· Venture Capital · 11 sources · Updated · Verified
AI Infrastructure Startups & Funding 2026: Companies, Rounds & Market Map
Track the AI infrastructure companies and funding rounds shaping 2026 across AI clouds, data centers, power, chips, networking, inference, databases and reliability.

Editorial team
Quick answer: AI infrastructure funding in 2026 is spreading across the full stack: AI clouds, data centers, power, networking, optical interconnects, chips, inference, databases, developer infrastructure and reliability software. The category is no longer synonymous with "GPU companies."
Deal details & investors
Funding event
Helix Digital Infrastructure
Led by Samsung Electronics
This page is VCT's evergreen AI-infrastructure market map. It separates venture equity, strategic investment, convertible financing, credit facilities and project/infrastructure capital instead of collapsing unlike instruments into a single inflated funding number.
AI infrastructure funding in 2026: the market map
| Layer | Companies VCT is tracking | What investors are underwriting |
|---|---|---|
| AI cloud / neocloud | CoreWeave, Nebius, IREN, Crusoe, Nscale, GMI Cloud, PaleBlueDot AI, DeepInfra, Baseten | GPU capacity, inference, utilization, enterprise demand |
| Data centers / power | Helix Digital Infrastructure, Fluidstack, Bluecore Energy | Sites, megawatts, energy access, power-to-compute conversion |
| Chips / compute | Positron AI, Efficient Computer, Volantis | Inference economics, memory bandwidth, power efficiency |
| Networking / interconnect | Celero Communications, Cornelis Networks, CScale | Scale-up/scale-out bandwidth and cluster reliability |
| Databases / data layer | Qdrant, Supabase | Retrieval, vector search, agent memory, developer workflows |
| Reliability / orchestration | Clockwork.io | Keeping distributed AI workloads running through failures |
Major 2026 AI infrastructure financing signals
| Company | Latest 2026 financing signal | Valuation / structure | Layer |
|---|---|---|---|
| Nebius | $5.75B convertible notes (August); $3.5B Citi facility (October) | Convertible bonds and secured debt. $40–45B projected 2027 capex is not money raised | AI cloud / neocloud |
| CoreWeave | $2.6B secured loan (August); $4.2B convertible notes (September) | Debt funding, not venture equity. $132.5B backlog is future contracted revenue, not cash | AI cloud / neocloud |
| Crusoe | $3.9B Series F | $30.9B valuation | AI data centers / neocloud |
| Nscale | $3.36B announced pre-IPO convertible notes | $2.36B at closing + $1B NVIDIA commitment | AI cloud / data centers |
| Fluidstack | Reported $1.5B financing | >$18B valuation | AI cloud / capacity |
| Helix Digital Infrastructure | $1B Samsung strategic investment | Strategic investment | Data centers + power + fiber |
| Positron AI | $875M Series C / C-1 | $5B valuation | Inference silicon |
| Modal | $750M Series D, October 14 | $15.75B post-money valuation | Serverless GPU compute / AI inference |
| Oxide Computer | $445M Series D, announced October 9 | $6B Forbes-reported valuation, not company-confirmed | Rack-scale private cloud hardware |
| Supabase | $500M Series F plus later $150M growth financing | $10.5B Series F valuation | Database / agent infrastructure |
| Baseten | $300M Series E | $5B valuation | Inference platform |
| Celero Communications | $275M Series C | >$3B valuation | Optical interconnect |
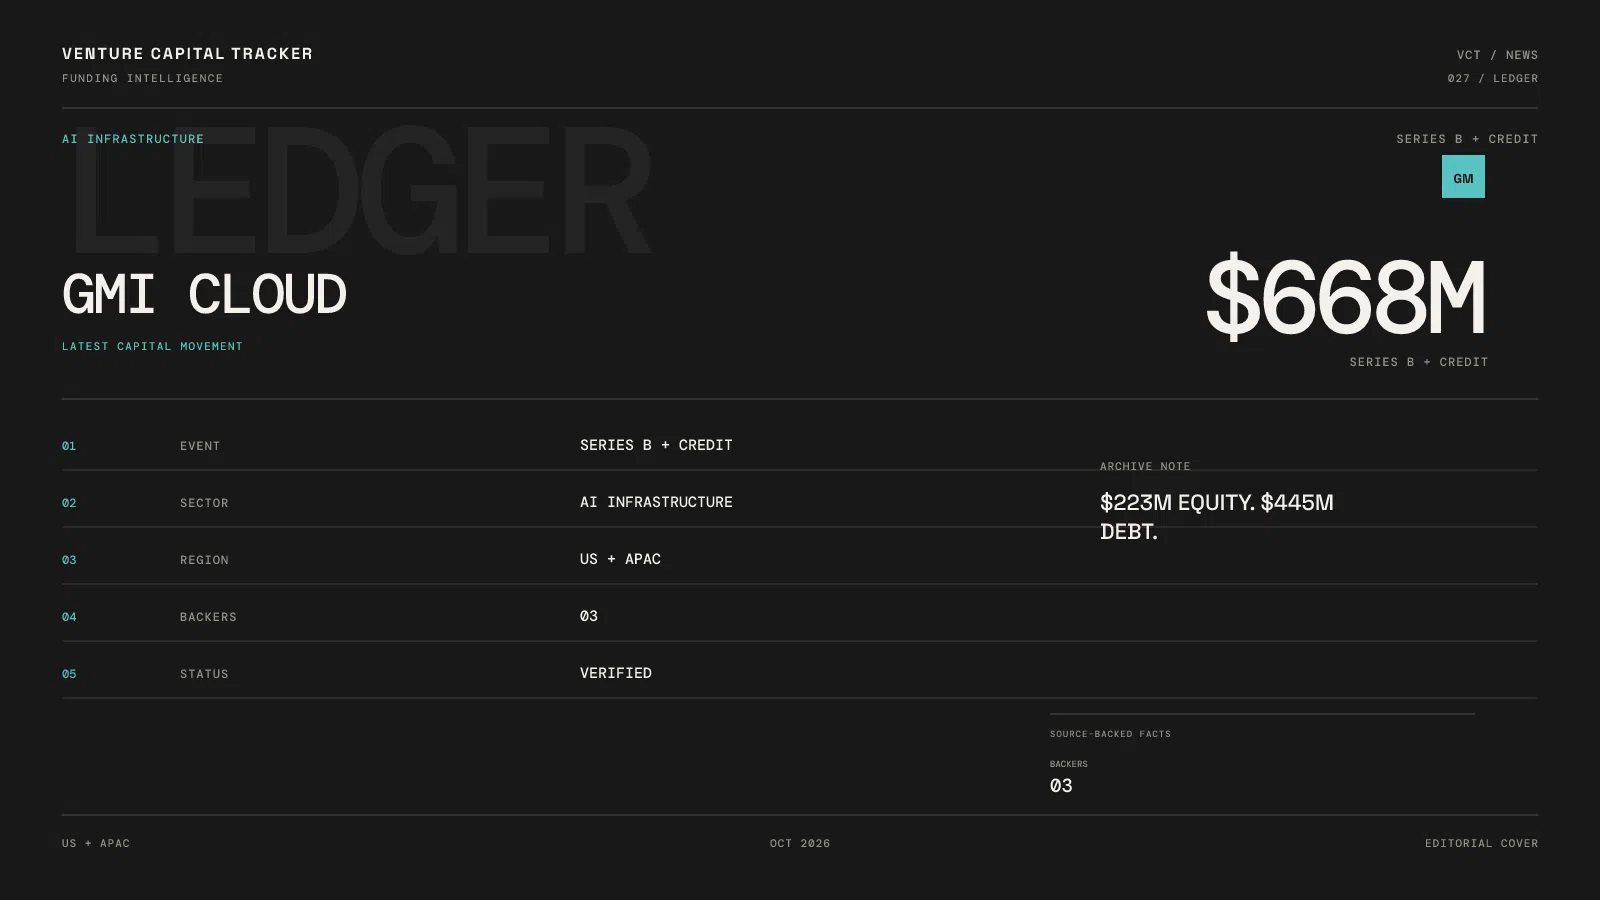
| GMI Cloud | $223M Series B equity + $445M credit facility | Equity and debt labeled separately | AI cloud |
| Cornelis Networks | $205M financing | Stage undisclosed | AI/HPC networking |
| PaleBlueDot AI | $200M Series C | $3.2B valuation | AI compute / serverless inference |
| CScale | $145M Series C | Undisclosed | Optical interconnect |
| DeepInfra | $107M Series B | Undisclosed | Managed inference cloud |
| Efficient Computer | >$97M Series B | $650M valuation | Energy-efficient processors |
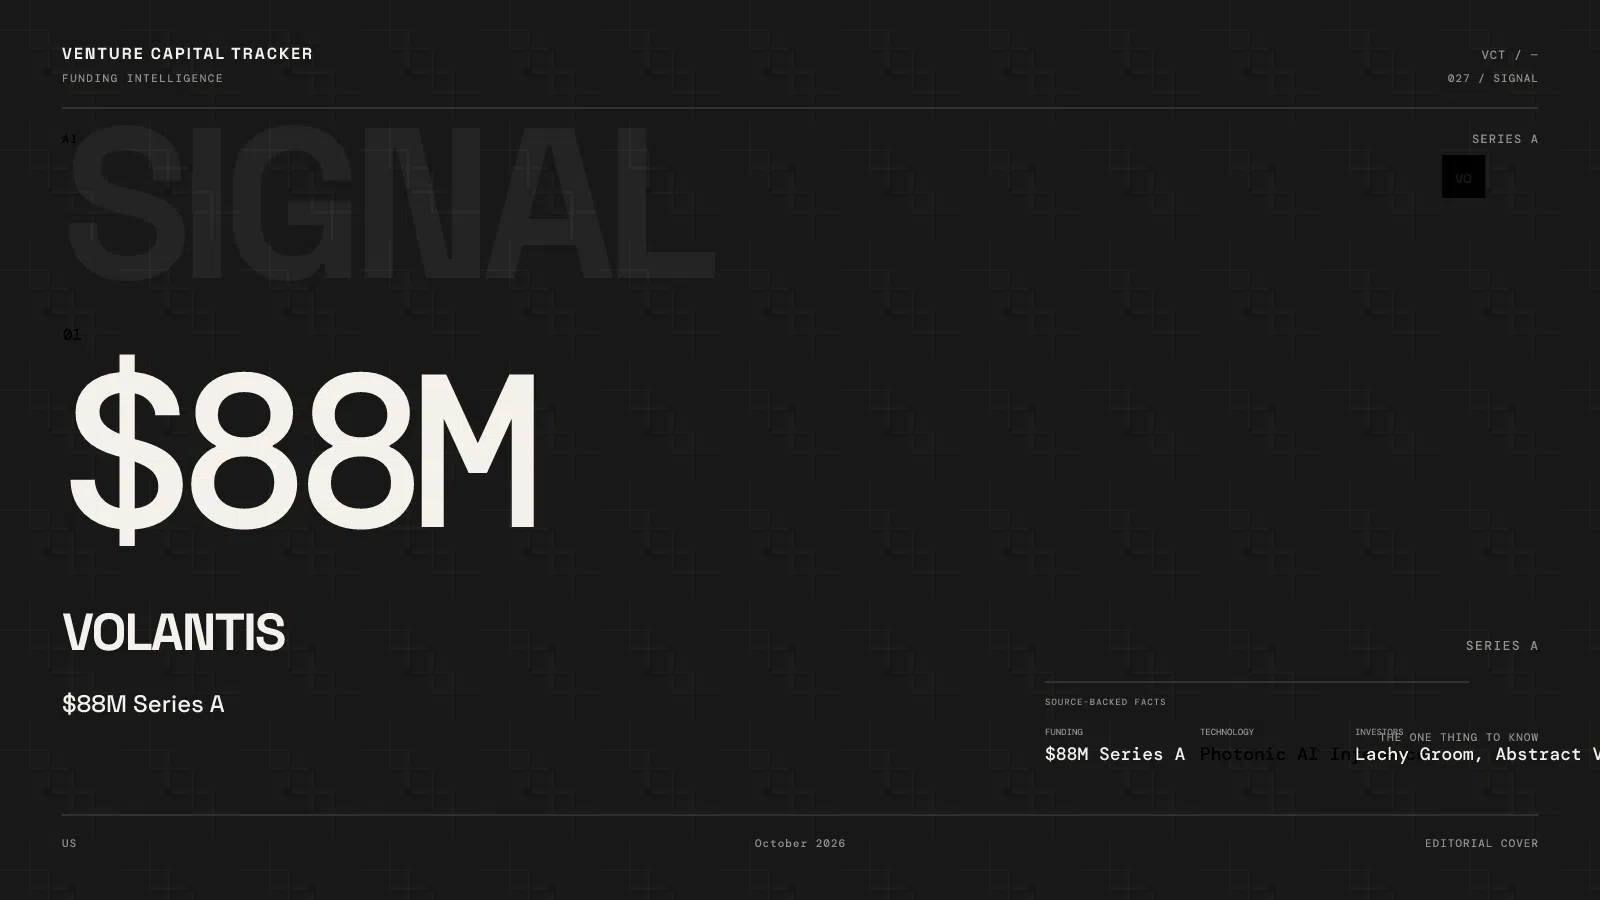
| Volantis | $88M Series A | Undisclosed | Photonic inference interconnect |
| Qdrant | $50M Series B | Undisclosed | Vector database / agent memory |
| Clockwork.io | $31M financing | Stage undisclosed | AI workload reliability |
The table deliberately mixes several financing structures because that is what the market actually looks like. The labels matter: Nscale's convertible notes, GMI Cloud's credit facility, Helix's strategic investment and Crusoe's priced equity are not economically interchangeable.
October 2026: two infrastructure funding milestones
Modal's $750 million Series D, announced October 14, 2026, was led by Accel at a $15.75 billion post-money valuation. Modal also reported annualized run-rate above $1 billion. That is a company-reported run-rate metric, not a separately audited revenue figure. The round supersedes its May $355 million Series C as Modal's latest financing.
Oxide Computer's $445 million Series D, announced October 9, 2026, backs rack-scale cloud systems that enterprises can own. The $6 billion valuation was reported by Forbes and was not part of Oxide's company announcement.
These two financings illustrate different infrastructure economics: recurring developer-platform demand for Modal versus capital-intensive physical system production for Oxide. Neither should be added to credit facilities or data-center project commitments as if all funding instruments were identical.
Funding analysis across the AI infrastructure stack
The company profiles in the market map show who participates in each layer. These underlying deal articles explain the actual financing instrument and the operating bottleneck it is intended to address.
- Cloud capacity, systems and power: GMI Cloud’s $223M Series B plus separate $445M facility and VEIR’s $110M Series C address very different infrastructure costs.
- Networking and memory bandwidth: CScale’s $145M Series C, Volantis’s $88M Series A and Cornelis Networks’ $205M financing show why interconnects can be as important as GPUs.
- Inference silicon and specialized finance: Positron AI’s $875M Series C, Efficient Computer’s $97M-plus Series B and USD.AI’s $128.9M GPU facility reflect different capital structures and economics. The GPU facility is debt-related financing, not an equity round.
What counts as AI infrastructure?
VCT uses a practical definition: a company belongs in the AI-infrastructure map if its product is part of the compute, data, networking, power or software layer required to train, deploy, serve or operate AI systems.
That includes more than physical infrastructure.
1. AI cloud and neocloud
The most capital-intensive companies are building GPU capacity and managed compute.
Crusoe, Nscale, GMI Cloud, Fluidstack and PaleBlueDot AI are different versions of that thesis.
The investor question is increasingly not "does the company have GPUs?" but:
- what power and capacity are contracted;
- how much compute is actually online;
- who the customers are;
- what utilization looks like;
- whether contracts justify the capital stack;
- and whether the company can earn acceptable returns after hardware depreciation and financing costs.
That is why debt and infrastructure finance show up alongside venture equity in this category.
2. Inference platforms
Baseten and DeepInfra sit higher in the stack. They sell the developer-facing layer for deploying and serving models rather than only raw GPU capacity.
The investment thesis is that inference becomes a recurring software and orchestration problem even as the underlying accelerator market changes.
The risk is compression. Hyperscalers, model providers and GPU clouds can all move into the serving layer. Durable businesses need an advantage in performance, developer experience, workload orchestration, model coverage or enterprise reliability.
3. Chips and compute efficiency
Positron AI, Efficient Computer and Volantis illustrate three different bottlenecks.
- Positron focuses on memory-first inference hardware.
- Efficient Computer is pursuing energy-efficient processor architecture.
- Volantis is targeting the memory wall with photonic interconnect.
The important shift is that "AI chip startup" no longer means "another general-purpose NVIDIA challenger." Many companies are attacking narrower constraints where economics can be measured directly: memory movement, inference throughput, interconnect, power consumption or latency.
4. Networking and optical interconnect
Large AI clusters fail if accelerators cannot communicate efficiently.
Celero Communications, Cornelis Networks and CScale sit in this layer.
As cluster sizes move toward tens of thousands of accelerators and beyond, networking becomes part of the compute economics. A GPU sitting idle because data cannot move efficiently is wasted capex.
That is why investors are willing to fund companies that improve bandwidth, latency, fault tolerance and scale-up/scale-out architectures.
5. Data centers and power
Helix Digital Infrastructure, Fluidstack and Bluecore Energy show why AI infrastructure is now partly an energy-and-real-estate market.
The limiting resource is often not the accelerator itself. It can be:
- grid interconnection;
- megawatts available at the site;
- cooling;
- fiber connectivity;
- construction speed;
- or the ability to finance capacity before customer revenue begins.
Power access is therefore becoming a competitive advantage.
6. Databases, retrieval and agent memory
Not all infrastructure is measured in megawatts.
Qdrant and Supabase sit in the application/data infrastructure layer used by developers building AI products.
Vector search, retrieval, databases, auth, storage and agent memory are less capital-intensive than GPU clouds, but they can become sticky control points in software architectures.
This layer is where AI infrastructure starts to overlap with traditional developer tools.
7. Reliability and orchestration
Clockwork.io represents a problem that becomes more valuable as clusters get larger: failures are normal.
Distributed training and inference systems need to survive GPU, networking and infrastructure faults without constantly restarting expensive workloads.
The key metric here is not just software adoption. It is how much expensive compute time the product saves.
The biggest mistake: treating all "AI funding" as venture equity
AI infrastructure companies often use financing structures that would be unusual for an ordinary SaaS startup.
A company may raise:
- priced venture equity;
- convertible notes;
- equipment financing;
- project finance;
- asset-backed debt;
- a credit facility;
- customer prepayments;
- strategic investment;
- or a long-term infrastructure commitment.
Adding all of those together and calling the result "venture funding" creates nonsense.
Example: GMI Cloud
GMI Cloud announced a $223 million Series B equity round alongside a $445 million credit facility.
The combined capital availability matters operationally, but the equity investors are not buying the same instrument as the lenders.
Example: Nscale
Nscale announced $3.36 billion of pre-IPO convertible notes, including $2.36 billion at closing and a $1 billion NVIDIA commitment.
That is a very different financing structure from Crusoe's $3.9 billion Series F.
Example: Helix
Samsung affiliates committed $1 billion to Helix as a strategic investment. Strategic industrial relationships may have value beyond financial capital, but they should still be labeled accurately.
VCT keeps those distinctions visible.
What investors should track beyond valuation
Valuation is often the least interesting number in AI infrastructure.
For AI clouds and data centers
Track:
- megawatts contracted;
- megawatts energized;
- GPU capacity installed;
- utilization;
- contracted backlog;
- customer concentration;
- debt load;
- capex per deployed unit;
- and time from capital commitment to revenue-generating capacity.
For chips and networking
Track:
- tape-out / manufacturing progress;
- benchmark performance;
- watts per workload;
- memory bandwidth;
- networking throughput;
- design wins;
- customer qualification;
- and production shipments.
For software infrastructure
Track:
- inference volume;
- workload retention;
- gross margins;
- developer adoption;
- enterprise usage;
- latency/performance;
- and switching costs.
Different layers require different operating metrics. A common "AI startup score" is not useful.
2026 market signals
Several things are becoming clearer.
Capital is concentrating around bottlenecks
The largest rounds are flowing toward companies that control a constrained input: power, data-center capacity, inference silicon, networking or production deployment.
Infrastructure companies increasingly have hybrid capital stacks
As physical capex rises, equity alone becomes an inefficient funding source. Expect more combinations of equity, credit, strategic investment and project capital.
NVIDIA can be customer, supplier, investor and ecosystem gatekeeper
NVIDIA appears across many 2026 financing stories not simply as a chip vendor but as a strategic investor or ecosystem partner. That creates useful validation but also concentration risk.
The software layer is not disappearing
Huge physical-infrastructure rounds can obscure the fact that databases, inference serving, orchestration and reliability can create much higher-margin control points above the hardware.
The market is likely to support both.
Companies to watch by layer
AI cloud / compute
Chips and interconnect
Power and data centers
Data and developer infrastructure
Reliability
Methodology
This page is built from VCT's structured company records and primary funding sources where available.
A company is included when it has a meaningful role in the AI infrastructure stack and VCT has enough evidence to classify its product and financing accurately.
The list is intentionally curated, not exhaustive. Hundreds of startups can plausibly describe themselves as AI infrastructure; the goal is to map important control points and financings, not generate a directory full of marginally related companies.
Frequently asked questions
What is an AI infrastructure startup?
An AI infrastructure startup builds part of the technical or physical stack required to train, deploy, serve or operate AI systems. That can include compute clouds, chips, networking, data centers, power, databases, inference software and reliability tooling.
Which AI infrastructure startups raised the largest rounds in 2026?
Among the financings VCT tracks, Crusoe announced a $3.9B Series F, Nscale announced $3.36B of pre-IPO convertible notes, Fluidstack was reported to raise $1.5B at a valuation above $18B, and Helix received a $1B strategic investment from Samsung affiliates.
Is AI infrastructure funding the same as venture capital funding?
No. The category uses equity, debt, convertible notes, project finance, strategic investment and other structures. VCT labels financing types rather than adding unlike instruments into one venture-funding total.
Why are AI infrastructure companies raising so much capital?
Many need to secure scarce accelerators, construct or lease data-center capacity, obtain power, finance hardware, and build global infrastructure before all capacity generates revenue. That produces much larger capital requirements than ordinary software startups.
Which AI infrastructure layer may have the best economics?
There is no single answer. Physical infrastructure can control scarce capacity but requires enormous capital. Software layers such as inference, databases and orchestration can have better gross margins but face intense platform competition. The key is whether a company owns a durable control point.
November 2026: customer-financed AI cloud
CoreWeave and Nebius show how AI infrastructure finance combines customer advances, equipment-backed loans, convertible bonds and equity. The headline figures are not all amounts of fresh investment.
- Nebius Q3 2026: $40–45B capex forecast, customer prepayments and Microsoft-linked delivery delays explains the ~$325M one-off revenue item, Vineland delays and what is already funded.
- CoreWeave Q3 2026: $132.5B backlog, expected $9B in deposits and $47.5B debt explains backlog versus cash and adjusted EBITDA versus net income.
- CoreWeave vs Nebius: who pays for the AI data center boom? compares the financing stack, underlying business risks and what to track next.
- Neocloud companies and stocks: full 2026 operator map distinguishes public GPU clouds, private startups and data-center landlords.
- GPU financing explained compares rated asset-backed facilities, debt pricing and customer advances.
Classification matters: Nebius's 2027 capex plan is projected spending, and CoreWeave's expected deposits are customer finance, not new venture funding. Debt facilities have different drawdowns and interest terms. The linked analyses cite SEC filings and company disclosures.
What VCT will update next
This hub will be updated as new financings arrive. VCT will continue to separate:
venture equity → strategic investment → convertibles → credit/debt → infrastructure commitments → acquisitions
and link each material financing to the relevant permanent startup profile.
Further 2026 coverage and deal context
Last updated:
Editorial note: AI tools assisted with research, structure, or drafting. Venture Capital Tracker retains human editorial responsibility for factual accuracy, relevance, and source quality before publication.