· Venture Capital Tracker Editorial
Valon Raises $150M at $2.3B for Mortgage AI
Valon raised a $150 million Series D at a $2.3 billion valuation to expand ValonOS and AI agents across mortgage origination and servicing.
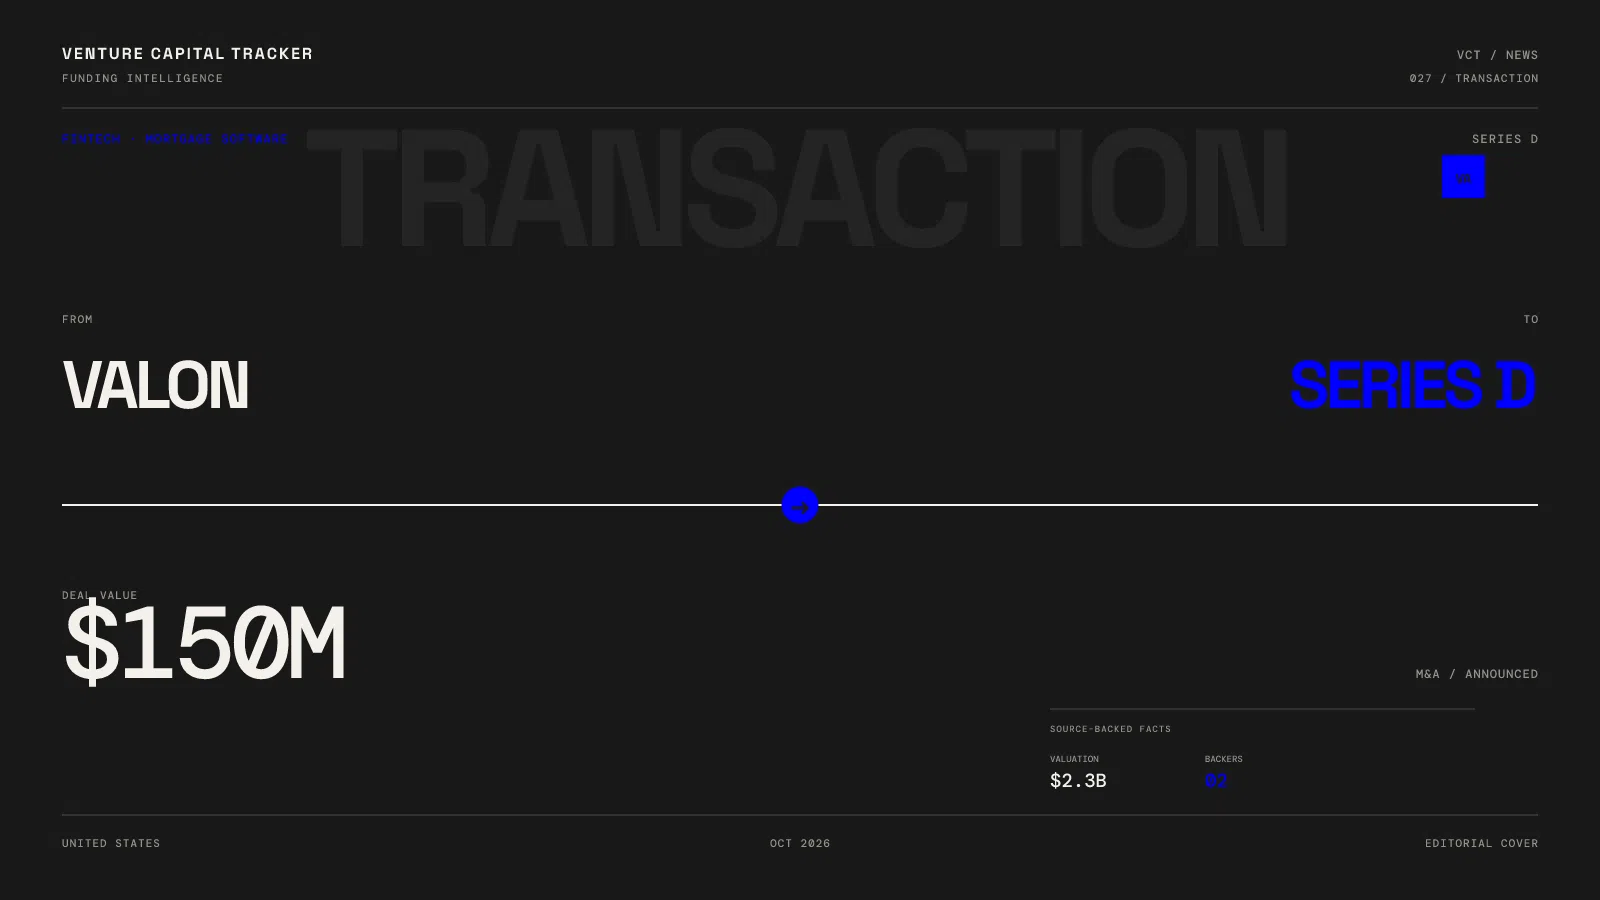
Valon Technologies has raised a $150 million Series D at a $2.3 billion valuation, giving the mortgage-software company fresh capital to expand ValonOS and its AI agents across origination, servicing and consumer lending.
Ribbit Capital joined as a new investor and Andreessen Horowitz participated again. The round follows Valon’s $100 million Series C in October 2024, when the company was valued at $1.1 billion. In roughly two years, Valon has therefore more than doubled its private-market valuation while shifting its pitch from a technology-enabled mortgage servicer to a broader software platform for financial institutions.
Valon Series D at a glance
- Financing: $150 million Series D
- Valuation: $2.3 billion
- Investors: Ribbit Capital and Andreessen Horowitz
- Use of proceeds: Product development and deployment of ValonOS and AI agents
- Status: Company-announced and confirmed
Valon says its software now supports one in six US mortgages and that it signed more than $200 million of contracted annual recurring revenue in six months. Those are company-reported figures, not independently audited results. They nevertheless help explain why investors are assigning a software multiple to a business that began inside the operationally intensive mortgage-servicing market.
The strategic shift behind Valon's valuation
Valon’s most important change is structural. Carrington Mortgage Services agreed in 2025 to acquire Valon’s mortgage-servicing subsidiary, while Valon Technologies remained an independent software company. That separation lets Valon sell the operating system without asking customers to outsource servicing to a direct competitor.
It also changes the economics investors are underwriting. Mortgage servicing can produce recurring revenue, but it is capital-intensive, regulated and exposed to interest-rate cycles. A software layer licensed to banks, servicers and lenders can have higher gross margins and a much larger addressable market—if deployments become repeatable.
ValonOS covers servicing operations, borrower communications and workflow automation. The company is now extending the same infrastructure into origination and consumer lending. Its AI agents are intended to handle tasks such as document review, customer support and back-office workflows while keeping regulated institutions in control of approvals.
Why mortgage servicing is an AI market
Mortgage servicing has high call volumes, legacy databases and document-heavy processes. It also has strict audit requirements. Errors can be expensive because servicers must comply with federal and state rules covering payments, escrow, loss mitigation and borrower communications.
That makes the market defensible but difficult. A general-purpose AI assistant cannot simply be connected to a loan book. Customers need reliable data models, permissioning, logging, human escalation and reproducible decisions. Valon’s operating history gives it process data and domain expertise that horizontal AI vendors may lack.
The competitive set is also unusually entrenched. ICE Mortgage Technology, including the former Black Knight platform, and Sagent serve large parts of the US mortgage industry. Banks and non-bank servicers have spent years integrating those systems. Valon must prove that its productivity gains justify migration risk and implementation costs.
What the new capital must prove
The $2.3 billion valuation will ultimately depend less on announced contracts than on converting them into durable software revenue. Contracted ARR can include deployments that have not yet reached full production, so the pace of implementation matters.
Investors should watch five indicators:
- Revenue conversion: How quickly contracted ARR becomes recognized recurring revenue.
- Deployment time: Whether Valon can onboard large institutions without lengthy custom projects.
- Software margins: Whether separating the servicing subsidiary produces a genuinely scalable margin profile.
- Customer concentration: Whether growth is spread across multiple banks and servicers.
- Regulatory performance: Whether AI-driven workflows reduce costs without increasing complaint, audit or error rates.
Valon has raised enough capital to compete for major institutions, but the next phase is execution-heavy. The company is trying to replace systems that sit at the center of regulated balance sheets. Winning those customers could make ValonOS a significant financial-infrastructure platform; failed or slow deployments would make the new valuation harder to sustain.
The bottom line
Valon’s Series D is not just another large AI round. It is a bet that one of the least modernized parts of US financial infrastructure can be rebuilt as enterprise software. The company’s servicing roots are a valuable distribution and data advantage. The $2.3 billion valuation now sets a high bar for converting that experience into repeatable, high-margin software revenue.
Editorial note: AI tools assisted with research, structure, or drafting. Venture Capital Tracker retains human editorial responsibility for factual accuracy, relevance, and source quality before publication.