Agilent Agrees to Acquire Proscia for $240M Plus Earnout
Agilent signed a definitive agreement to acquire digital-pathology software company Proscia for $240 million at closing plus up to $30 million in performance payments.
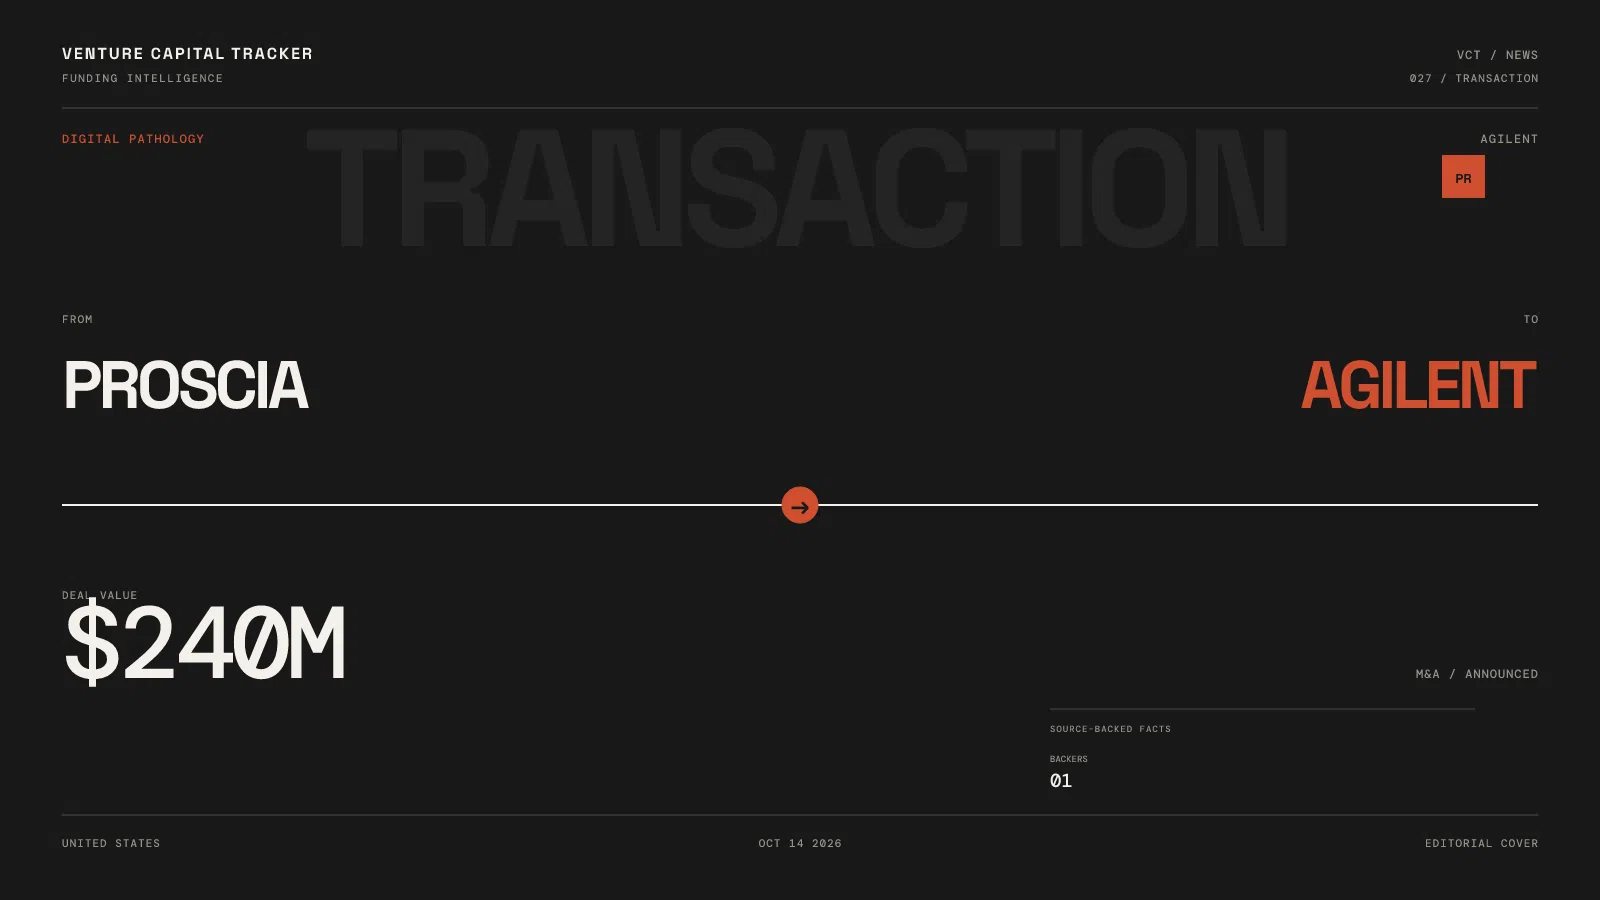
Agilent Technologies has signed a definitive agreement to acquire digital-pathology software company Proscia for $240 million in cash at closing, plus up to $30 million in performance payments.
The transaction has not closed. It remains subject to customary conditions and is expected to complete early in Agilent's fiscal 2027. Proscia will then join Agilent's Life Sciences and Diagnostics Markets Group.
Transaction terms
| Item | Detail |
|---|---|
| Upfront consideration | $240 million cash |
| Additional consideration | Up to $30 million tied to performance |
| Maximum value | Up to $270 million |
| Status | Definitive agreement; not closed |
| Expected timing | Early Agilent fiscal 2027 |
The earnout should not be treated as guaranteed purchase price. The confirmed amount payable at closing is $240 million, assuming the transaction completes.
Why Agilent wants a software layer
Proscia's Concentriq platform connects slide scanners, laboratory information systems, image-analysis applications, AI tools, personnel and pathology data. The company describes it as vendor-agnostic, which allows laboratories to combine equipment and software from multiple providers.
Agilent already sells pathology instruments, staining systems and related diagnostics products. Adding Proscia could connect those physical workflows to a software control plane and a repository of real-world pathology data. Agilent intends to use that combination across diagnostics, biomarker research, companion diagnostics and drug development.
The companies are not starting from zero: they have worked together under a commercial distribution relationship since 2022.
Commercial profile and implied multiple
Proscia reported more than $18 million in trailing-twelve-month revenue. Using only the $240 million upfront price, the transaction values the company at more than 13 times that revenue. At the full $270 million potential consideration, the multiple reaches 15 times.
Those simple ratios do not adjust for cash, debt or the precise earnout conditions, but they show that Agilent is paying for strategic software value and growth rather than current earnings alone.
Proscia says its products are used by more than 4,000 laboratories, hospitals and clinics and by 16 of the top 20 pharmaceutical companies. These are company-reported adoption figures.
Integration risk
The strategic appeal is clear: Agilent can pair instruments and reagents with recurring software and data workflows. The tension is openness. Proscia's value to customers partly comes from connecting heterogeneous scanner and analysis systems. If ownership makes the platform appear less neutral, competing hardware vendors or laboratories may hesitate.
Agilent must therefore preserve Proscia's vendor-agnostic position while creating commercial advantages from the combination. Until closing, Proscia remains an independent private company and the transaction should be described as an acquisition agreement, not a completed sale.
Follow Venture Capital Tracker in Google
Add VCT as a preferred source to make our venture-capital coverage easier to find in Google Search.
Editorial note: AI tools assisted with research, structure, or drafting. Venture Capital Tracker retains human editorial responsibility for factual accuracy, relevance, and source quality before publication.