· Investment Strategies · 2 sources · Updated · Verified
Open Cosmos’s €300M Series C: Profitable European Satellites at Factory Scale
Open Cosmos closed €300M (~$351M) Series C led by ETF Partners on September 14, 2026 — with LocalGlobe’s Phoenix Court in the syndicate — after five years of profitable growth, $370M+ contracts, and one-satellite-per-day manufacturing capacity (company).

By Venture Capital Tracker Editorial
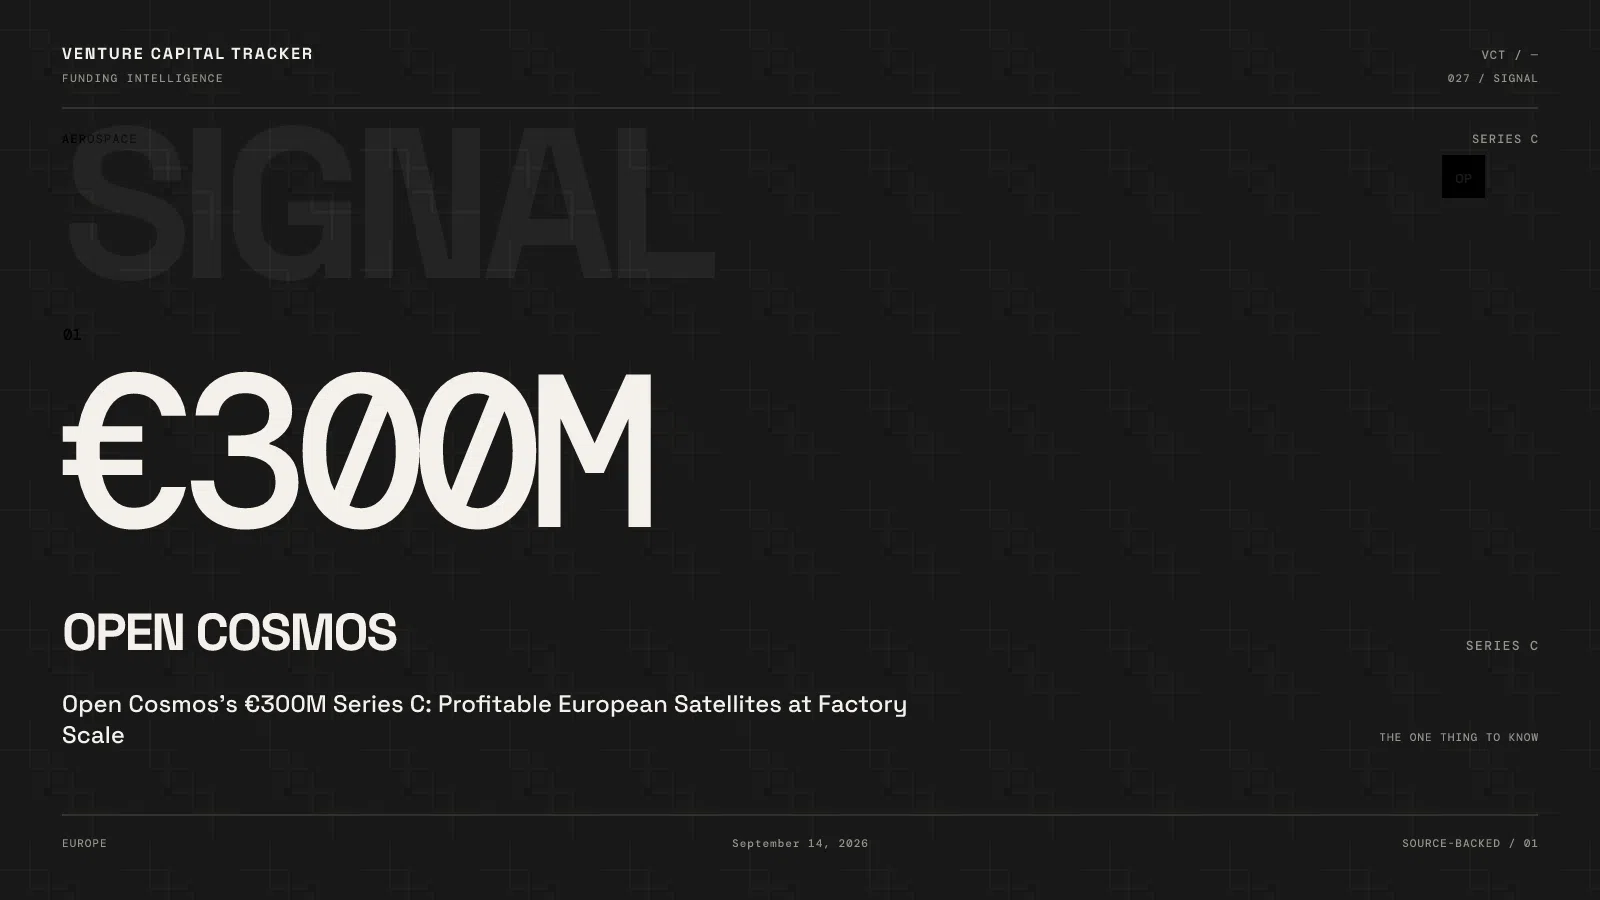
Open Cosmos secured €300 million (~$351M) in Series C funding on September 14, 2026, led by ETF Partners, with Lightrock, ICF, Entrepreneurs First, two major pension funds, and Phoenix Court (home of LocalGlobe and Latitude) among a long European syndicate (ETF Partners).
A European sat manufacturer that already claims profits + factory throughput + $370M+ contracts just took a climate/sovereignty specialist’s lead check — space as infrastructure, not a science project.
Key facts
- Company
- Open Cosmos — Harwell Campus, UK; ops in ES/PT/GR
- Round
- €300M (~$351M) Series C; valuation n/d
- Lead
- ETF Partners
- Named syndicate (partial)
- Lightrock, ICF, EF, Phoenix Court (LocalGlobe/Latitude), NSSIF, Trill Impact, Endeavor Catalyst, Santander AI, Shilling, Amena, Claret, pensions, others
- Traction (company)
- $370M+ contracts / 3.5 years; 5 years profitable growth; 1 sat/day capacity; ~400 people
- Platforms
- OpenOrbit, OpenConstellation, ConnectedCosmos, DataCosmos
- Use of proceeds
- Mass manufacturing + expand constellation intelligence/connectivity
The supplier side of spacecraft manufacturing is developing alongside integrated operators. MP Space’s October 2026 seed round funds battery production, while Solestial’s May 2025 Series A supports solar manufacturing. These component suppliers address different parts of the power system; neither financing establishes Open Cosmos as a customer.
Who uses the product — and for what job
Users: Governments and agencies that need sovereign EO and communications; energy and infrastructure operators that need orbital monitoring without owning a full constellation program.
Job today: Design/build/operate missions; shared OpenConstellation capacity; ConnectedCosmos links; DataCosmos intelligence that aims to cut EO delivery from up to 48 hours toward ~30 minutes with onboard AI (company).
Job example (company narrative): Detect a forest temperature anomaly, classify risk onboard, relay via ConnectedCosmos to responders even without terrestrial internet — sensing + connectivity + AI as one system.
Why now
- European governments are treating space as critical infrastructure for autonomy and security, not optional R&D.
- Global space VC hit $11.3B in H1 2026 alone (ETF Partners citing sector data) — capital is available for operators that already sell, not only for launch memes.
- Open Cosmos’s claimed profitability + manufacturing cadence is the anomaly vs cash-burning constellation peers.
Why ETF Partners — and LocalGlobe’s seat
ETF Partners (Environmental Technologies Fund) has spent two decades underwriting climate-adjacent infrastructure. Open Cosmos sells environmental and operational intelligence from orbit — wildfire, energy, infrastructure — so the lead fits a sustainability-meets-infrastructure mandate more cleanly than a pure defense-only fund.
LocalGlobe via Phoenix Court is the London early/growth platform that likes ambitious European technical founders. Participation (not lead) keeps LocalGlobe on a scaled UK space manufacturer without owning the climate-infra lead narrative.
NSSIF and Catalan/public capital in the list underline the sovereign buyer story that pure commercial VCs alone cannot close.
Competitive map
| Approach | Tradeoff |
|---|---|
| U.S. mega-constellations | Scale and capital; sovereignty and export-control friction for EU buyers |
| National agency programs | Full control; slow and expensive |
| EO pure-plays without manufacturing | Software margins; dependent on third-party buses |
| Open Cosmos integrated stack | Factory + services; must keep mission success and contract conversion high |
What is not proven
- Valuation, dilution, and which “two major international pension funds.”
- Audited confirmation of profitability and $370M+ contract figures (company-disclosed).
- Independent proof of 30-minute intelligence SLAs at constellation scale.
Practical takeaway
- Founders (European space): Lead with contracts + manufacturing cadence + profit, not constellation slideware — climate and sovereign funds will write €100M+ checks.
- Investors: Diligence backlog quality vs announced capacity; Phoenix Court is a soft signal, ETF is the thesis owner.
- Government / enterprise buyers: Relevant if you need interoperable EO + connectivity without standing up a national OEM.
Follow Venture Capital Tracker on Google
Add VCT as a preferred source to see more of our venture-capital reporting in Google Search.
Last updated:
Editorial note: AI tools assisted with research, structure, or drafting. Venture Capital Tracker retains human editorial responsibility for factual accuracy, relevance, and source quality before publication.