· Venture Capital Tracker · venture-capital
Stryker Commits $400M to CMR Surgical and Secures a Buyout Option
Stryker agreed to invest approximately $400 million in CMR Surgical, become the exclusive U.S. commercial agent for Versius and secure an option to acquire the rest of the company.
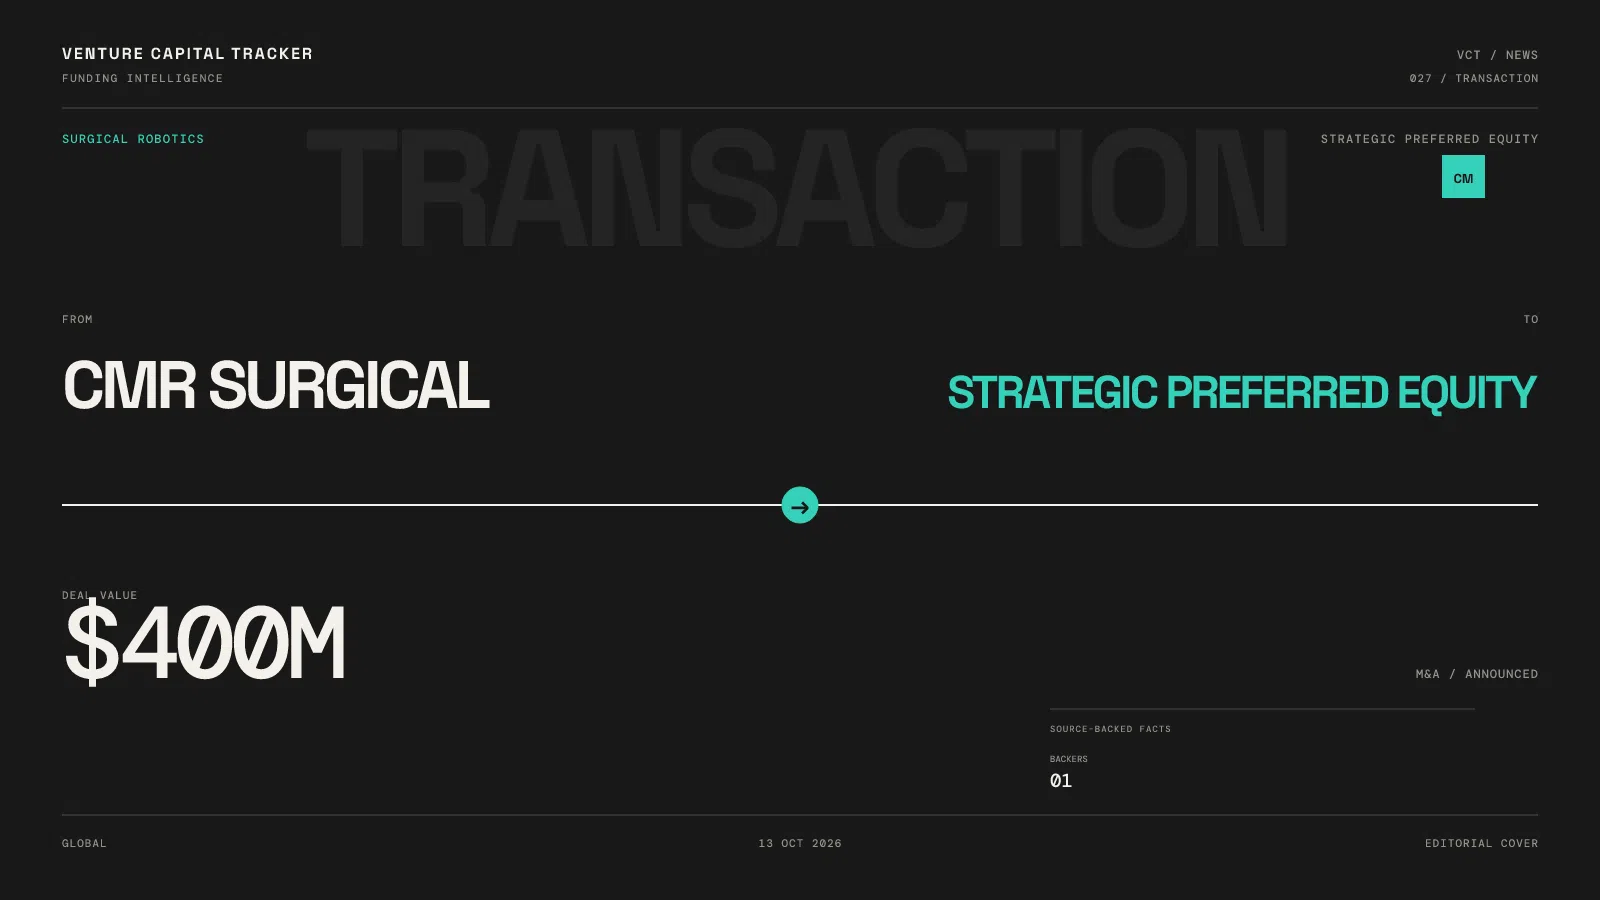
Stryker has agreed to make an approximately $400 million (£300 million) preferred-equity investment in CMR Surgical, pairing the capital with an exclusive U.S. commercial agreement and an option to acquire the remaining equity later.
The structure matters. This is not a completed acquisition, and the investment itself remains subject to customary closing conditions. But it moves CMR much closer to a strategic endgame: Stryker receives a financial stake, control of U.S. commercialization for the Versius robotic-surgery platform and contractual exclusivity over a future purchase.
The transaction at a glance
| Item | Detail |
|---|---|
| Investor | Stryker |
| Company | CMR Surgical |
| Financing | Approximately $400M preferred equity |
| Status | Announced; subject to closing conditions |
| Commercial component | Stryker becomes exclusive U.S. commercial agent for Versius |
| Strategic option | Stryker receives an exclusive option to acquire all remaining CMR equity |
| Valuation | Not disclosed by the companies |
The companies did not disclose the option price, exercise window, ownership percentage or governance protections attached to the preferred shares. The Times reported that the investment represents roughly 10% of CMR and implies a valuation near $4 billion, but those figures are reported estimates rather than company-confirmed terms.
Why Stryker is paying for access before buying control
CMR’s Versius platform gives Stryker an entry into soft-tissue robotic surgery without requiring an immediate takeover. That is strategically useful in a market where the clinical workflow, service network and surgeon-training model can be as important as the robot itself.
The commercial-agency component lets Stryker apply its U.S. hospital relationships while CMR continues developing the system and operating internationally. If U.S. adoption validates the platform, the buyout option offers a path to full ownership. If adoption disappoints, Stryker has limited its initial commitment to a minority preferred-equity position.
For CMR, the partnership substitutes a scaled medical-device distribution network for the expensive process of building one from scratch. It also funds product development and global commercialization after Versius Plus entered the U.S. market.
The operating evidence—and what remains unproven
CMR said in April that more than 45,000 patients had been treated with Versius worldwide. That is meaningful installed-use evidence for an independent surgical-robotics company, although it is a company-supplied cumulative metric rather than a measure of recurring revenue or system utilization.
The U.S. opportunity remains early. CMR’s first-generation system received FDA marketing authorization for cholecystectomy, and Versius Plus subsequently received 510(k) clearance. Broader indications, hospital procurement cycles, surgeon training and service reliability will determine whether the platform can translate regulatory clearance into durable adoption.
The deal also concentrates CMR’s U.S. route to market in one strategic partner. That can accelerate distribution, but exclusivity reduces flexibility if the relationship underperforms.
What investors should watch
Three milestones now matter more than the headline amount:
- Closing and final ownership: the companies have not said when the preferred-equity transaction will close or confirmed the resulting stake.
- U.S. utilization: installed systems and procedure growth will be more informative than regulatory clearance alone.
- Option mechanics: the valuation formula and timing for a potential full acquisition remain undisclosed.
The financing is therefore best read as a staged strategic transaction, not a conventional venture round. Stryker is paying for a seat at the table, a distribution role and the right—but not the obligation—to buy the rest later.
Bottom line
CMR gains substantial capital and a credible U.S. commercialization engine. Stryker gains exposure to a differentiated surgical-robotics platform without immediately assuming full acquisition risk. The decisive question is whether Versius can build enough U.S. procedure volume to make the option worth exercising.
Follow Venture Capital Tracker in Google
Add VCT as a preferred source to make our venture-capital coverage easier to find in Google Search.
Editorial note: AI tools assisted with research, structure, or drafting. Venture Capital Tracker retains human editorial responsibility for factual accuracy, relevance, and source quality before publication.