
Startup profile · funding coverage
Megaport funding, valuation and investors
Publicly listed Network-as-a-Service provider expanding into CPU/GPU compute and storage after acquiring Latitude.sh.
Verified company research · funding, investors and latest developments
Keep track of Megaport
Save this profile to your VCT watchlist for a quick return.
Funding, valuation & investors
Answer-first snapshotLatest funding
Not publicly disclosed
Latest known valuation
Not publicly disclosed
Total disclosed equity funding
Not publicly disclosed
Excludes debt, grants, acquisitions, secondaries, and IPO proceeds.
Current status
public
public · Brisbane, Queensland, Australia
Overview
Founded in Brisbane by Bevan Slattery in 2013 and listed on Australia's ASX in December 2015, Megaport Limited (ASX: MP1) operates programmable private connectivity between cloud platforms, data centers and corporate networks. With the Latitude.sh acquisition (November 2025) and Extreme IX transaction, it added dedicated CPU/GPU compute, storage and an India network presence.
As of 30 June 2026 it reported 1,200+ enabled data centers in 31 countries and 4,000+ customers. On 29 September 2026 it reported Network ARR A$302.6M, Compute ARR US$141.0M (A$201.4M), billed Group ARR over A$500M and pro forma Group ARR of about A$1.1B including contracted future capacity. These are different metrics.
Three new AI infrastructure deals added A$978.6M total contract value and A$322.6M prepayments, raising the cumulative disclosed strategic TCV since April to approximately A$2.3B. FY27 company guidance: A$720M-A$810M revenue and A$1.78B-A$1.88B capex, not realized earnings. Sources: Megaport investor relations FY26 and ASX announcement of 29 September 2026.
Why Megaport is interesting
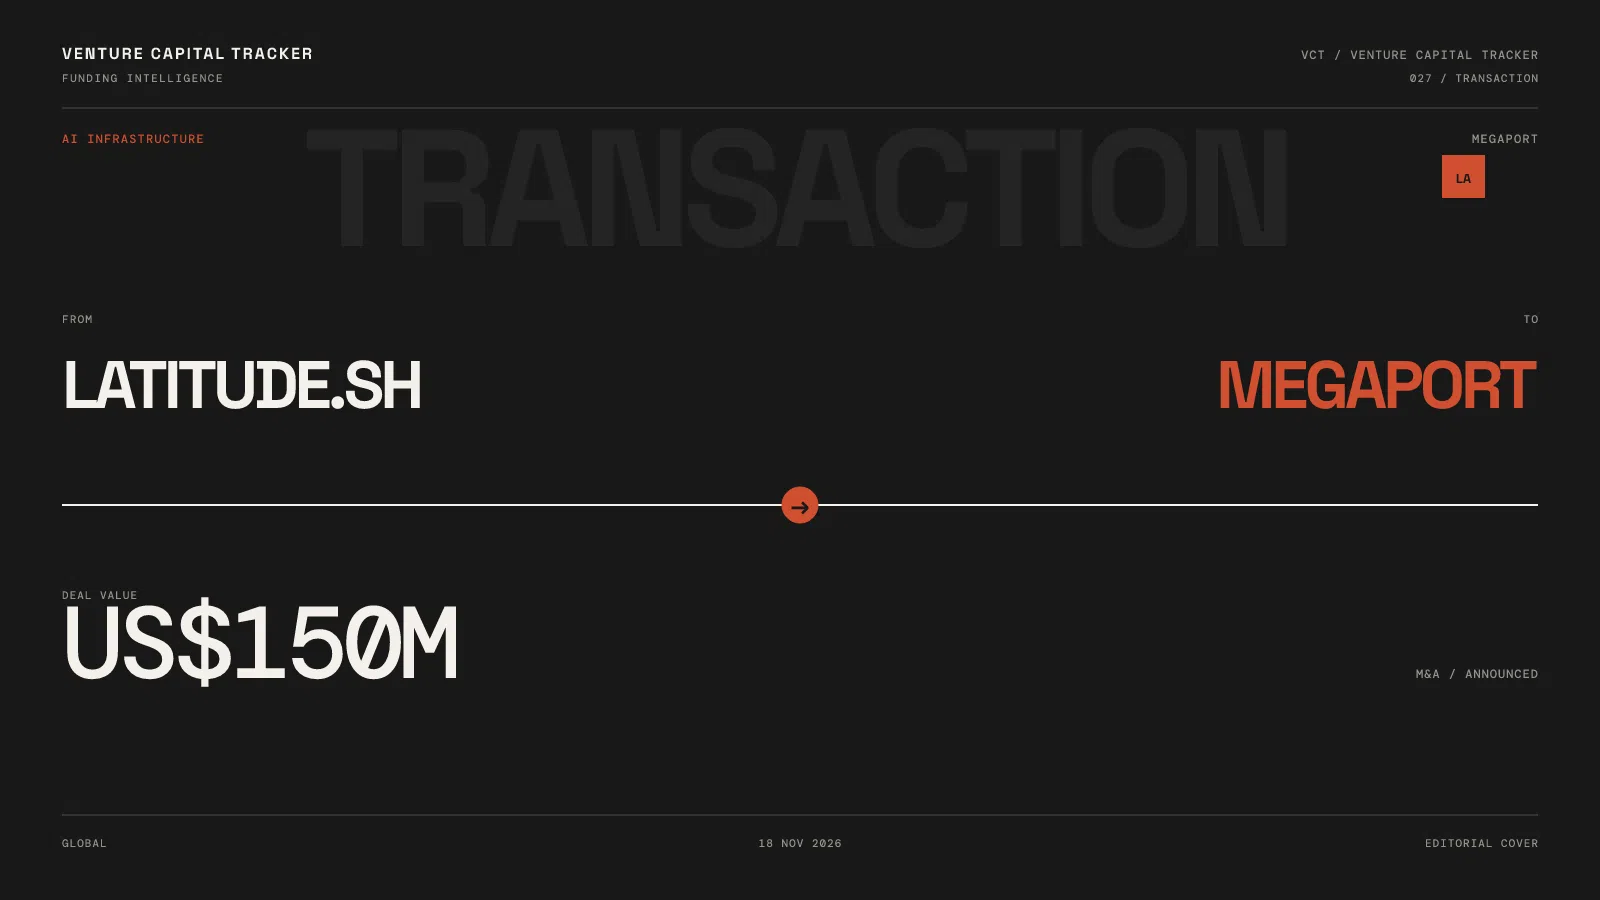
Megaport acquired Latitude.sh in 2025 for US$150M upfront plus an earnout capped at US$150M; its Compute ARR rose from US$43.1M before the acquisition to US$141M by 22 September 2026. Large AI contracts and capital expenditure create an unusual hybrid of network SaaS economics and asset-heavy GPU cloud infrastructure.
Product & use cases
Programmable Network-as-a-Service (virtual cross connects, cloud routers, virtual edges, internet exchange, private cloud interconnects), plus dedicated CPU/GPU servers and storage via its Latitude.sh subsidiary.
- Connect clouds, on-premises systems and data centers via private networks.
- Deploy performance-sensitive enterprise workloads and AI inference/training on dedicated CPUs or GPUs.
- Combine private interconnection with compute and storage for distributed AI.
Key facts
- A$395.2M ARR (30 June 2026); 1,200+ enabled data centers and 4,000+ customers.
- Compute ARR US$141.0M at 22 Sep 2026, +227% vs US$43.1M September 2025 pre-acquisition baseline.
- Sep 2026: A$978.6M new AI infrastructure contract value and A$322.6M customer prepayments; ~A$2.3B cumulative strategic contract value since April.
- FY27 projected revenue A$720M-A$810M, capex A$1.78B-A$1.88B (September guidance, not actuals).
- October 12, 2026: Megaport added Portugal to its international network ecosystem. October 22: AWS and Megaport announced a preview for AWS Interconnect – last mile; AWS still described Megaport's Northern Virginia availability as a preview on November 5, 2026.
Related reading
Explore the analysis behind recent funding rounds and company developments.
Competitive landscape
Edge: Megaport combines an established global software-defined network footprint with Latitude.sh's programmable compute. The potential for private-network differentiation is strategic, not proof of universally lower cost or latency.
For network-as-a-service buyers compare Equinix Fabric, PacketFabric and PCCW Console Connect. For AI compute customers compare CoreWeave, Nebius, Lambda, Crusoe, OVHcloud, Vultr and Hetzner. These groups are not interchangeable product rivals. Synergy Research says specialist neocloud revenue topped US$25B in 2025; the entire market is not directly addressable by Megaport.
-
Equinix Fabric direct
On-demand interconnection and extensive data-center footprint.
-
PacketFabric direct
Private software-defined connectivity.
-
Console Connect direct
Private programmable multicloud connectivity.
-
CoreWeave adjacent
GPU-focused cloud, different size and software stack.
-
Nebius adjacent
AI GPU infrastructure and cloud platform.
Industries
Market / IPO context
Ticker: MP1 (ASX)
IPO status: public
Note: ASX-listed public company. Do not confuse market capitalization with A$2.3B contract value, A$1.1B pro forma ARR or acquisition consideration.
Editorial / static context — not a live quote.
FAQs about Megaport
Practical answers founders, operators, and investors typically search for.
Last updated:
Editorial note: AI tools assisted with research, structure, or drafting. Venture Capital Tracker retains human editorial responsibility for factual accuracy, relevance, and source quality before publication.