· Investment Strategies · 1 source
Sapien’s $180M Valuation Round: Neo Leads the AI Layer That Traces Ops to P&L
Neo’s Ali Partovi led a new Sapien financing at a $180M valuation — amount undisclosed — as the GC-seeded FP&A startup expands into operational profit analytics for Bayer, Cooper Standard, and peers.
Editorial team
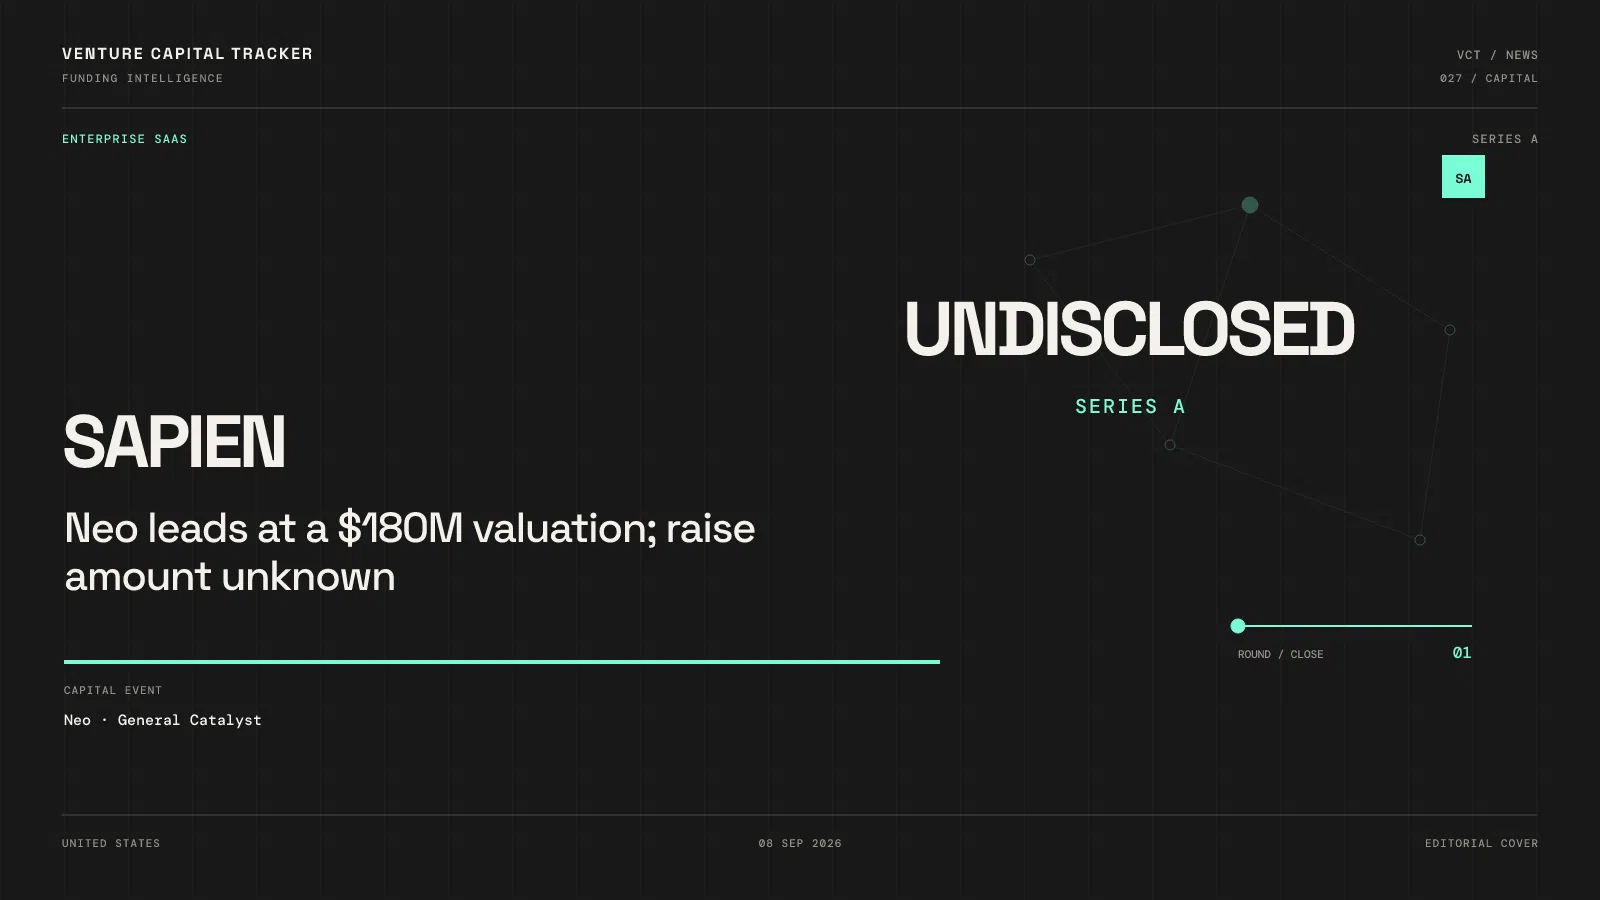
Neo (Ali Partovi) led a new financing for Sapien at a $180 million valuation on September 8, 2026, with General Catalyst participating after leading the company’s $8.7 million seed in 2024 (Fortune). Raise amount was not disclosed.
Spine: In a week of billion-dollar AI and space cheques, this is the quieter enterprise bet — AI that tells operators which decision moved profit, not another dashboard that reports what already happened.
Key facts
- Company
- Sapien (sapien.ai — not Sapien.io crypto data foundry)
- Founders
- Ron Nachum, Pranav Ravella, Arya Grayeli (2024)
- Round
- New financing at $180M valuation; $ amount unknown
- Lead
- Neo (Ali Partovi)
- Prior
- $8.7M seed led by General Catalyst (2024)
- Named customers
- Bayer, Carlex, Cooper Standard, Blink Charging, Westgate Resorts
Who uses the product — and why
Users: CFOs and operators at industrial and consumer companies that need to connect shop-floor / channel decisions to P&L drivers — beyond classic FP&A planning.
Job: move from “forecast the budget” to “explain what actually drove margin and cash.” Fortune frames an expansion from financial planning software into broader operational analytics.
Why those logos matter: Bayer and Cooper Standard are not novelty AI buyers; renewal at accounts like these is the real diligence metric when revenue is undisclosed.
Why Neo — portfolio fit
| Dimension | Fit |
|---|---|
| Neo | Concentrated early bets on technical founders building enterprise AI systems of record |
| General Catalyst | Seed lead recycling into the follow-on — continuity signal when amount is hidden |
| Founder rationale | Need growth capital to expand from FP&A into ops-to-P&L without raising a splashy round that forces premature ARR theater |
Roughly 20× markup from an $8.7M seed to a $180M mark in under two years is aggressive for enterprise AI — but common in 2026. Without disclosed ARR, treat the mark as investor opinion, not a multiple you can underwrite.
What remains undisclosed
- Round size (primary vs secondary)
- Formal series letter (A vs seed extension)
- Revenue, NRR, or seat counts
- How much of “profit driver” analysis is model vs rules + human services
Takeaway
$180M valuation without a published cheque size is a signal about who is writing (Neo + GC) more than how much fuel arrived. The next public proof is whether Bayer-class accounts renew after the novelty quarter.
Day index: September 8–9 investment news.
Follow Venture Capital Tracker on Google
Add VCT as a preferred source to see more of our venture-capital reporting in Google Search.
Editorial note: AI tools assisted with research, structure, or drafting. Venture Capital Tracker retains human editorial responsibility for factual accuracy, relevance, and source quality before publication.