· Investment Strategies · 2 sources · Updated
Omilia’s $67M Series B: Voice-First Agentic CX Without Token Bill Shock
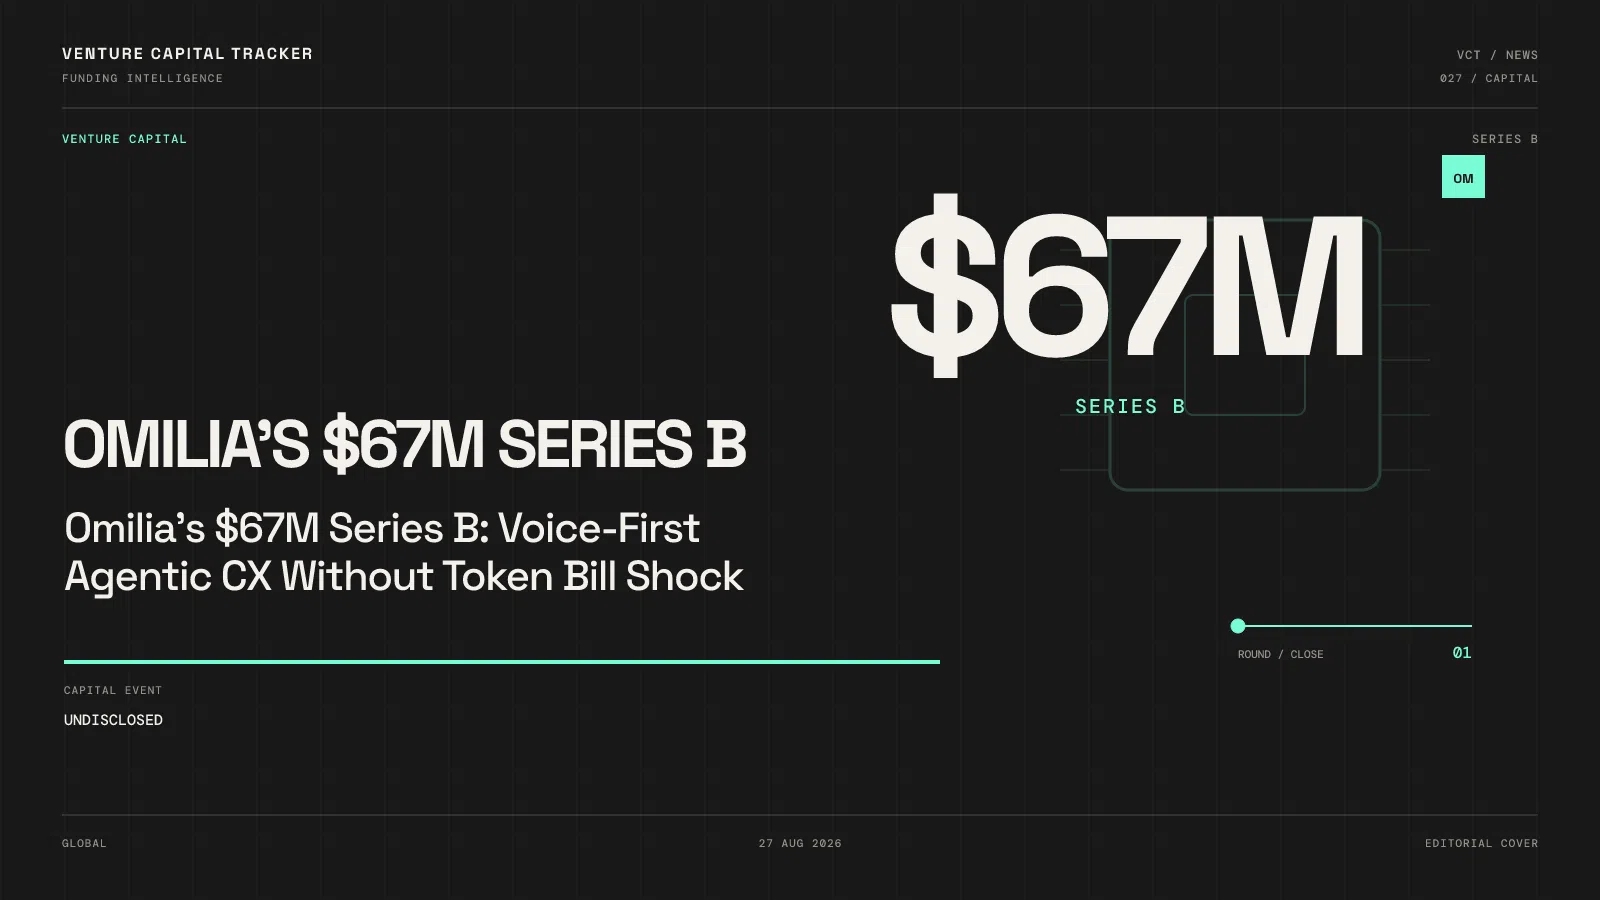
Expedition Growth Capital led Omilia’s $67M Series B as the self-learning agentic CX platform hit $60M+ ARR — Capital One, Discover, RBC, and 1,000+ Taco Bell drive-thrus in the customer set.

Editorial team
Funding event
Omilia
Led by Expedition Growth Capital
Omilia raised a $67 million Series B led by Expedition Growth Capital on August 6, 2026. The Athens/New York voice-first agentic CX company says live ARR topped $60M — >10× since Series A — with capital efficiency rare in the GenAI CX arms race.
Key facts
- Company
- Omilia — Self-Learning Agentic CX
- Round
- $67M Series B
- Date
- August 6, 2026
- Lead
- Expedition Growth Capital (London / Boston)
- Prior
- ~$20M Series A (Grafton Capital, 2020)
- ARR
- >$60M live (company)
- Scale claims
- Tier-1 U.S. bank >1M calls/day; insurer agent-assist >600k calls/day
- Recognition
- Forrester Wave Leader (Conversational AI for Customer Service, Q2 2026)
Who uses the product — and for what job
Users: contact-center and CX leaders at banks, insurers, utilities, government, and QSR.
Job: contain and resolve high-volume voice (and omnichannel) interactions with sub-second latency, auditability, and predictable cost — not a pilot chatbot that explodes the LLM bill.
Named logos include Capital One, Discover, RBC, DWP, PSEG, and Taco Bell (1,000+ drive-thrus / 38 states per company).
Omilia’s wedge vs “LLM for every utterance”: use the right tool for the job — deterministic flows for balance checks, generative agents where judgment is needed — on owned models so token pass-through does not own the P&L.
Why now
- Enterprises graduated from GenAI demos to production call volume.
- Token-priced CX stacks create CFO pushback at million-call scale.
- Regulated buyers want FedRAMP / PCI / HIPAA / GDPR paths, not lab sandboxes.
- QSR voice ordering and bank containment are measurable ROI stories, not vanity NPS.
Why Expedition — portfolio fit (growth equity lens)
Expedition markets itself as a transatlantic software & AI growth specialist ($1B+ AUM) that partners with founder-owned, capital-efficient leaders. Omilia’s six-year gap from Series A to a $67M B with $60M+ ARR is the textbook “use capital to accelerate, not survive” profile.
Likely founder rationale: pick growth equity that understands enterprise GTM and founder control, not a mega-fund that would force a burn race against Sierra/Decagon branding.
| Dimension | Omilia signal |
|---|---|
| Efficiency | 10× ARR without interim equity |
| ICP | Regulated + high concurrency voice |
| Moat claim | Owned voice stack + glass-box auditability |
| Use of proceeds | U.S. office + Five9-veteran GTM bench |
Competitive map
| Player | Lane |
|---|---|
| Sierra, Decagon, Parloa | Generative / agentic CX peers |
| Five9 / Genesys ecosystem | Incumbent CCaaS platforms |
| ElevenLabs / Smallest.ai | Voice model layers (infra vs full CX) |
| HappyRobot | Ops agents (logistics) — adjacent automation |
CEO Dimitris Vassos’s framing (via TechCrunch): you may have a bazooka, but contact centers still need a knife.
Market signal
~$60M ARR → $67M raise implies growth equity pricing discipline, not 2021 AI multiple theater. The category winners may be the vendors that own unit economics at 1M+ calls/day.
When not to treat Omilia as the only template
- Wrong for greenfield consumer chatbots with no concurrency or compliance burden.
- Wrong if your only proof is a LinkedIn demo — Omilia’s buyers care about FedRAMP and call containment.
- Wrong to ignore QSR edge cases; voice ordering still needs human escalation design.
Practical takeaway
- Founders (CX AI): Sell predictable cost + audit trails; owned models can be a CFO feature.
- Investors: Prefer capital-efficient voice platforms with named regulated logos over narrative-only agent demos.
- Operators: Benchmark containment and cost-per-resolved-contact at your peak concurrency, not vendor showcase traffic.
Follow Venture Capital Tracker on Google
Add VCT as a preferred source to see more of our venture-capital reporting in Google Search.
Last updated:
Editorial note: AI tools assisted with research, structure, or drafting. Venture Capital Tracker retains human editorial responsibility for factual accuracy, relevance, and source quality before publication.