· Investment Strategies · 2 sources
Mach Industries’ $600M Series C Extension: $3.7B Defense Manufacturing Mark
Mach printed another $600M on Sep 10, 2026 — doubling to $3.7B three months after a $300M Series C at $1.8B — as Ribbit, Sequoia, Bedrock, and Infinite fund airframes, counter-UAS, and Mach Energetics.

By Venture Capital Tracker Editorial
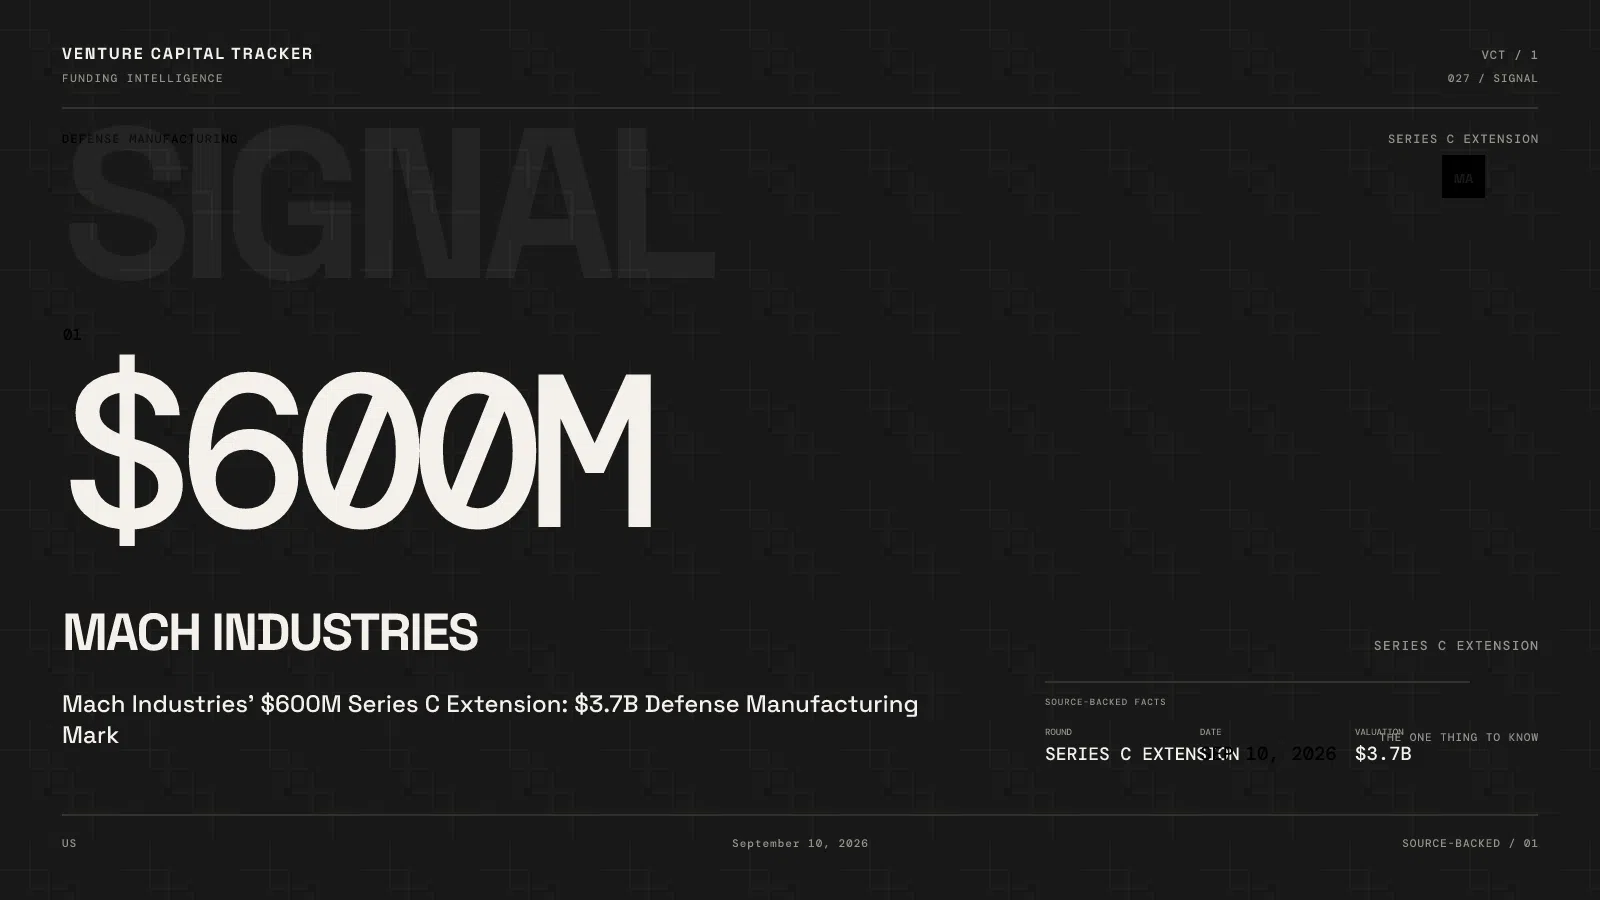
Mach Industries announced a $600 million continuation of its Series C on September 10, 2026, marking the company at $3.7 billion — 2× the June 2026 Series C print of $300 million at $1.8 billion. Ribbit Capital, Infinite Capital, Bedrock Capital, and Sequoia are named on both tranches (company PR / TechCrunch).
In three months the mark doubled again. The story is not another software “defense AI” deck — it is factory + energetics capacity for unmanned weapons as SRMs and engines become bottlenecks.
For the wider investment context of defense manufacturing scale-up, consult VCT’s 2026 defense-tech funding overview. It distinguishes startup financings from institutional VC fund closes and government contracts.
Key facts
- Company
- Mach Industries (Huntington Beach, CA)
- Round
- $600M Series C extension at $3.7B
- Prior tranche
- June 2026: $300M at $1.8B
- Earlier
- June 2025 Series B: $100M at ~$470M (Khosla lead)
- Factory
- Forge Huntington — 115,000 sq ft
- Founder
- Ethan Thornton, 22, MIT dropout
- Energetics
- Acquired Exquadrum ($50M cash/equity, May) → Mach Energetics
Bedrock Capital and Infinite Capital have
Who uses the product — and for what job
Users / buyers: U.S. military and allied procurement offices that need unmanned strike, counter-UAS, and related effects at costs below classic prime timelines. TechCrunch notes an Army contract earlier in 2026.
Job: design-to-produce unmanned systems with in-house propulsion and solid rocket motors so Mach is not waiting on the two-incumbent SRM market. Mach Energetics also sells energetics outward — a supplier line, not only captive use.
Why now
- June’s $1.8B Series C was already a 4× jump from the 2025 Series B mark; September’s extension says manufacturing milestones (airframes, propulsion, Energetics) cleared a second diligence pass fast.
- Drone warfare created SRM scarcity; buying Exquadrum was Mach’s answer.
- Sequoia’s Stephanie Zhan / Shaun Maguire path made Mach Sequoia’s first defense-tech bet — continuity capital follows that thesis.
Why these investors — portfolio fit
| Investor | Likely fit |
|---|---|
| Ribbit | Once fintech-coded; now overlapping AI/hard-tech (Cognition, Crusoe adjacency in press) with Mach as a manufacturing print |
| Sequoia | Defense manufacturing conviction after being first-in among classic SV firms |
| Bedrock / Infinite | Early Mach capital recycling through scale-up |
Founder age is a feature for narrative and a risk for primes used to decades of program history — the cheque says VCs are underwriting throughput, not pedigree.
Competitive map
| Approach | Tradeoff |
|---|---|
| Traditional primes | Certifications + scale; slow / expensive |
| Anduril-class software-defined defense | Lattice + autonomy; different manufacturing depth |
| Mach vertical factory + energetics | Own SRMs/engines; must prove sustained DoD production |
What remains undisclosed
Contract values, backlog, margins, and how much of the $900M Series C stack (300+600) is already spent vs reserved for Forge expansion. $3.7B is a manufacturing capacity mark until revenue prints.
Follow Venture Capital Tracker on Google
Add VCT as a preferred source to see more of our venture-capital reporting in Google Search.
Editorial note: AI tools assisted with research, structure, or drafting. Venture Capital Tracker retains human editorial responsibility for factual accuracy, relevance, and source quality before publication.