· Venture Capital · 33 sources · Updated · Verified
Top Defense Tech Companies 2026: Funding, Leaders and Fundamentals
An independently sourced market guide to the leading defence-tech companies, major 2026 investment rounds, real revenue and production evidence, and the risks behind private valuations.

Editorial team
Defence technology has moved from a specialist venture category into one of the largest markets for private capital. By October 5, European defence-tech startups had attracted $7.4 billion in 2026 financing, compared with $2.6 billion in all of 2025, according to Dealroom and Resilience Media. In the US, Anduril closed a $5 billion Series H at a $61 billion valuation. Europe had its own blockbuster: Helsing raised $1.8 billion at $18 billion.
Deal details & investors
Funding event
TEKEVER
Led by UC Investments , Baillie Gifford
Reported valuation $6.4B
The larger question is what the money buys. A flight-tested drone is not necessarily an accepted production system; a multibillion-dollar contract ceiling is not revenue. There are companies with real, disclosed sales and deployed products, others with promising prototypes, and plenty of private valuations that reveal little about margins or cash burn.
The leading companies are not all in the same business. Some sell mission software, others manufacture missiles or ships, and some provide satellite intelligence or critical components. The durable advantage is likely to come from products that customers repeatedly order, factories that deliver and enough capital to finance the gap between the two.
The largest disclosed defence-tech rounds of 2026
The figures below are selected announced transactions, dated as of November 5, 2026. The table distinguishes primary investment from debt, secondary trades and financing still subject to closing.
| Company | Announced | Equity raised or disclosed financing | Valuation at announcement | Business |
|---|---|---|---|---|
| Anduril | May 13 | $5B Series H | $61B | Integrated defence software, sensors and autonomous systems |
| Helsing | July 13 | $1.8B Series E | $18B | European autonomy and defence AI |
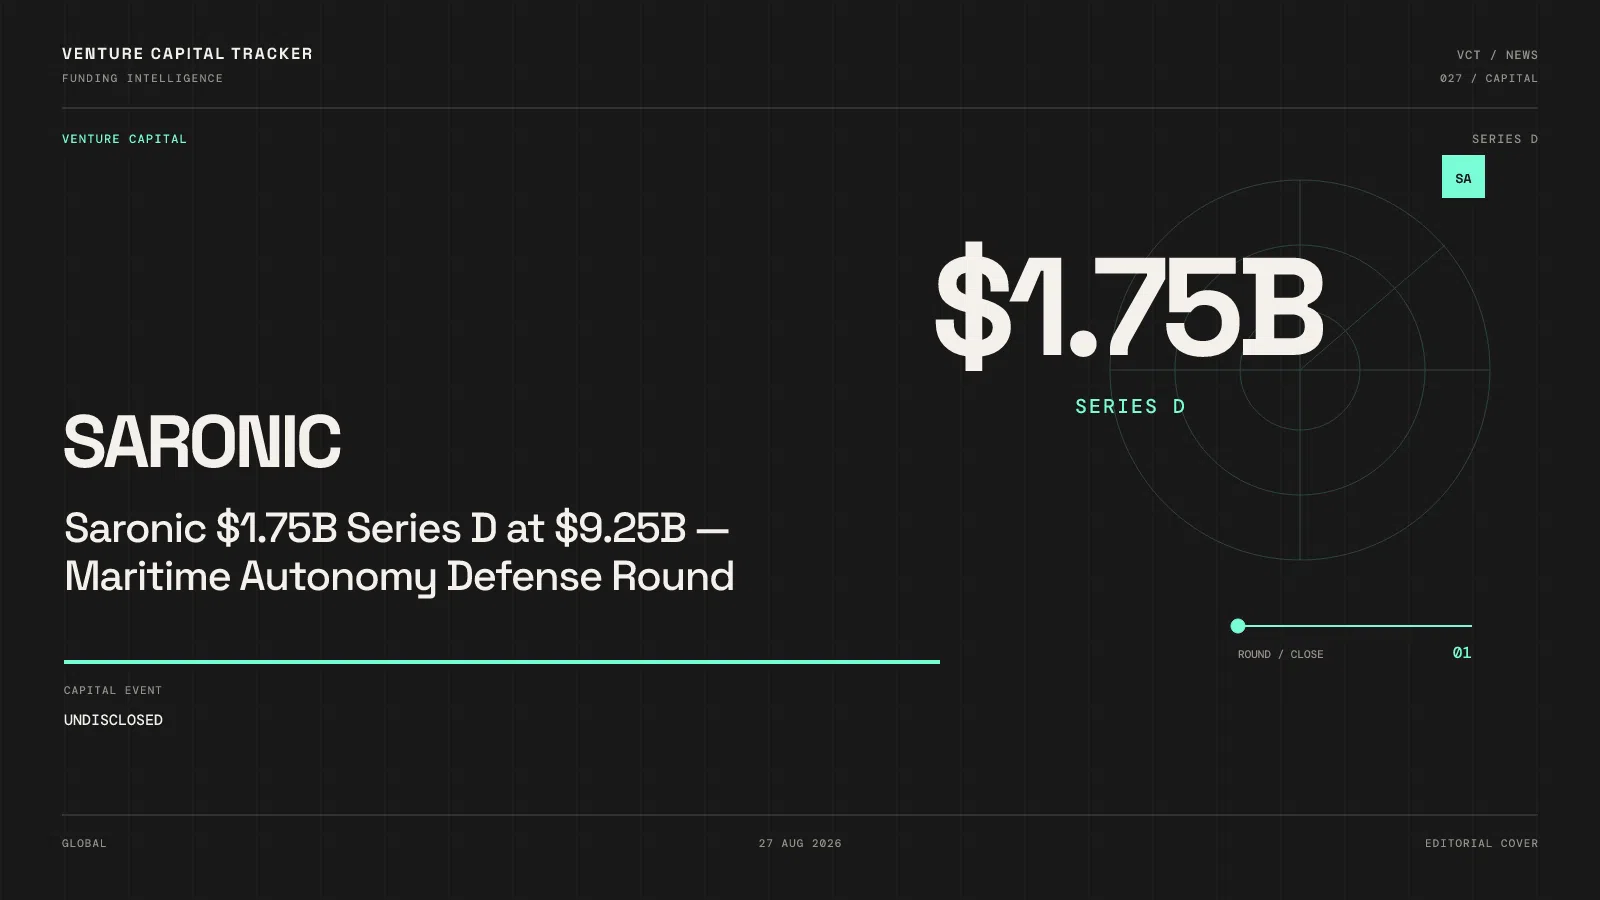
| Saronic | March 31 | $1.75B Series D | $9.25B | Autonomous vessels and shipbuilding |
| Shield AI | March 26 | $1.5B Series G plus $500M preferred financing | $12.7B | Autonomous aviation and Hivemind software |
| Quantum Systems | July 2 | $1.2B Series D signed | ~$8B | Multi-domain drones and autonomy |
| Castelion | August 19 | $800M equity plus $250M committed revolver | $13B | Hypersonic strike systems |
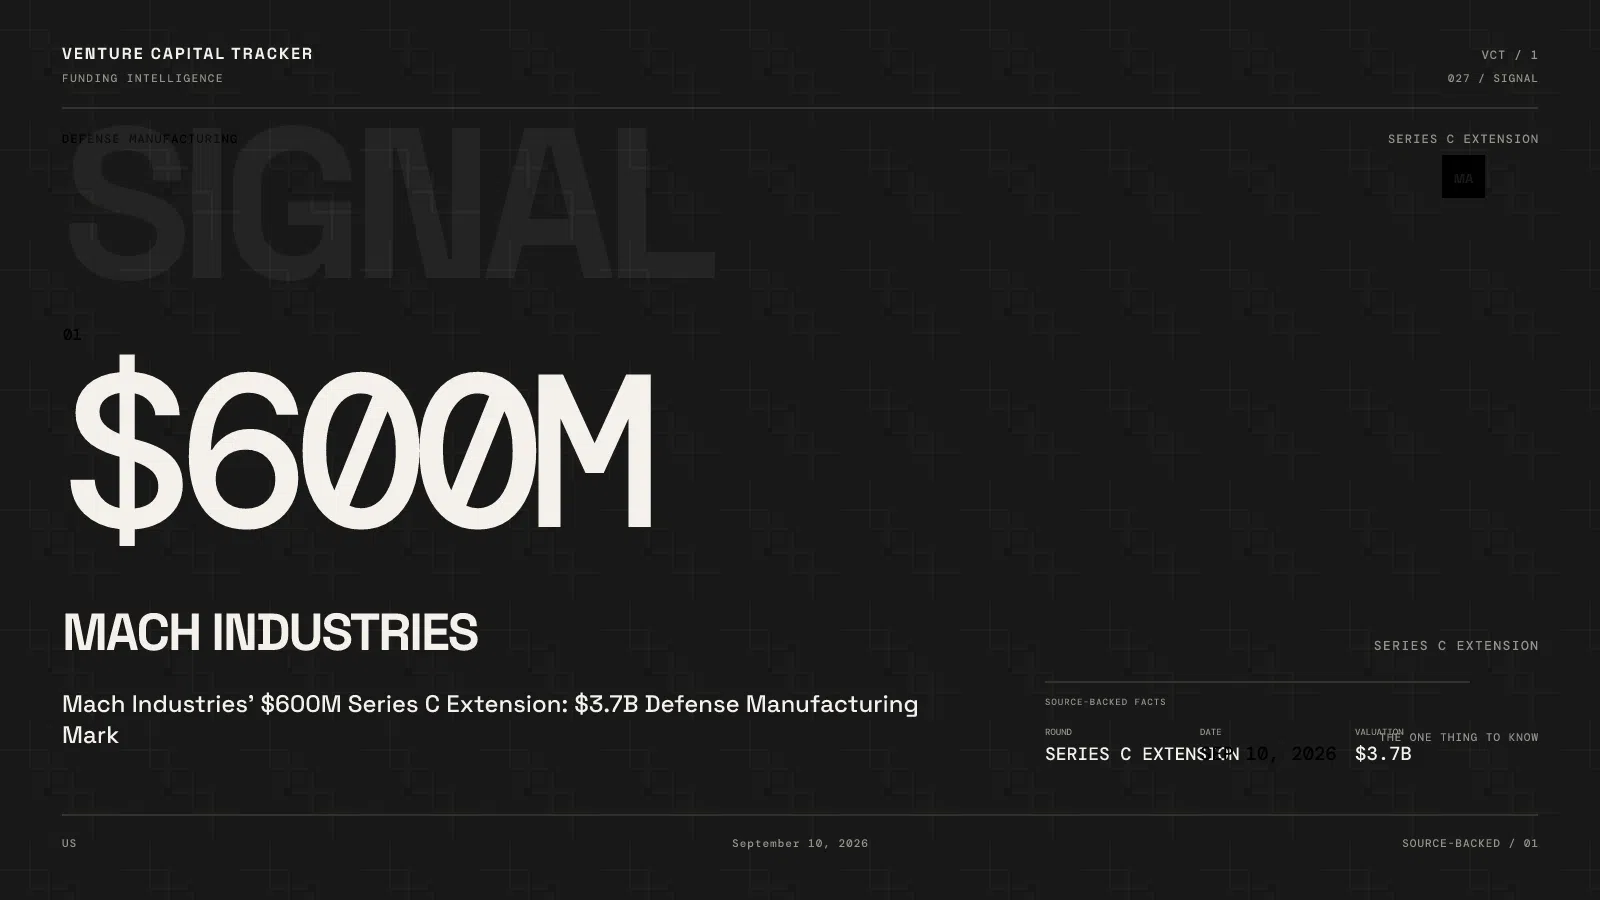
| Mach Industries | September 10 | $600M Series C continuation following $300M in June | $3.7B | Long-range strike, drones and propulsion |
| TEKEVER | September 23 | $580M Series D first close | $6.4B | Surveillance drones and intelligence services |
| STARK | June 25 | €500M financing, per investor disclosure | Not publicly confirmed in cited announcement | Munitions, unmanned systems and production |
| ICEYE | June 9 | €450M primary Series F, with a separate secondary placement | Over €10B | Radar satellites and sovereign intelligence |
| Neros Technologies | August 11 | $250M Series C | $2.5B | Small drones and interceptors |
| Hermeus | April 7 | $200M equity plus $150M debt | $1B | High-speed uncrewed aircraft |
| Harmattan AI | January 12 | $200M Series B, led by Dassault Aviation | Not confirmed by the cited company announcement | Military autonomy and AI systems |
Dollar and euro amounts remain in the disclosed currencies; this is not a sum of interchangeable equity investments. Several companies serve broader aerospace or dual-use markets.
Four financing details materially change the numbers:
- Shield AI: Its March announcement separates $1.5 billion of Series G capital from $500 million of fixed-return preferred equity. An additional $250 million delayed-draw commitment was not part of the $2 billion headline.
- Castelion: Its release calls the transaction a $1 billion Series C, but specifies $800 million equity and a $250 million revolving credit commitment—components totalling $1.05 billion. The announced headline is rounded, and committed credit is not equivalent to cash equity raised.
- ICEYE: €450 million is new primary financing. A secondary share sale increased the combined transaction above €1 billion, but secondary proceeds generally go to selling shareholders, not the company. The deal was subject to closing conditions when announced.
- TEKEVER and Quantum Systems: The former disclosed a first close; the latter announced that financing had been signed. Neither description should silently become a claim that every eventual tranche had closed.
Mach Industries's additional $600 million should likewise be read alongside, not mistaken for, its separate $300 million June financing. The table excludes the sizeable debt and procurement packages sometimes presented in defence-investment rankings.
Who leads the market—and why?
Anduril: the broadest vertically integrated challenger
Founded in 2017, Anduril has moved beyond individual defence products toward an integrated portfolio of Lattice software, sensors, autonomous aircraft, counter-drone systems and manufacturing capacity. Its May 2026 round was led by Thrive Capital and Andreessen Horowitz.
Its financial disclosure is unusually substantial for a private peer: CEO Brian Schimpf said revenue more than doubled to $2.2 billion in 2025. That figure was reported by management, rather than presented here as independently audited. Anduril's challenge is now industrial as much as technological: converting development programmes into regularly delivered, serviced systems across different customers.
A $20 billion US Army enterprise contract ceiling awarded in March 2026 illustrates the distinction. The amount is the maximum potential value over the contract's scope—not $20 billion of realised sales or guaranteed orders.
Helsing: Europe’s military AI company becomes a hardware supplier
Munich-based Helsing began with software that interprets sensor data and supports military decision-making. It has since expanded into autonomous physical systems, making it a different industrial proposition from a pure software contractor.
Its $1.8 billion Series E, announced July 13, valued the company at $18 billion. The company's release listed investors including Dragoneer, Goldman Sachs Alternatives, Lightspeed, Iconiq and JPMorganChase, without identifying a single lead investor. The investment thesis rests on European demand for sovereign systems and integration with national defence programmes. Comprehensive, independently verified revenue and margin information remains limited.
Shield AI and Auterion: two ways to sell autonomy
Shield AI develops the Hivemind autonomous pilot and V-BAT aircraft. Its 2026 financing also supports its planned acquisition of simulation specialist Aechelon. Hardware, flight autonomy and simulation offer multiple potential customer relationships, but make integration and programme delivery complex.
Auterion is a different bet: an operating-system and autonomy layer designed to operate across less expensive drone hardware. Bessemer led its $130 million Series B in September 2025—not a 2026 financing.
The commercial question: Can common autonomy software spread across fleets without requiring custom engineering for every aircraft, sensor and military customer? If not, the apparent software-margin advantage can narrow quickly.
Quantum Systems, TEKEVER and ICEYE: three intelligence businesses
These companies all deliver military intelligence, but their economics differ.
Quantum Systems builds uncrewed platforms and the MOSAIC autonomy ecosystem. Its July release disclosed a signed $1.2 billion Series D, approximately $8 billion valuation, and more than 19,000 missions in Ukraine during 2025. The company also described itself as profitable, with double-digit profitability; audited margin figures were not supplied in that disclosure. Missions provide more operating evidence than a prototype photograph, but do not establish revenue per mission or fleet reliability.
TEKEVER, founded in Portugal in 2001 and now headquartered in the UK, combines aircraft, sensors, intelligence analysis and operational services. Its September $580 million first close followed selection for the British Army's CORVUS surveillance programme, worth up to £400 million over ten years. That programme ceiling is not a revenue statement. The distinction is important: a supplier selling supported surveillance services may have different recurring economics from a one-time drone manufacturer.
ICEYE sells synthetic-aperture radar imagery and complete sovereign satellite systems. Its June financing statement reported over €250 million of 2025 revenue, over €100 million EBITDA and a contracted backlog exceeding €1.5 billion, all based on unaudited 2025 results. The company said seven European governments had procured sovereign systems, and described satellite production of 50 per year, with a goal of 100 annually by 2028. Backlog is future contracted work, not recognised revenue; the production target is not current output.
Of the three, ICEYE offers the clearest publicly stated revenue and profitability data. Quantum Systems offers unusually concrete operational activity. TEKEVER has a named large government programme. Those are distinct forms of evidence—not directly comparable measures of commercial strength.
Saronic, STARK and ARX Robotics: industrial production is the test
Saronic, a US developer of autonomous surface vessels, closed $1.75 billion in March at $9.25 billion, led by Kleiner Perkins. The funding supports vessel development and shipyard expansion. Its earlier $392 million Navy production contract provides customer evidence, although the awarded value should not be treated as proof that the full programme has been delivered and paid.
Germany's STARK raised €500 million in June, according to investor NATO Innovation Fund, to expand manufacturing and research for uncrewed systems. The investor said production would scale towards thousands of systems a month. That is a planned capability, not a verified count of accepted deliveries. ARX Robotics is a ground-robotics specialist; its €31 million 2025 Series A and €11 million extension belong to separate transactions and should not both be described as 2026 funding.
The economics depend on manufacturing yield, component suppliers, field maintenance and production acceptance—not merely factory floor space.
Castelion, Mach and Neros: the cost of making weapons at volume
Castelion is developing mass-producible hypersonic weapons. Its August release described more than $500 million in US military contracts and targeted initial Blackbeard fielding in 2027. The company has disclosed flight testing and substantial manufacturing investment, but production targets and contracted awards still require separate delivery and cash-conversion evidence.
Mach Industries operates across strike systems, counter-drone capability and propulsion, building a distributed manufacturing network called Forge. Its two 2026 Series C financing tranches fund production capacity and supply-chain control. Both the breadth of the product portfolio and the capital expenditure required are central to its outlook.
Neros Technologies raised $250 million in August at a $2.5 billion valuation. On November 2, 2026, the company separately announced a $450 million conditional government loan commitment for manufacturing, alongside $165 million of its own equity allocated to the project. The resulting $615 million project size is not a new $615 million venture round. Its goal of producing a million drones annually by 2028 is a target, not current verified output.
The enabling companies
Not every attractive defence supplier builds a weapon. Hadrian focuses on automated precision manufacturing, CHAOS Industries and CX2 on sensing and electronic warfare, and K2 Space, Apex Space and Northwood Space on spacecraft and supporting infrastructure. Forterra and Overland AI target autonomous ground operations. Skydio, Perennial Autonomy and Ulysses serve overlapping but not identical drone and maritime markets.
These businesses should be judged on the economics of their own layer of the supply chain, not benchmarked blindly against missile producers or integrated prime contractors.
A map of the defence-tech value chain
| Segment | Important companies | What buyers purchase | Strongest operating evidence |
|---|---|---|---|
| Integrated platforms and military AI | Anduril, Helsing, Shield AI | Mission software, sensing and autonomous systems | Product acceptance, programme expansion and repeat support |
| Uncrewed aircraft and counter-drone | Quantum Systems, TEKEVER, Neros, Skydio | Aircraft, interceptors, controls and intelligence services | Operational hours, delivered units and replenishment economics |
| Maritime and ground autonomy | Saronic, STARK, ARX Robotics, Forterra | Vessels, ground vehicles and autonomy | Fleet deliveries, availability and maintenance costs |
| Strike systems and propulsion | Castelion, Mach Industries, Firehawk Defense | Missiles, propulsion and industrial capacity | Qualification, accepted output, cost per unit |
| Space intelligence and infrastructure | ICEYE, K2 Space, HEO, Apex Space | Satellite imagery, communications and hardware | Launch record, contracted service revenue and coverage |
| Production and electronic systems | Hadrian, CHAOS Industries, CX2, Nominal | Components, test systems, sensing and factory services | Factory yields, lead times and customer diversification |
The category boundary is intentionally wider than weapons manufacturing. Space, sensing, logistics and industrial suppliers can benefit from defence demand without being direct competitors to autonomous aircraft companies.
Defence spending is not venture capital
The acceleration in European investment is real within Dealroom's classification: $7.4 billion in 2026 through the report date, 11.1% of European venture funding, and a $10.5 billion projected full-year total. The projection must not be reported as funding already invested. Definitions also differ across datasets, especially around space, cyber, dual-use technology and manufacturing.
The demand side is bigger than venture capital but operates differently.
In June 2025, NATO allies committed to an annual 5% of GDP defence and security-related spending framework by 2035, comprising at least 3.5% for core defence and up to 1.5% for resilience and related needs. This is a future national spending commitment, not venture funding and not an amount already disbursed. The European Commission's SAFE programme provides up to €150 billion in loans to Member States for common defence procurement. Again, these are not equity checks to startups.
That distinction explains why funding can surge while young suppliers still struggle to win orders. Budgets must reach a programme that can procure the product; the supplier must pass qualification and export/security reviews; and manufacturing must meet delivery requirements.
The fundamentals that separate companies from valuations
Two companies can raise similar amounts and have radically different businesses. The following public examples show what can and cannot be concluded.
| Company | Harder evidence available | What remains unknown from those disclosures |
|---|---|---|
| Anduril | Management-reported $2.2B 2025 revenue and a closed $5B 2026 round | Company-wide audited margin, cash flow and profitability by programme |
| ICEYE | Unaudited €250M+ 2025 revenue, €100M+ EBITDA, €1.5B+ contracted backlog | Audited conversion of backlog into sales and product-level margins |
| Quantum Systems | Company-reported 19,000+ 2025 Ukraine missions and profitability claim | Independently audited financials and economic returns per system |
| TEKEVER | Selected for a British Army programme of up to £400M | Amount obligated, recognised revenue and delivery economics |
| Saronic | $392M Navy production contract, per company and deal coverage | Full ordering, completed vessel deliveries and unit margins |
| Neros | $250M equity round plus a later $450M conditional loan commitment | Loan drawdown, achieved factory throughput and cost per fielded unit |
Three accounting distinctions are essential. An IDIQ or programme ceiling is the maximum potentially ordered, not automatically the amount spent. A financing commitment may be undrawn; loans must be repaid. A company's stated production capacity may be planned rather than achieved. None should be added to booked revenue.
For a supplier facing long approval cycles, the most consequential measures are customer-funded orders, accepted deliveries, gross margin after integration and maintenance, inventory financing, and cash received. An announced factory can increase future production—and consume capital for years before that production is accepted.
Where the next competitive advantage lies
United States: Anduril, Shield AI, Saronic and Castelion benefit from access to a large national acquisition market. That advantage comes with long procurement procedures, programme politics, cybersecurity obligations and export rules. The biggest contract number may be a ceiling rather than an obligated order.
Europe: Helsing, Quantum Systems, ICEYE, TEKEVER and STARK are building more local capabilities as governments pursue technology sovereignty. But Europe remains a collection of procurement authorities, budgets and export regimes, not one buyer. Operational partnerships and production capacity in allied markets matter more than a general claim to benefit from NATO spending.
Israel: Defence-tech companies operate in a mature sensor, cyber and aerospace ecosystem, with firms such as Protego Ventures financing early-growth businesses. Demonstrated field use can help adoption, but it cannot replace internationally compliant supply chains and recurring customers.
Ukraine: Battlefield needs shorten some product-feedback cycles, creating opportunities in drones, electronic warfare and autonomy. Brave1 public grants, private venture investments and government procurement serve different purposes; export rights, IP ownership and supply-chain risks remain material.
The investment opportunity is therefore not a single 'defence software' trade. It is a set of businesses with widely varying industrial requirements and revenue quality. The likely dividing line is not which company raised most recently, but which can consistently turn technical advantage into affordable, supported and paid-for capability.
The investors financing the build-out
Capital comes from firms with different constraints. Independent specialists such as NATO Innovation Fund and Decisive Point, industrial growth investors such as DTCP Defence Fund I, generalists such as a16z, Founders Fund, Lux Capital and Bessemer, and strategic investors such as Lockheed Martin Ventures can all fund different parts of the system.
NATO Innovation Fund publishes €3M–€15M initial direct checks and €1B AUM. DTCP announced a €455M first close, towards a €500M target. The figures are not comparable investment tickets. In Ukraine, D3 publishes $500K–$1.5M initial checks.
The companion Defense Tech VC Funds 2026 guide compares 14 identifiable investors, actual disclosed check-size evidence, fund mandates and relevant financing examples.
For company-specific valuations, see Defense Unicorns 2026. Related sector reporting covers a16z American Dynamism, US government-tech investors, and nuclear and defence energy startups.
Reporting cut-off: November 5, 2026. Figures are selected, not an exhaustive global market census. Company-reported operational metrics are attributed; private company financials are not assumed audited unless specifically stated. Primary equity, preferred financing, debt, secondary transactions, grants and procurement contracts remain separate categories.
Last updated:
Editorial note: AI tools assisted with research, structure, or drafting. Venture Capital Tracker retains human editorial responsibility for factual accuracy, relevance, and source quality before publication.