· Investment Strategies · 2 sources
Light’s $46M Series A: Matrix Leads Embedded Electricity for Solar, Proptech & EV Partners
Matrix led Light’s $46M Series A with Activate joining and Spark Capital plus BoxGroup returning — total equity ~$60M and capital base >$100M including credit as Light joins PJM.

Editorial team
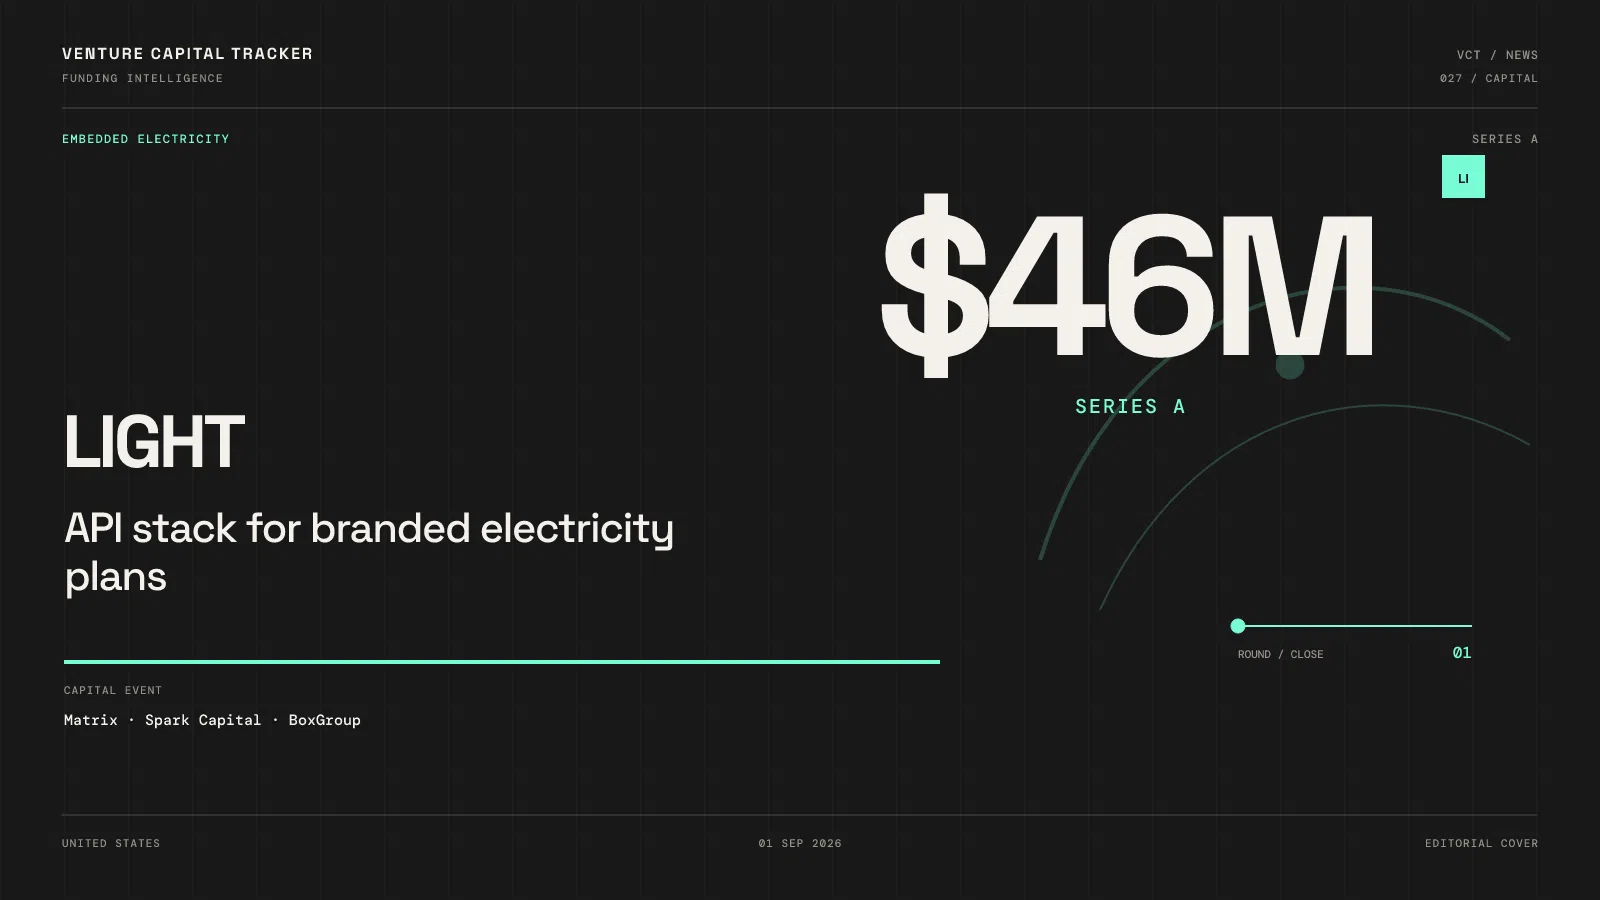
Matrix led Light’s $46 million Series A (September 1, 2026), with Activate Capital joining and existing investors Spark Capital, Mischief, Gigascale Capital, MCJ, and BoxGroup returning. Total equity funding reaches ~$60M; including a credit facility, Light says its capital base exceeds $100M (company PR).
Spine: apply the embedded-finance playbook to electricity — partners keep the customer relationship while Light is the regulated provider behind an API.
Key facts
- Company
- Light (Austin; poweredbylight.com)
- Founder
- Baker Shogry (ex–Head of Product, Plaid) with co-founder Adam
- Round
- $46M Series A
- Lead
- Matrix (Matt Brown)
- Returning (directory)
- Spark Capital, BoxGroup
- Expansion
- PJM membership → NJ, PA, IL beyond Texas
- Company claims
- 10x run-rate revenue in 12 months; 100% of new TX electricity brands in H1’26 launched on Light (up from >70% in 2025)
Who uses the product — and for what job
Users / partners: solar and battery companies, proptech/multifamily operators, EV/mobility brands, and fintechs that want to sell or bundle electricity without becoming a utility from scratch.
Named partners: Palmetto, GoodLeap, Emporia, Public Grid, Lunar Energy, Moved.
Job: launch a branded electricity plan (company claims as little as two weeks) while Light handles licensing, wholesale power, commodity risk, billing, support, and VPP ops.
Why now
- AI load, residential price inflation, and DER/battery adoption make owning the electricity relationship a commercial lever — not a side referral.
- State-by-state retail electricity is an operations moat: hard to fake with a thin API alone.
- PJM entry tests whether the Texas playbook travels into the largest U.S. wholesale market.
Why this syndicate — portfolio fit
Matrix’s public quote compares Light to Plaid-style category infrastructure. Spark and BoxGroup returning signals continuity from earlier checks into a Series A that funds multi-ISO expansion and product (battery bundles, EV subscription charging).
| Dimension | Fit |
|---|---|
| Stage | Series A scale of regulated ops + GTM |
| Thesis | Embedded energy = next infrastructure layer after payments |
| Risk | Wholesale volatility, state regulation, grid constraints |
Matrix, Activate, Mischief, Gigascale, and MCJ are covered without inventing /fund/ pages.
What remains undisclosed
- Valuation
- Gross margin / risk book performance
- Credit facility size and covenants
- Partner concentration (how much volume sits in top solar partners)
Competitive map
Standalone retail electricity providers and utility-branded plans still dominate. Light’s wedge is partner-branded electricity inside solar, housing, and EV sales motions — adjacent to grid-software stories like Gridsight, which sell utilities capacity visibility rather than retail plans.
Takeaway
The diligence question is operational: can Light underwrite commodity and regulatory risk across ISOs while partners only see an API? Product demos are easy; balance-sheet and compliance execution are the product.
Sources
Follow Venture Capital Tracker in Google
Add VCT as a preferred source to make our venture-capital coverage easier to find in Google Search.
Editorial note: AI tools assisted with research, structure, or drafting. Venture Capital Tracker retains human editorial responsibility for factual accuracy, relevance, and source quality before publication.