· Investment Strategies · 3 sources
Easy Aerial’s $20M Series B: Tethered Drones for Persistent ISR
NYC’s Easy Aerial closed $20M with Insight Partners and Entrée Capital — scaling tethered UAS that stay aloft on ground power for defense and critical infrastructure.

Editorial team
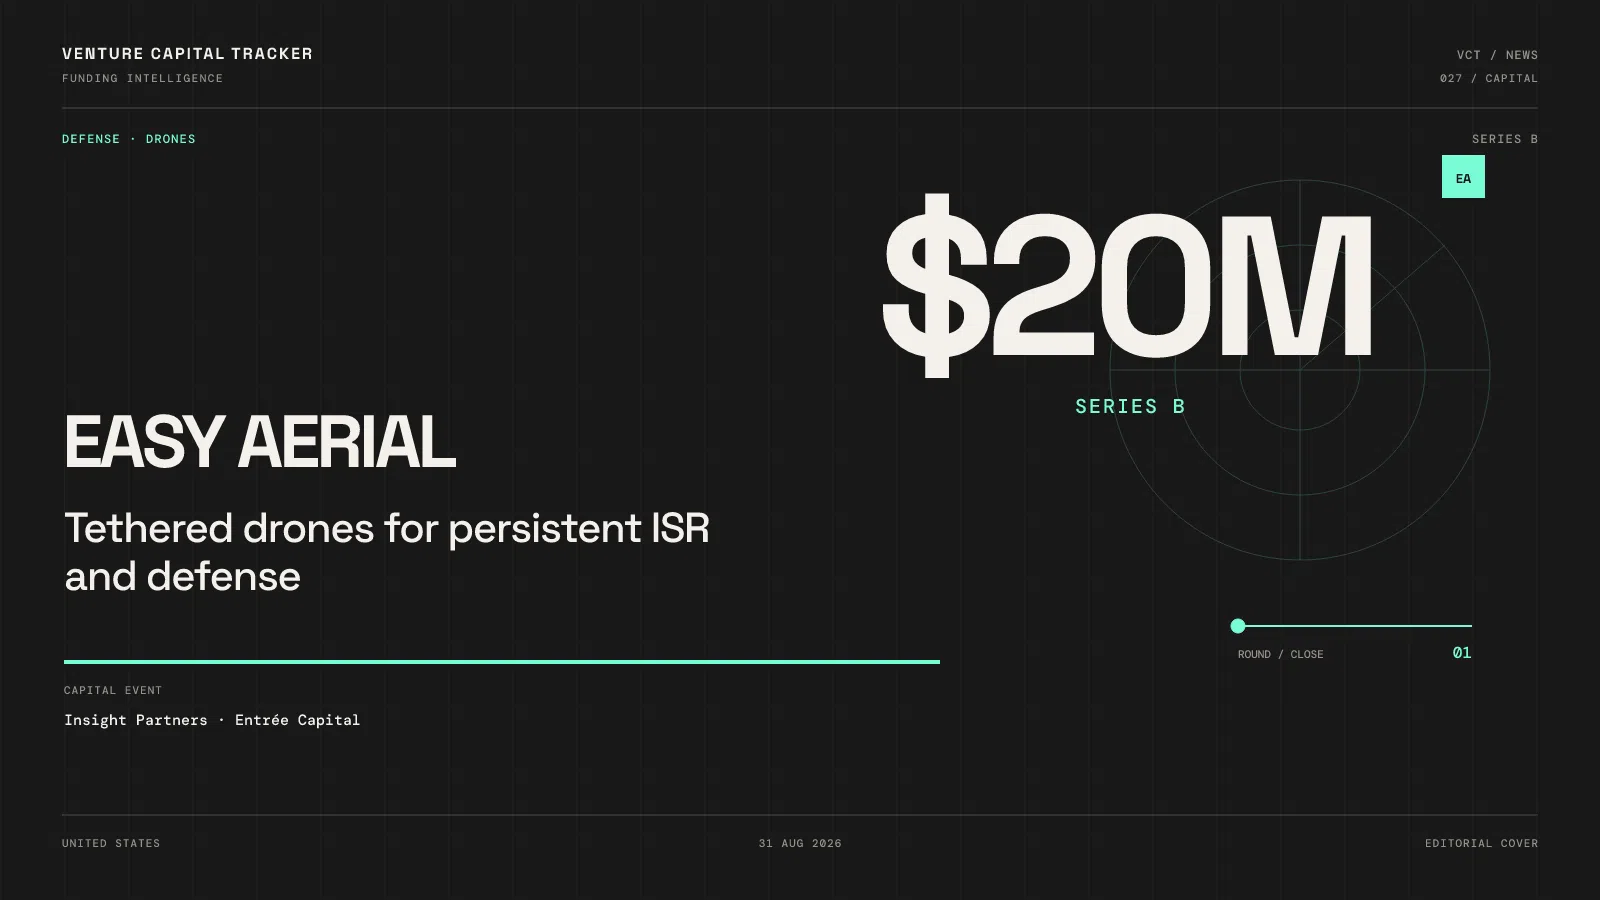
Easy Aerial completed a $20 million Series B on August 31, 2026, with Insight Partners, Entrée Capital, and private U.S. investors (Business Wire). Valuation was not disclosed. The release did not name a single lead.
Spine: free-flying drones still lose to physics on long-duration stare; tethered systems trade mobility for hours-to-days of persistent ISR on ground power — exactly what bases, borders, and critical sites buy.
Key facts
- Company
- Easy Aerial
- Round
- $20M Series B
- Investors
- Insight Partners, Entrée Capital, private U.S. investors
- HQ
- New York
- Use of proceeds
- Production capacity, international defense programs, autonomous aerial R&D
- Footprint
- Manufacturing expanding into Europe (company)
Who uses the product — and for what job
Users: defense and government customers needing persistent aerial intelligence, plus commercial operators protecting perimeters and critical infrastructure.
Job: put an autonomous sensor package in the air and keep it there — EO/IR and related payloads for force protection, ISR, emergency response — without rotating battery-swapped free-flyers every 20–40 minutes.
DroneDJ’s Sep 3 recap framed the raise against rising ISR spend. Separate federal sole-source activity for tethered UAS at DOI-managed sites has been reported in procurement databases; treat contract specifics as outside this memo’s primary sources unless verified on SAM.gov for diligence.
Why now
- Contested and peacetime ISR budgets both favor persistence over spectacle.
- Allied and U.S. programs need non-Chinese hardware stacks that clear Blue UAS / NDAA-style constraints.
- Series B capital is manufacturing and program delivery money, not a science project.
Why Insight Partners — portfolio fit
Insight Partners is best known for software ScaleUp — but the firm’s software/defense-adjacent book and growth playbooks fit a company leaving custom integrations for repeatable production and international programs. Entrée Capital adds early-tech DNA. For founders, Insight is a signal that the buyer motion is shifting from prototype demos to multi-year deployment contracts.
Entrée Capital has no /fund/ page here.
Competitive map
| Approach | Tradeoff |
|---|---|
| Manned towers / aerostats | Persistent; expensive and slow to redeploy |
| Free-flying multicopters | Flexible; endurance-limited |
| Satellite / HAPS | Wide area; latency and weather tradeoffs |
| Easy Aerial tethered UAS | Persistent local stare; tether constrains mobility |
What is not proven
- Valuation, backlog dollars, and margin.
- Named program wins in the Series B release (qualitative “multiple new contracts” only).
- Exact split of defense vs commercial revenue.
Practical takeaway
- Founders (defense hardware): Raise when you can point to programs and factories, not airframe photos.
- Investors: Diligence tether logistics, Blue UAS compliance, and spare-parts economics — that is the moat, not the demo reel.
- Operators: Relevant if you need continuous overwatch on a fixed or slow-moving asset.
Follow Venture Capital Tracker on Google
Add VCT as a preferred source to see more of our venture-capital reporting in Google Search.
Editorial note: AI tools assisted with research, structure, or drafting. Venture Capital Tracker retains human editorial responsibility for factual accuracy, relevance, and source quality before publication.