· Venture Capital Tracker · venture-capital
Li Auto’s MHX Signs RMB1.625B Equity Deal; RMB625M Is External
MHX Technology signed RMB1.625B in equity subscriptions: RMB1B from Li Auto and RMB625M externally. Closing is conditional; a further RMB500M is optional.
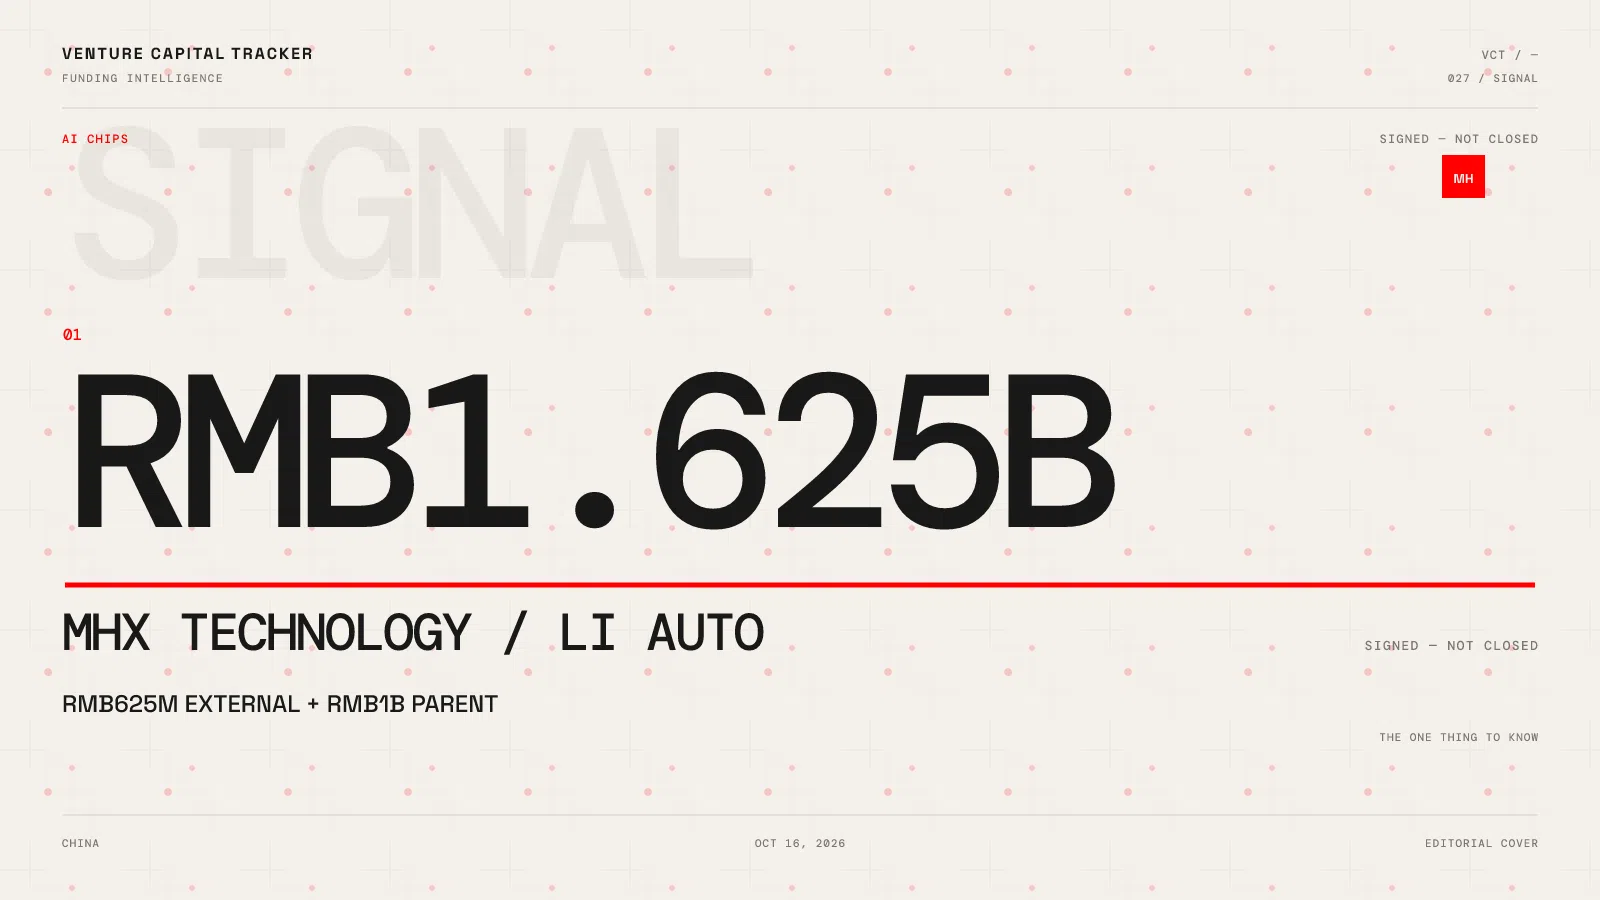
Li Auto’s chip subsidiary, MHX Technology, has signed RMB1.625 billion of equity subscription agreements, opening its semiconductor business to outside investors while leaving the automaker in control.
The October 16 announcement divides the financing into two very different sources: a RMB1 billion parent contribution routed through a fully owned entity, alongside RMB625 million subscribed by outside backers. Those external backers include Hangzhou Jingtao, Lanchi Ventures, Huaye Tiancheng and MiraclePlus.
This is a signed transaction, not a completed funding round. Li Auto’s release makes closing conditional. It does not assign a Series A label in the release.
How much outside capital is actually involved?
The externally subscribed portion represents about 38.5% of the RMB1.625 billion agreement; the parent supplies the remaining 61.5%. These are shares of the capital contribution, not ownership percentages.
That distinction changes the investment story. The headline amount measures capitalization of the subsidiary, whereas RMB625 million measures the outside investors’ initial financial commitment. Treating all RMB1.625 billion as independently raised venture capital would overstate the external validation.
It also matters at group level. Moving money from a parent-controlled entity into a subsidiary does not create the same group-wide inflow as a third-party investment. Because Li Auto will continue consolidating MHX, readers should distinguish subsidiary proceeds from new outside cash entering the broader group.
The additional RMB500 million is an option, not money raised
A Hangzhou Jingtao-associated investor can make a further subscription of up to RMB500 million using the initial deal’s price for each unit of registered capital added. The right can be exercised once, on or before December 31, 2026.
If exercised in full, that would bring the initial subscriptions plus optional capital to RMB2.125 billion. It is a scenario, not today’s committed financing amount.
CnEVPost’s reporting puts the maximum post-money valuation at RMB17.1 billion if the entire right is taken up. That figure should retain its conditions; it is not an unconditional valuation attached to a closed RMB1.625 billion round.
Why Li Auto is opening the chip business
MHX, formally Shanghai Mahe Xin Technology Co., Ltd., houses the parent’s chip and domain-controller activities. Li Auto says the dedicated platform can pursue industrial opportunities outside the car market and use the capital for research, development and commercialization.
The strategic thesis is straightforward: an in-house chip team may gain a larger addressable market if it can supply other customers. More production volume could spread design and software-development costs across a wider revenue base.
But a captive deployment environment and an independent semiconductor business are different propositions. External customers need support, portable software, dependable supply and a roadmap that is not subordinate to one automaker’s product cycle. The financing creates room to pursue that transition; it does not demonstrate that third-party sales have already scaled.
Control is preserved, with important assumptions
The parent plans to preserve control, keeping MHX within its consolidated accounts. The release outlines a scenario in which the parent holds approximately 74.01%, external investors 6.58% and incentive-plan entities 19.41%.
That ownership scenario incorporates the complete allocation of both employee incentive programs and the full optional investment. They should not be presented as the current cap table or inferred from the initial cash split.
The incentive pool is part of the commercial logic: chip businesses require scarce engineering talent, and a subsidiary-level equity structure may help recruit and retain it. The corresponding ownership dilution is part of the cost.
What the next milestones should prove
The first milestone is an announced close. The next is whether the optional subscription is exercised by the year-end deadline.
Beyond financing, the stronger evidence would be named outside customers, qualified products and disclosed commercial revenue. Those milestones would show whether MHX is becoming a broader edge-AI supplier rather than remaining primarily an internal technology platform.
Bottom line
MHX’s agreement is a substantial corporate-backed semiconductor financing, but its structure is more informative than the headline alone. It comprises RMB625 million of initial outside subscriptions, RMB1 billion of parent capital and a separate optional RMB500 million. Closing, option exercise and external commercialization remain distinct future tests.
For related context, see VCT’s MHX Technology profile, Lanchi Ventures profile and coverage of Mueon’s $65 million Series A.
Last updated:
Editorial note: AI tools assisted with research, structure, or drafting. Venture Capital Tracker retains human editorial responsibility for factual accuracy, relevance, and source quality before publication.