· Updated · Venture Capital Tracker Editorial · investment-strategies
Southeast Asia VC May–June 2026: Singapore's Gravity and the AI Hub Bet
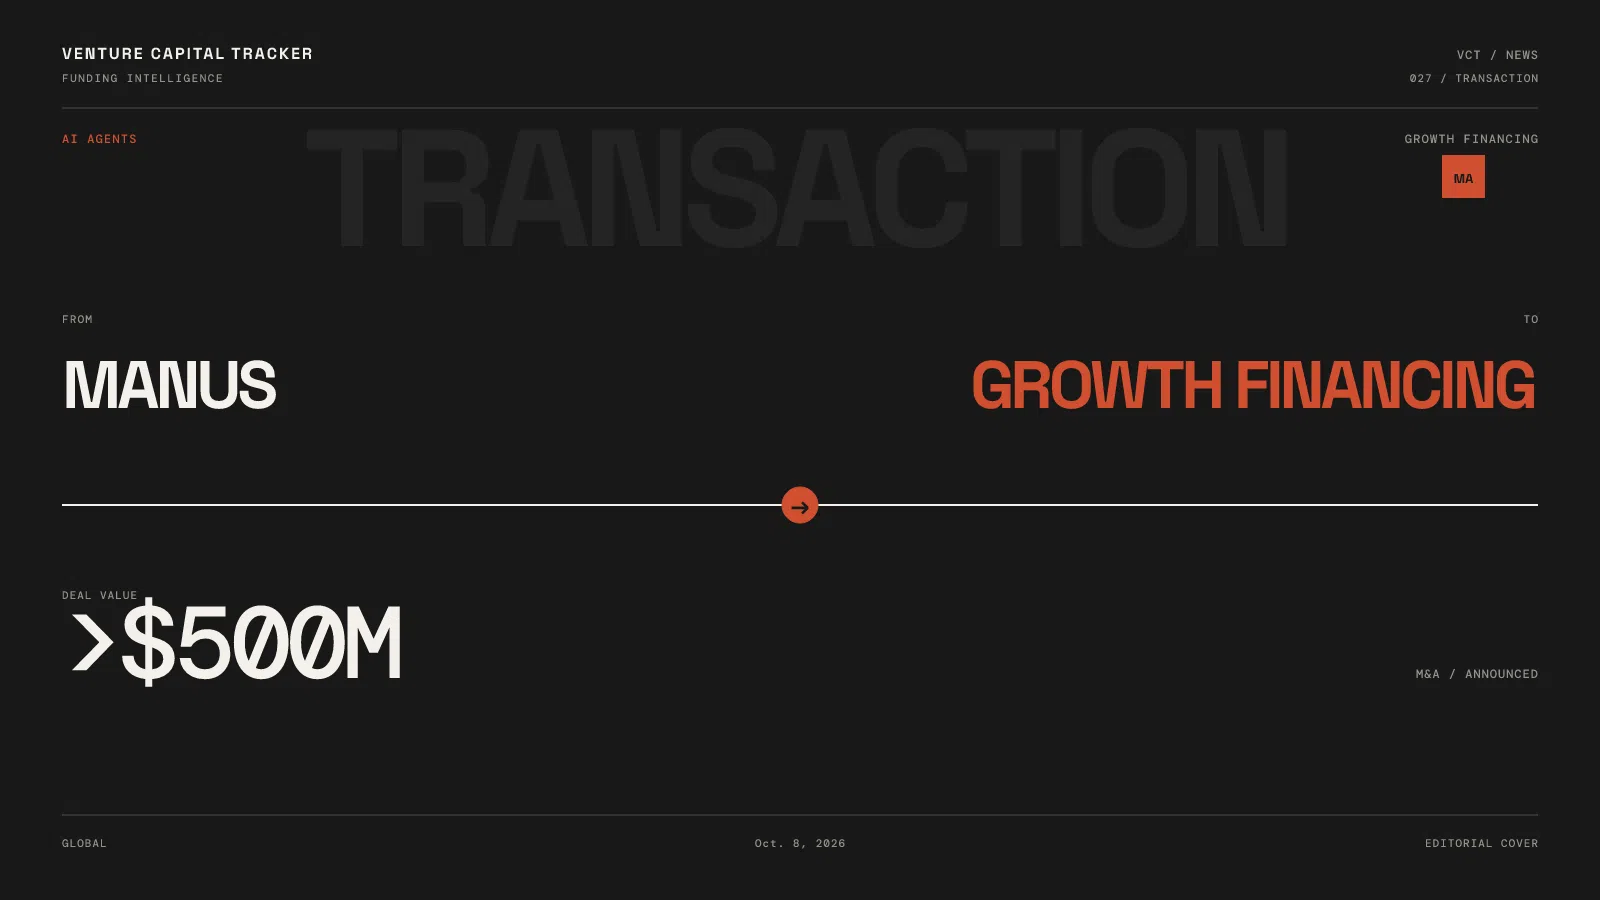
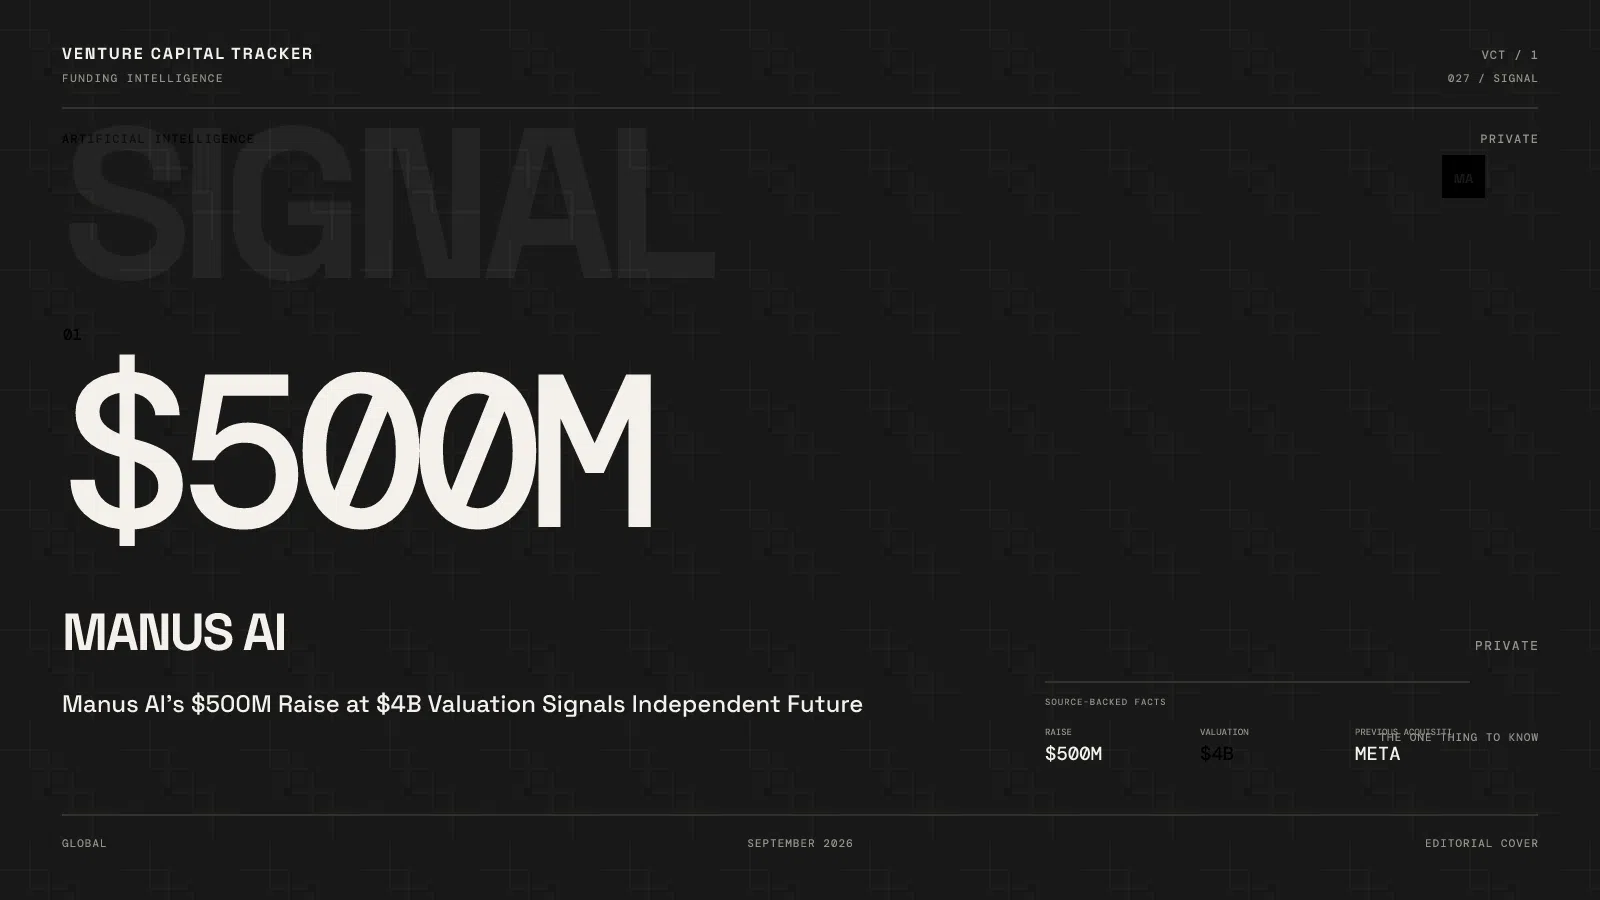
Singapore captured the lion's share of Southeast Asian capital in mid-2026, anchored by DayOne's $4.5B data-center round, Aippy's AI gaming raise, and OpenAI's new lab. Manus’s live September print is $500 million at $4 billion in talks — not the June $1 billion buyback ask.
Southeast Asia's venture map in May and June 2026 had one clear center of gravity: Singapore. The city-state captured the overwhelming majority of regional capital and cemented its status as the region's AI hub.
Singapore's marquee deals
| Company | Amount / Event | Sector |
|---|---|---|
| DayOne | $4.5B Series C | Data centers |
| Aippy (NADA AI) | tens of millions ($250M val) | AI-native gaming |
| Manus AI | June: weighing $1B buyback. Sep 2026: $500M at $4B talks | Agentic AI |
| OpenAI | $235M applied-AI lab | AI research |
Why Singapore is winning
- Infrastructure scale. DayOne's $4.5B — the region's defining deal — funds data-center expansion across Singapore, Malaysia, and Indonesia, backed by Coatue, Hillhouse, and the Indonesia Investment Authority.
- AI talent magnet. OpenAI's $235M applied-AI lab and Manus AI's relocation (now legally Singaporean) show the city-state pulling agentic-AI gravity from across Asia.
- Capital concentration. With Singapore taking 90%+ of Q1 regional capital, the rest of Southeast Asia competes for a smaller, more disciplined pool focused on later-stage, profitable companies.
The Manus wrinkle: geopolitics meets venture
Manus AI — founded in China, staff relocated to Singapore in mid-2025 — was weighing a $1B raise to unwind Meta's $2B acquisition after Beijing blocked the deal. The live September 2026 print is $500 million at $4 billion in talks, not that June $1 billion figure. It still underscores Singapore's hub appeal and the regulatory complexity facing China-origin startups.
Practical takeaway (operator + investor)
For founders in the region, Singapore is the launchpad but the bar is high: investors want disciplined, later-stage businesses or genuine AI infrastructure plays. Capital is concentrated, so a credible path to profitability or strategic moat is the price of entry.
Sources
- The Business Times (DayOne $4.5B): https://www.businesstimes.com.sg/companies-markets/data-centre-operator-dayone-raises-us4-5-billion-series-c-funding
- PRNewswire (Aippy $250M valuation): https://www.prnewswire.com/apac/news-releases/aippy-raises-tens-of-millions-of-dollars-at-a-250-million-valuation-to-build-the-future-of-ai-native-interactive-entertainment-302787864.html
- Dealroom (Manus AI $1B buyback): https://app.dealroom.co/news/note/manus-eyes-1b-raise-to-unwind-meta-s-2b-acquisition-after-beijing-blocks-deal
Last updated:
Editorial note: AI tools assisted with research, structure, or drafting. Venture Capital Tracker retains human editorial responsibility for factual accuracy, relevance, and source quality before publication.