Snowpoint Ventures Closes $411M Fund II for 10 Dual-Use Companies
Snowpoint Ventures closed a $411 million second fund for a concentrated portfolio of ten dual-use companies, while using a government-backed loan to expand its investment capacity.
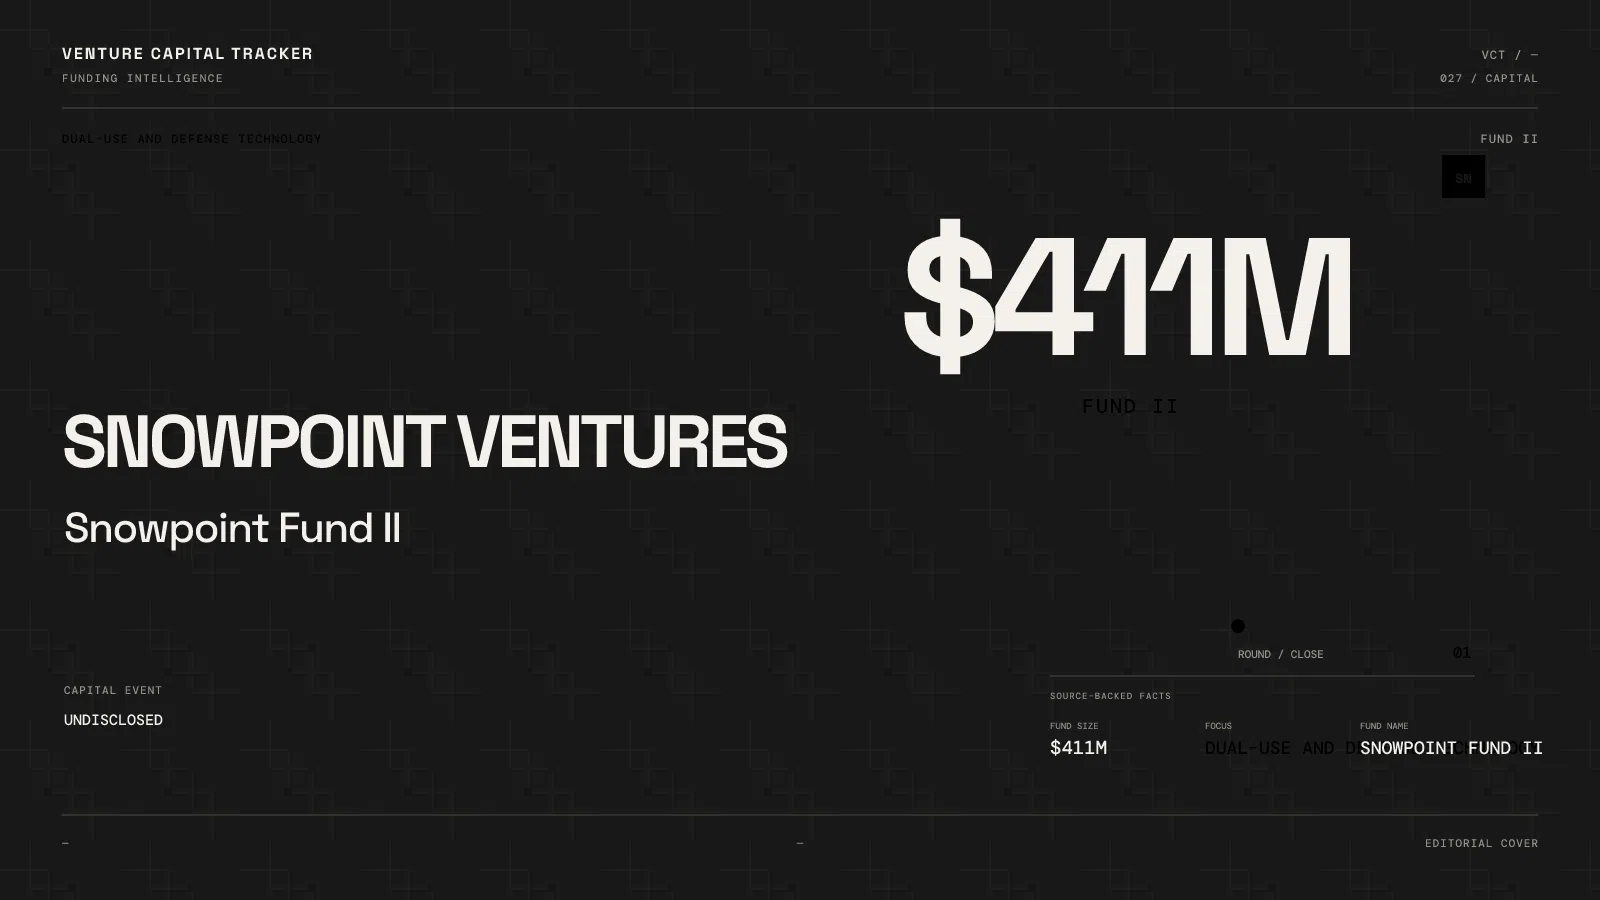
Snowpoint Ventures has closed a $411 million second fund for a highly concentrated portfolio of approximately ten dual-use technology companies.
The Palm Beach firm completed the close in July 2026, according to reporting published by The Wall Street Journal on October 2. Snowpoint did not separately announce the final close on its public website. The distinction matters for timing: this is newly disclosed fund news, not an October close.
Fund snapshot
| Item | Detail |
|---|---|
| Vehicle | Snowpoint Ventures Fund II |
| Final close | $411 million |
| Close timing | July 2026, reported in October |
| Planned portfolio | Approximately 10 companies |
| Strategy | Dual-use technology serving commercial and government markets |
| Firm assets | Approximately $1.5 billion, reported |
| Government-backed loan | $125 million |
| LP examples | Sovereign wealth funds and university endowments |
Snowpoint also obtained a $125 million loan through a Department of Defense and Small Business Administration initiative supporting technologies important to national security. That borrowing is not limited-partner capital and should not be added to the $411 million fund close as if it were another equity commitment.
A deliberately concentrated defense-tech strategy
Co-founders Doug Philippone and Alex Creasey built Snowpoint around technologies that can serve both national-security and commercial customers. Philippone previously helped build Palantir’s defense business after a military career. Creasey is a former naval cryptologist.
The firm’s disclosed portfolio includes companies such as Astranis, Shield AI, Valar Atomics and Rivet. These businesses span space communications, autonomous systems, advanced energy and defense-oriented software.
Fund II’s planned ten-company portfolio is unusually concentrated. At a simple average, $411 million divided across ten positions would imply approximately $41 million per company before fees and reserves. Actual deployment will vary, but the arithmetic makes clear that Snowpoint intends to take meaningful positions rather than spread small checks across dozens of startups.
Why the structure matters
Defense technology is attracting large amounts of venture capital as governments modernize procurement, conflicts expose supply-chain weaknesses and commercial technologies become central to military systems. That demand has also raised concerns that valuations and capital supply are outrunning realistic procurement timelines.
Snowpoint’s answer is specialization and concentration. A small portfolio lets partners spend more time on government sales, security requirements, manufacturing and financing—areas where conventional software investors may have less operating experience.
The strategy also amplifies company-specific risk. One delayed procurement program, failed manufacturing scale-up or regulatory problem can have a visible effect on fund performance when the portfolio contains only ten companies.
The government-backed loan adds another layer. It expands the capital available for national-security investments without requiring Snowpoint to raise the same amount from limited partners. But debt is economically different from committed fund equity: it has repayment terms and may carry restrictions that the firm has not publicly detailed.
The analytical read
Snowpoint is making a strong claim about edge: that operating experience inside defense and intelligence markets is more valuable than broad diversification.
Four tests will determine whether that thesis works:
- Commercial dual use. Portfolio companies need real non-government markets rather than relabeling defense products as theoretically commercial.
- Procurement conversion. Pilot programs and research contracts must become scaled, repeatable government revenue.
- Manufacturing execution. Hardware companies need supply chains and production capacity that match contract ambition.
- Exit liquidity. Concentrated growth positions require credible paths to public markets, strategic acquisitions or secondary liquidity.
Snowpoint is also reportedly seeking a separate $1 billion growth-stage fund. If completed, that vehicle could give the firm more follow-on capacity for mature dual-use companies approaching public markets. It remains a fundraise in progress, not a confirmed close.
What to watch
The most useful next disclosures would be the final composition of Fund II, investment size and reserve policy, terms of the $125 million loan, and progress on the proposed growth fund. The concentration thesis should ultimately be judged by procurement conversion and company-level cash generation—not by the volume of capital flowing into defense technology.
Editorial note: AI tools assisted with research, structure, or drafting. Venture Capital Tracker retains human editorial responsibility for factual accuracy, relevance, and source quality before publication.