· Investment Strategies · 3 sources · Updated · Verified
Profound’s $180M Series D at $1.8B: AI Marketing for Answer Engines
Profound closed a $180 million Series D at $1.8 billion on September 15, 2026, co-led by Sequoia and Kleiner Perkins — less than seven months after a $96 million Series C. ARR not disclosed; 1,000+ enterprise brands claimed.

By Venture Capital Tracker Editorial
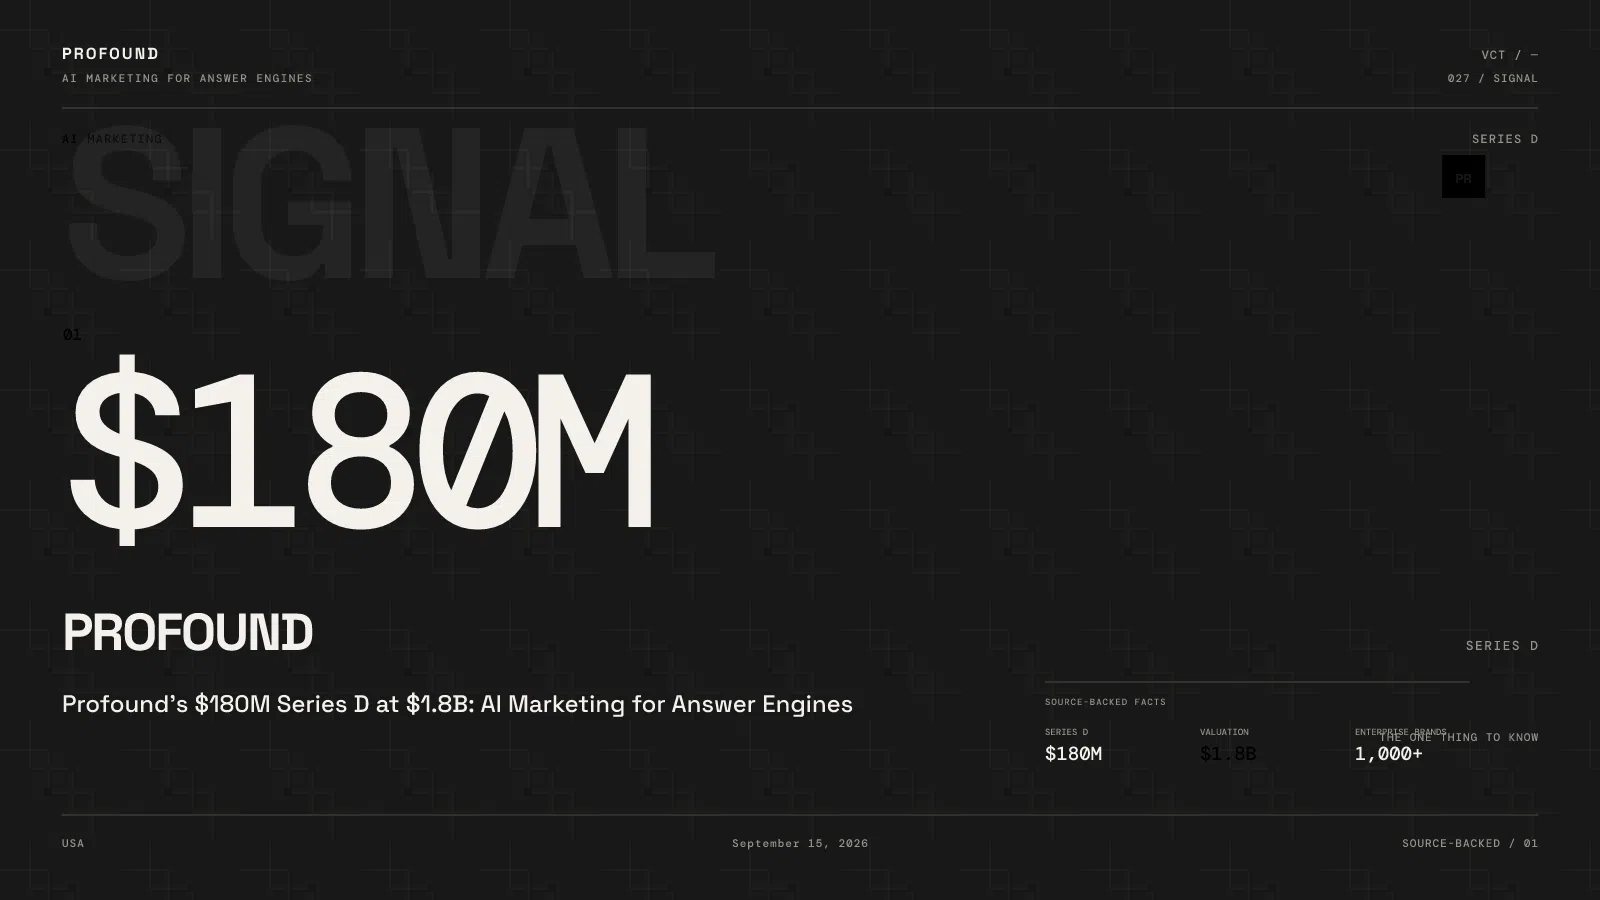
Profound closed a $180 million Series D at a $1.8 billion valuation on September 15, 2026, co-led by Sequoia Capital and Kleiner Perkins. Existing backers Lightspeed Venture Partners, Khosla Ventures, Saga Ventures, Evantic, and South Park Commons participated. The round arrives less than seven months after a $96 million Series C at $1 billion. ARR was not disclosed (company, Bloomberg).
Brands are learning that “SEO for ChatGPT” is not a feature — it is a new marketing surface — and Sequoia + KP just paid a $1.8B mark for the workbench expanding from AI-search analytics into agentic campaign ops.
Key facts
- Company
- Profound (tryprofound.com) — AI platform for marketing / answer engines
- Financing
- $180M Series D at $1.8B
- Date
- September 15, 2026
- Leads
- Sequoia + Kleiner Perkins (co-led)
- Prior
- $96M Series C at $1B (Feb 2026; Lightspeed led)
- Customers (company)
- 1,000+ enterprise brands; >1/3 of Fortune 100; 16% of Fortune 500 claimed
- Named logos
- Comcast, Estée Lauder, Walmart, Campari, RBC, Zoom, ServiceNow, Ramp, Cursor, MongoDB, Figma
- ARR
- Not disclosed
Who uses the product — and for what job
Users: marketing teams at large brands and growth-stage tech companies that need to win visibility when buyers ask ChatGPT, Gemini, Perplexity, and other answer engines — then turn that signal into content, ads, and reporting.
Job: (1) measure how models mention and describe the brand; (2) produce and refresh marketing work across organic and paid; (3) orchestrate agents (“AI Marketer”) with brand context. Company product names around the raise: AI Marketer, Context Manager, Ads Studio (OpenAI / Google / Meta ad managers; company pixel).
Fortune 100/500 share claims and named logos are company-disclosed distribution, not audited spend. Treat “2B+ real user prompts” as a data-asset claim until methodology is public.
Why now
- Buyer discovery is shifting from ten blue links to answer engines — marketing orgs need a continuous coverage surface, not a quarterly SEO project.
- Series C → Series D in under seven months at 1.8× the prior mark argues the bottleneck is platform breadth (agents + ads), not category education.
- Kleiner’s Ilya Fushman frames the bet as rebuilding marketing workflows for the “agentic web”; Sequoia’s Anas Biad cites enterprise adoption speed — both are judgment, not metrics.
Why Sequoia and Kleiner Perkins — portfolio fit
Co-lead structure matters: both firms were already on the cap table from earlier rounds and tripled down as Profound expands from AI-search analytics into a broader marketing OS.
- Sequoia fits category-defining consumer/enterprise platforms where distribution compounds (brand logos + data flywheel). Partner quote emphasizes applied AI lab talent in NYC and SF.
- Kleiner Perkins fits “workflow rebuild” theses when a new interface (answer engines) forces new software — analogous to prior marketing/cloud transitions, not a one-feature AEO plug-in.
- Khosla returning keeps a hard-tech / AI conviction lane on the same tape as Factory’s same-day raise.
Do not invent a /fund/lightspeed link (main Lightspeed is not our NYC directory page). Saga, Evantic, and South Park Commons stay editorial-only.
Competitive map
| Approach | Tradeoff |
|---|---|
| Classic SEO / AEO agencies | Human coverage; does not scale to answer-engine surfaces |
| Generic marketing copilots | Speed; weak brand-context + measurement loop |
| Ad platforms alone | Paid presence; thin organic AI-search insight |
| Profound workbench | Named enterprise logos + agent roadmap; no ARR printed |
What is not proven
- ARR, NRR, ACV, or contribution margin.
- Whether Fortune 100/500 percentages are seats, logos, or pipeline.
- Independent verification of the “2B+ prompts” corpus.
- Profitability — not disclosed.
Practical takeaway
- Founders (martech): Ship measurement → agent work → paid/organic loop; raise on logo density only if you can later print monetization.
- Investors: Diligence expansion from AI-search analytics into Ads Studio — category risk is “AEO feature” vs “marketing platform.”
- CMOs: Relevant if answer-engine visibility already shows up in brand tracking and you need one system for insight and execution.
Follow Venture Capital Tracker on Google
Add VCT as a preferred source to see more of our venture-capital reporting in Google Search.
Last updated:
Editorial note: AI tools assisted with research, structure, or drafting. Venture Capital Tracker retains human editorial responsibility for factual accuracy, relevance, and source quality before publication.