· Venture Capital Tracker Editorial · investment-strategies
Maven Robotics’ $100M Series A: Industrial Robots Built for Three Shifts
Maven Robotics exited stealth with $100M Series A on Sep 10, 2026 — RoboStrategy led; LocalGlobe joined — claiming Fortune 250 CPG fleets at 99%+ uptime and plans for 250 third-gen robots. Not Maven Clinic.
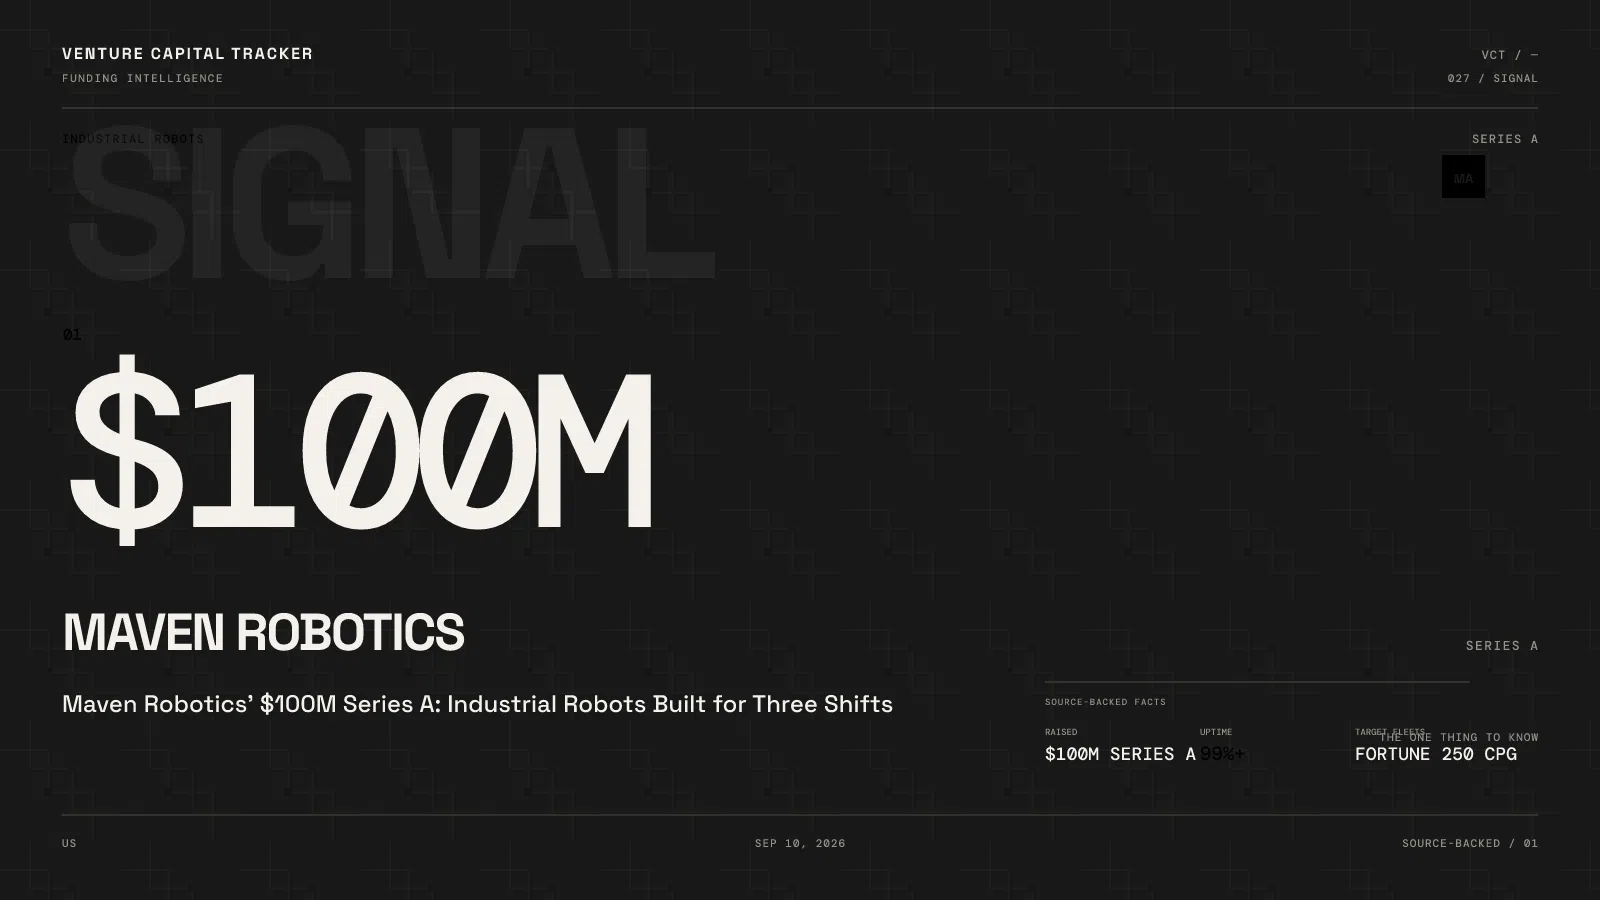
Maven Robotics exited stealth on September 10, 2026, with a $100 million Series A led by RoboStrategy. LocalGlobe, Vine Ventures, and XTX Ventures participated (company / TechCrunch). Valuation was not disclosed.
Humanoid demos win Twitter; mixed-case palletizing wins ROI. Maven’s $100M is a three-shifts-a-day industrial bet — wheeled bases, two arms, vacuum grippers — not a bipedal science project. Not Maven Clinic.
Key facts
| Field | Detail |
|---|---|
| Company | Maven Robotics (mavenrobotics.ai), Santa Clara |
| Round | $100M Series A at launch |
| Lead | RoboStrategy (Jack Pearson) |
| Notable participants | LocalGlobe, Vine Ventures, XTX Ventures |
| Founders | Hamza Derbas (CEO; ex-Apple special projects / EV), Khalid Derbas (CFO) |
| Hardware | Wheeled base ~10 mph; dual arms lift ~30 kg |
| Traction (TC / company) | Up to 8 robots, 16h/day, 99%+ uptime; Fortune 250 CPG; 100k autonomous hours target YE 2026 |
| Near-term plan | Build 250 third-gen robots; start fourth-gen design |
RoboStrategy, Vine Ventures, and XTX Ventures have
Who uses the product — and for what job
Users: logistics and manufacturing operators — starting with CPG distribution centers that rebuild mixed retail pallets from inbound factory pallets on 48-hour demand changes.
Job: end-to-end task autonomy from WMS hook-in to truck-ready mixed pallets, not a single-robot research problem. Company says it won a large CPG deal in 2024 by touring factories first and beating rivals that already had robots.
Company-estimated markets: ~$80B for palletizing/tote handling; >$1T if material handling + assembly expand — treat as TAM framing, not booked revenue.
Why now
- US manufacturing cites 480k+ unfilled jobs (company release); operators need elastic labor that survives heat and multi-shift abuse.
- Physical AI capital is hot; Maven’s differentiation is industrial systems culture (RoboStrategy’s stated reason) vs research-first labs.
- Two years of customer data loops (minutes/hours retrain cycle) make a $100M stealth exit plausible.
Why RoboStrategy + LocalGlobe — portfolio fit
| Investor | Likely fit |
|---|---|
| RoboStrategy | Mandate-aligned robotics specialist underwriting shift reliability over demos |
| LocalGlobe | Early/growth European-rooted capital with appetite for hard-tech category creators |
| Vine / XTX | Scale + markets-oriented capital for a hardware build plan (250 robots) |
Strategic rationale: scale fleets and data flywheels before frontier labs’ next physical model “one-shots” narrow workflows — Derbas told TechCrunch they are racing industrial labor, not model leaderboards.
Competitive map
| Approach | Tradeoff |
|---|---|
| Fixed industrial arms / traditional automation | Proven; brittle to SKU mix changes |
| Bipedal humanoids (e.g. Agility path) | Flexible form; cost/reliability questions (Derbas: legs “make zero sense” for palletizing) |
| Maven wheeled dual-arm fleets | Task-first ROI; must invent manipulation for next workflows |
What remains undisclosed
Valuation, revenue, robot ASP, and customer names beyond “Fortune 250 CPG.” Uptime and hour targets are company/TC-reported until third-party audits exist.
Sources
Follow Venture Capital Tracker in Google
Add VCT as a preferred source to make our venture-capital coverage easier to find in Google Search.
Editorial note: AI tools assisted with research, structure, or drafting. Venture Capital Tracker retains human editorial responsibility for factual accuracy, relevance, and source quality before publication.