· Updated · Venture Capital Tracker · investment-strategies
Fireworks AI’s $1.5B Series D at $17.5B: Specialized Intelligence Hits $1B ARR
Index Ventures co-led Fireworks AI’s $1.505B Series D at a $17.5B valuation in July 2026 as the PyTorch-founded inference platform crossed $1B ARR — with Bessemer, Menlo, and Insight among participants.
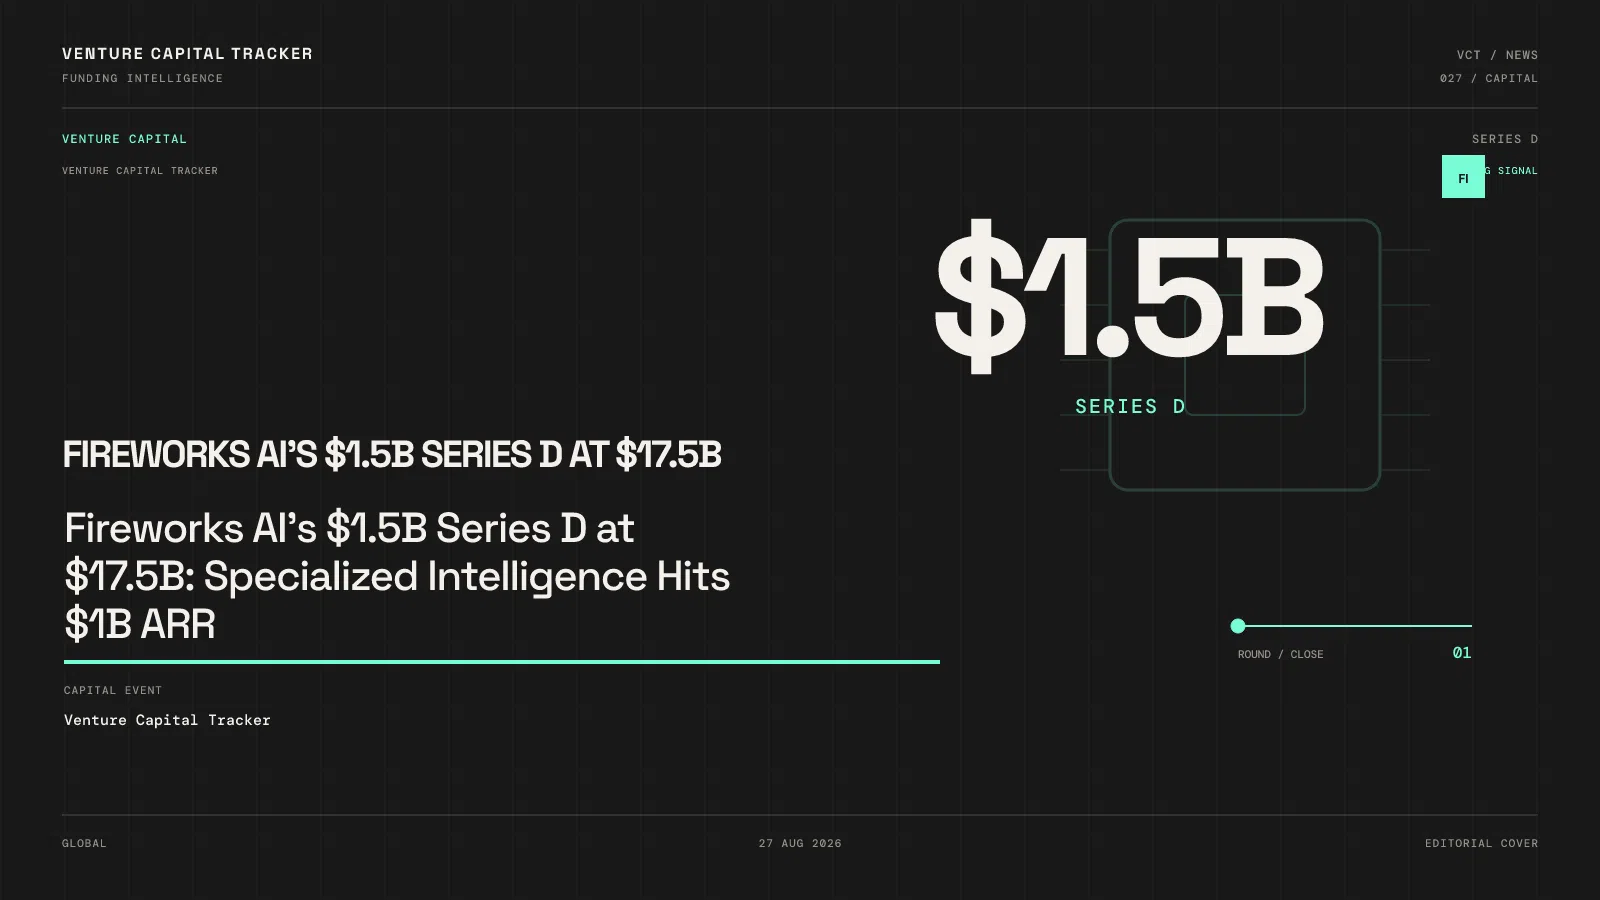
Fireworks AI closed a $1.505 billion Series D at a $17.5 billion valuation (July 15–16, 2026), co-led by Atreides Management, Index Ventures, and TCV — as the company said it crossed $1B ARR.
Key facts
- Co-leads: Atreides Management, Index Ventures, TCV
- Round / valuation: $1.505B Series D / $17.5B
- Date: July 15, 2026 (company blog); July 16 press wire
- Participants we track: Bessemer Venture Partners, Menlo Ventures, Insight Partners; also Nvidia, Lightspeed, Evantic, OTPP, Lone Pine, and others
- Scale claims: $1B ARR (5x YoY vs last round); >40T tokens/day; >95% of tokens from specialized models
- Prior: ~$250M Series C (Oct 2025) at ~$4B post — a steep step-up in under a year
- Roots: Founding team from PyTorch; historically also backed by Sequoia, Benchmark, AMD, Nvidia
Who uses Fireworks — and why
Fireworks sells specialized intelligence infrastructure: train/customize open models on proprietary data, then serve them on a high-performance inference stack.
Named customer examples in company materials: Uber, Shopify, Doximity, Geico, Revolut. The product job is not “chat with a frontier API”; it is own the model that runs your workflow when open weights approach closed-model quality and unit economics matter.
Developers also use Fireworks as a catalog of open models (text, image, embeddings, multimodal) with production serving — adjacent to Together, Baseten, and hyperscaler model platforms.
Why this matters now
Enterprises are moving from renting general intelligence to owning specialized models. Token volumes explode when agents enter production. Fireworks’ disclosed mix — 95%+ specialized tokens — is the market signal: customization is the revenue, not novelty chat.
Why these funds (portfolio fit)
| Firm | Fit |
|---|---|
| Index Ventures | Multi-stage software franchise; longtime Fireworks backer; co-lead keeps ownership and board continuity into late stage |
| Bessemer | Cloud/infra growth book; Cloud Index DNA maps to inference platforms with real ARR |
| Menlo Ventures | AI application + infra crossover; participates as category consolidates |
| Insight Partners | Scale-up software; $1B ARR is classic Insight territory |
Likely company reason to keep Index in the lead group: you do not want a brand-new growth shop learning your unit economics while you raise $1.5B at $17.5B. Index already knows the story; Atreides/TCV/OTPP deepen the late-stage syndicate.
Competitive map
- Inference peers: Together AI, Baseten, Fireworks’ own prior comps, Modal/Anyscale-style stacks.
- Hyperscalers: Bedrock, Vertex, Azure AI Foundry.
- Frontier APIs: OpenAI/Anthropic/Google — Fireworks’ counter is ownership + cost on open/specialized models.
Practical takeaway
- Founders: At this scale, the diligence question is gross margin on specialized serving, not demo latency. Fireworks led with ARR and token mix for a reason.
- Investors: Treat $17.5B as a bet that specialized inference remains a durable layer even if frontier APIs get cheaper — watch open-model quality and Nvidia partnership depth.
Sources
- Fireworks — Series D announcement (Jul 15, 2026): https://fireworks.ai/blog/series-d-announcement
- Fortune / EZ Newswire press release (Jul 16, 2026): https://fortune.com/press-releases/fireworks-raises-1-5b-series-d-reaches-1b-arr-2026-07-16/
- Index Ventures: /fund/index-ventures
Last updated:
Editorial note: AI tools assisted with research, structure, or drafting. Venture Capital Tracker retains human editorial responsibility for factual accuracy, relevance, and source quality before publication.