· Investment Strategies · 2 sources
HiBob’s $166M Salesforce Round: HR Data as Org Intelligence
Salesforce led HiBob’s $166M investment at a CTech-reported ~$3.2B valuation after founder-claimed $400M+ ARR — Farallon returns as HiBob bets workforce context becomes AI infrastructure.

Editorial team
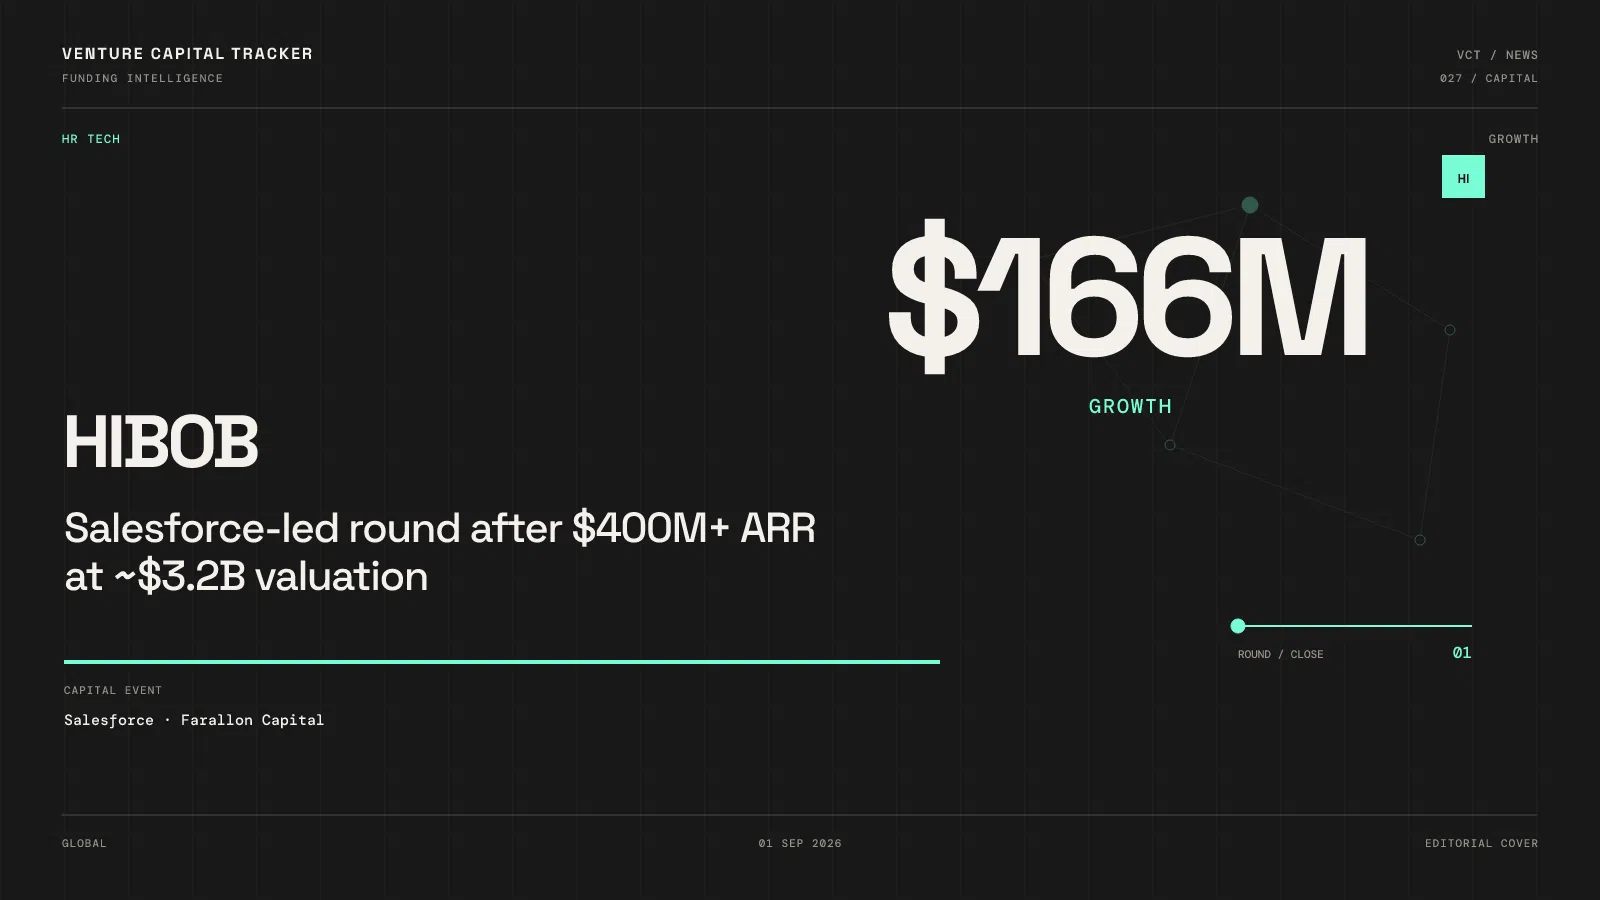
Salesforce led a $166 million investment in HiBob announced September 1, 2026, with Farallon Capital participating (company). CTech reported a ~$3.2 billion valuation, up from Farallon’s prior lead at $2.7 billion. CEO Ronni Zehavi told CTech annualized revenue topped $400 million; HiBob cites 5,500+ customers in 170+ countries (SiliconANGLE).
Spine: HRIS vendors are repositioning trusted people data as the context layer for enterprise AI agents — Salesforce’s cheque is distribution thesis as much as growth equity.
Key facts
- Company
- HiBob
- Round
- $166M growth investment
- Lead
- Salesforce
- Returning
- Farallon Capital (prior lead at $2.7B)
- Valuation
- ~$3.2B (CTech reported)
- ARR
- $400M+ annualized (founder to CTech)
- Customers
- 5,500+ (company)
- IPO
- No current plans (founder)
Who uses the product — and for what job
Users: mid-market and enterprise people ops / HR / finance teams that need a system of record for employees, skills, recruiting, learning, and org structure.
Job today: run HR, payroll, and workforce workflows in Bob. Job HiBob is selling next: expose that organizational context — roles, skills, teams, permissions, incentives — into Slack and other systems so AI agents act with real org truth rather than generic prompts.
Product surface already includes AI job-description generation, multi-board posting, CV summaries, workforce simulations, learning, and MCP sync to external automation tools (SiliconANGLE).
Why now
- Agent rollouts fail when models lack permissions, reporting lines, and skills inventory.
- Slack/Salesforce Labs commentary in the announcement explicitly frames HiBob as workforce-context infrastructure.
- At ~$400M ARR and no IPO urgency, the round looks like strategic alignment capital, not a survival raise.
Why Salesforce — portfolio fit
Salesforce gets a deeper wedge into people + agent workflows alongside Slack; HiBob gets distribution and product co-travel into the systems where managers already work. Farallon’s return bridges prior financial sponsorship into the new strategic chapter.
Likely founder rationale: raise from the collaboration/CRM giant that can make “headless org intelligence” real inside Slack — not another pure financial growth fund at this stage.
Salesforce and Farallon Capital are not in our fund directory — editorial only.
Competitive map
| Approach | Tradeoff |
|---|---|
| Legacy HRIS (Workday / SAP SuccessFactors) | Deep enterprise; heavier mid-market motion |
| Point AI HR tools | Fast features; weak system-of-record trust |
| Suite-native Agentforce alone | Strong Salesforce-native path; weaker independent HRIS depth |
| HiBob as HRIS + context layer | Strong mid-market base; must prove agent distribution |
What is not proven
- Exact primary vs secondary mix inside the $166M not broken out in the company post.
- Valuation is CTech-reported, not a full company 8-K-style disclosure.
- “Organizational intelligence” revenue vs core HRIS revenue mix not disclosed.
Practical takeaway
- Founders (vertical SaaS): When ARR is already large, strategic rounds are about where AI will consume your data, not just runway.
- Investors: Diligence net retention and AI attach — the $3.2B stamp assumes org context becomes durable infrastructure.
- Operators: Relevant if agent projects stall because HRIS data never reaches the tools managers use.
Follow Venture Capital Tracker on Google
Add VCT as a preferred source to see more of our venture-capital reporting in Google Search.
Editorial note: AI tools assisted with research, structure, or drafting. Venture Capital Tracker retains human editorial responsibility for factual accuracy, relevance, and source quality before publication.