· Investment Strategies · 1 source
Graph AI’s $13.3M Series A: Insight Bets on AI Pharmacovigilance
Insight led $13.3M Series A for Graph Safety on Sep 10, 2026, with Bessemer returning — company claims live PV deployments cut case turnaround >90% and opex up to 66% for pharma safety teams.

By Venture Capital Tracker Editorial
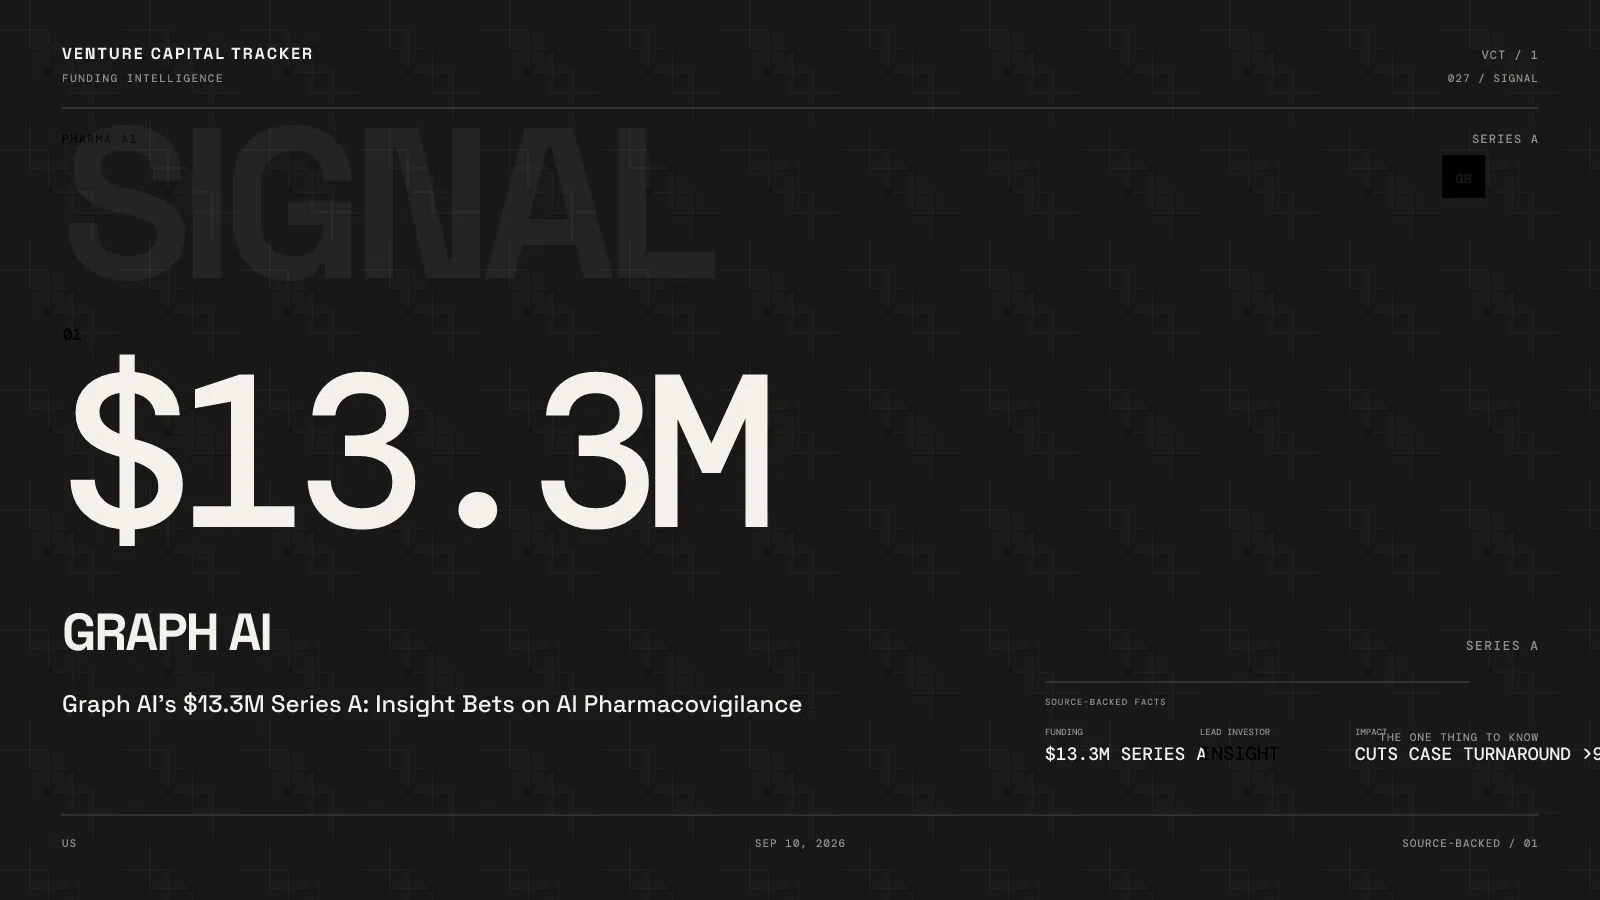
Graph AI closed a $13.3 million Series A on September 10, 2026, led by Insight Partners, with Bessemer Venture Partners returning after leading the October 2025 seed (company PR). Valuation and ARR were not disclosed.
Pharmacovigilance has scaled by hiring people around legacy case systems. Graph’s bet is that regulated AI with audit trails can eat the services layer — and Insight is underwriting measured turnaround cuts, not a chatbot demo.
Key facts
- Company
- Graph AI (graphsafety.ai), Pleasanton, CA
- Round
- $13.3M Series A
- Lead
- Insight Partners (Richard Matus quoted)
- Returning
- Bessemer (seed lead, Oct 2025)
- Founded
- 2024 — CEO Raghav Parvataraju
- Modules
- /intake, /nucleus live; /report launching Sep 2026; /signal in design partnerships
- Claimed outcomes
- Case TAT >3h → <10 min; opex down up to 66% (company)
Who uses the product — and for what job
Users: pharmaceutical and biotech patient-safety / PV teams that currently stitch intake channels, case databases, and aggregate reports with manual handoffs.
Job: capture adverse events across channels → automate case processing with deterministic controls and audit trails → keep humans on judgment and signal analysis. The company positions the stack against FDA AI credibility guidance, the EU AI Act, and CIOMS WG XIV expectations — treat that as design intent, not a regulatory approval claim.
Named customer logos were not listed in the Series A release; the company says it has onboarded pharma/biotech customers in North America and other markets.
Why now
- Case volumes rise while PV orgs remain people + process heavy.
- Generics “AI for safety” without traceability fail inspection culture; Graph’s pitch is AI plus deterministic validation.
- Seed-to-Series A in under a year with two shipped modules is the product proof Insight is buying.
Why Insight + Bessemer — portfolio fit
| Investor | Likely fit |
|---|---|
| Insight | Scale-up software that replaces services spend inside enterprises — classic Insight pattern |
| Bessemer | Seed conviction recycle; healthcare AI portfolio adjacency (Abridge et al. in firm narrative) |
Strategic rationale for raising now: US/Europe expansion and shipping /report + /signal while the services incumbents still sell integration labor.
Competitive map
| Approach | Tradeoff |
|---|---|
| Legacy PV vendors + BPOs | Installed base; slow / expensive ops |
| Point AI copilots on old databases | Fast demos; weak audit story |
| Graph Safety AI-native OS | End-to-end modules; must win regulated validation cycles |
What remains undisclosed
Valuation, ARR, customer count, and whether the 90%/66% figures are median or best-case sites. Those are the numbers that turn a strong PR claim into underwritable SaaS math.
Follow Venture Capital Tracker on Google
Add VCT as a preferred source to see more of our venture-capital reporting in Google Search.
Editorial note: AI tools assisted with research, structure, or drafting. Venture Capital Tracker retains human editorial responsibility for factual accuracy, relevance, and source quality before publication.