· Venture Capital Tracker Editorial · investment-strategies
Factory’s $200M at $5B: Coding Agents Triple in Five Months
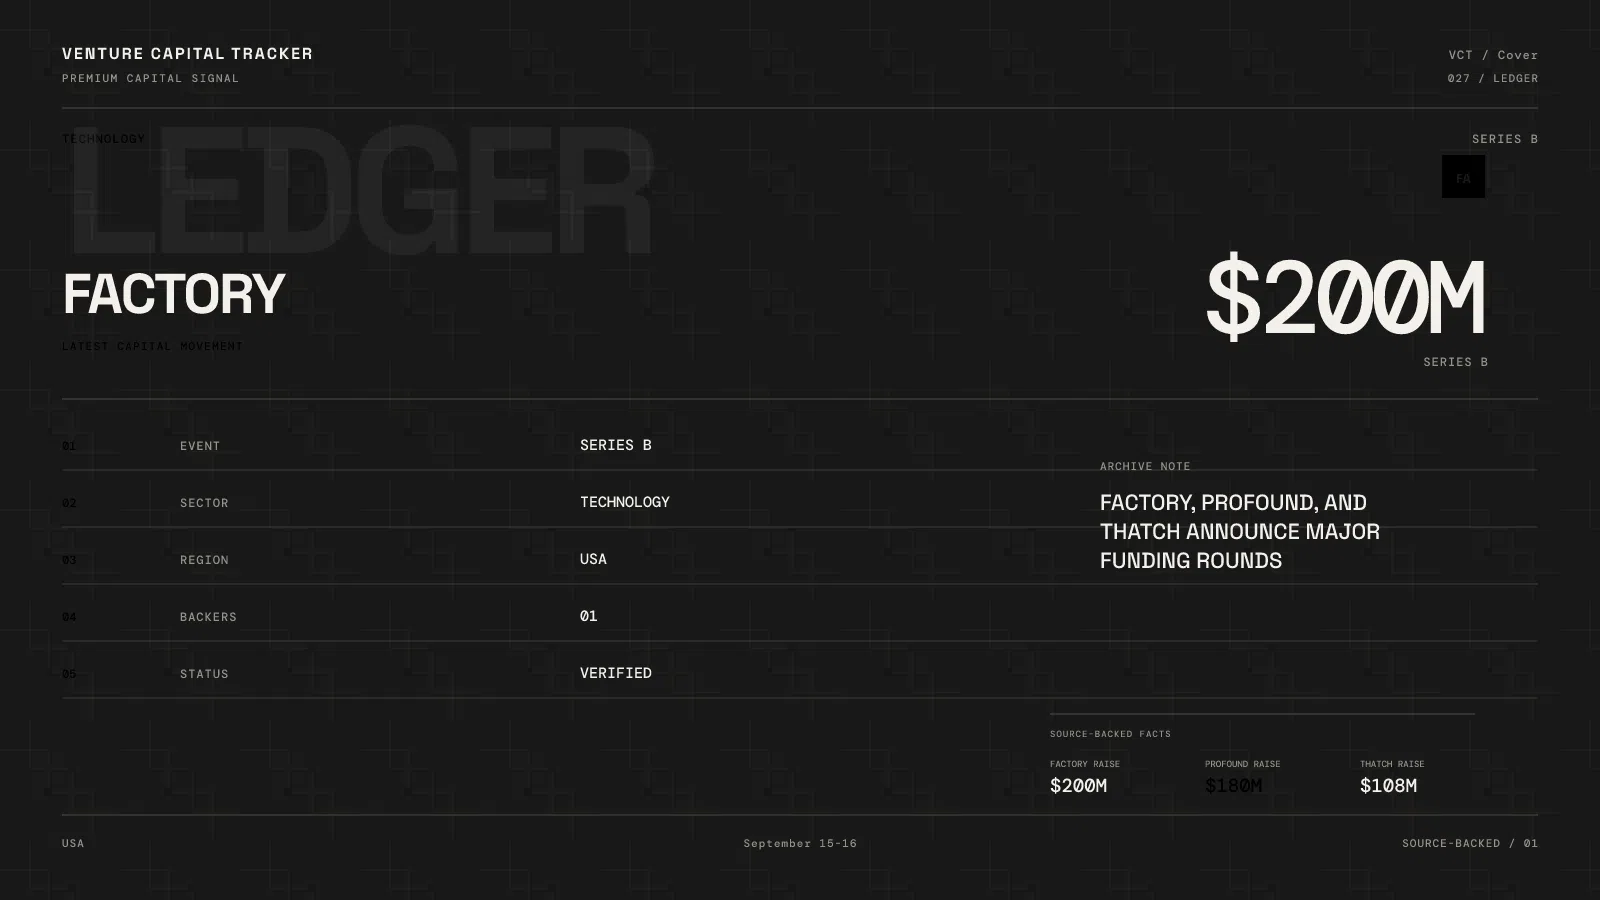
Factory raised $200 million at a $5 billion valuation on September 15, 2026 — more than tripling its April $1.5 billion mark. Blackstone, Khosla, Sequoia, and Insight backed; no lead named. ARR not disclosed.
Factory raised $200 million at a $5 billion valuation on September 15, 2026, more than tripling the $1.5 billion mark from its April 2026 $150 million round. Backers named by the company include Blackstone, Khosla Ventures, Sequoia Capital, Insight Partners, Evantic Capital, Sound Ventures, NEA, Mantis VC, and Clearlake. A lead was not named. Total funding is over $400 million. ARR was not disclosed (company, Reuters).
Five months after a $1.5B print, the same franchise re-priced at $5B on named enterprise logos and “software factory” positioning — without printing revenue.
Key facts
| Field | Detail |
|---|---|
| Company | Factory (factory.com) — enterprise AI agents / software factories |
| Financing | $200M at $5B valuation (unnamed stage) |
| Date | September 15, 2026 |
| Prior | $150M at $1.5B (April 2026) |
| Total funding | >$400M (company) |
| Lead | Not named |
| Named customers (company) | Nvidia, Blackstone, RBC, Palo Alto Networks, Adobe, T-Mobile |
| ARR / seats | Not disclosed (company says “hundreds of thousands of developers”) |
Who uses the product — and for what job
Users: enterprise engineering orgs that need governed, measurable agentic coding — not a consumer chatbot IDE.
Job: run a single controlled “software factory” across the SDLC (cloud, on-prem, or air-gapped) instead of stitching standalone coding agents. Company product claims around the raise: Factory Router (task-level model routing; >60% token-spend cut claim), air-gapped / high-security deployment, and Agent Effectiveness visibility into AI spend ROI.
Named logos (Nvidia, Blackstone, RBC, Palo Alto Networks, Adobe, T-Mobile) are customer claims, not audited seat or ARR evidence. Treat “hundreds of thousands of developers” as a usage claim until economics print.
Why now
- The 3.3× mark move in five months is the anomaly — capital is racing to own the enterprise control plane for coding agents, not the next chat wrapper.
- Security and deployment surface (air-gap, regulated customers) is the wedge vs consumer coding tools that cannot sit inside bank/gov constraints.
- Cognition’s September $48B Series E tape (our note) keeps the category hot; Factory is pricing as ops infrastructure, not a single-agent brand.
Why these funds — portfolio fit
No lead was disclosed, so fit is about who showed up again, not a single thesis memo.
- Khosla Ventures led or anchored the April round (secondary reporting) and returns here — consistent with high-conviction AI infrastructure bets that reprice fast when enterprise logos land.
- Sequoia and Insight Partners fit enterprise scale and go-to-market expansion; Insight’s growth DNA matches a “global GTM” use of proceeds.
- Blackstone as both customer and capital is the tell: the buyer of the product is also underwriting the mark — unusual signal, still not a substitute for ARR.
Do not invent a Series letter or revenue multiple. Do not link Lightspeed NYC, NEA, Evantic, Sound Ventures, Mantis, or Clearlake as /fund/ pages — they are not in our directory.
Competitive map
| Approach | Tradeoff |
|---|---|
| Consumer coding copilots | Fast individual speed; weak enterprise governance |
| Point agent tools | Strong demos; fragmented SDLC control |
| In-house agent stacks | Full control; slow to productize |
| Factory “software factory” | Named enterprise logos; no ARR in the raise |
What is not proven
- ARR, NRR, seat price, or gross margin.
- Which investor led / priced the round.
- Whether “hundreds of thousands of developers” means MAU, seats, or cumulative signups.
- Profitability — not disclosed.
Practical takeaway
- Founders (dev tools): Sell governed deployment + measurable ROI, then raise on logos — Factory still did not print ARR at $5B.
- Investors: Diligence token economics and air-gap attach; do not treat a 3× mark as proof of 3× revenue.
- Operators: Relevant if you need one controlled agent platform across regulated SDLC environments.
Sources
Follow Venture Capital Tracker in Google
Add VCT as a preferred source to make our venture-capital coverage easier to find in Google Search.
Last updated:
Editorial note: AI tools assisted with research, structure, or drafting. Venture Capital Tracker retains human editorial responsibility for factual accuracy, relevance, and source quality before publication.