· Investment Strategies · 3 sources · Updated · Verified
D-Robotics Raises $400M Series C for Sunrise Robot Chips
D-Robotics closed a $400M Series C (Mirae led per Yicai) after claiming 8M+ Sunrise chip shipments and 20+ embodied-AI customers on S600 — who buys the silicon and why the round fits industrial robotics.

By Venture Capital Tracker Editorial
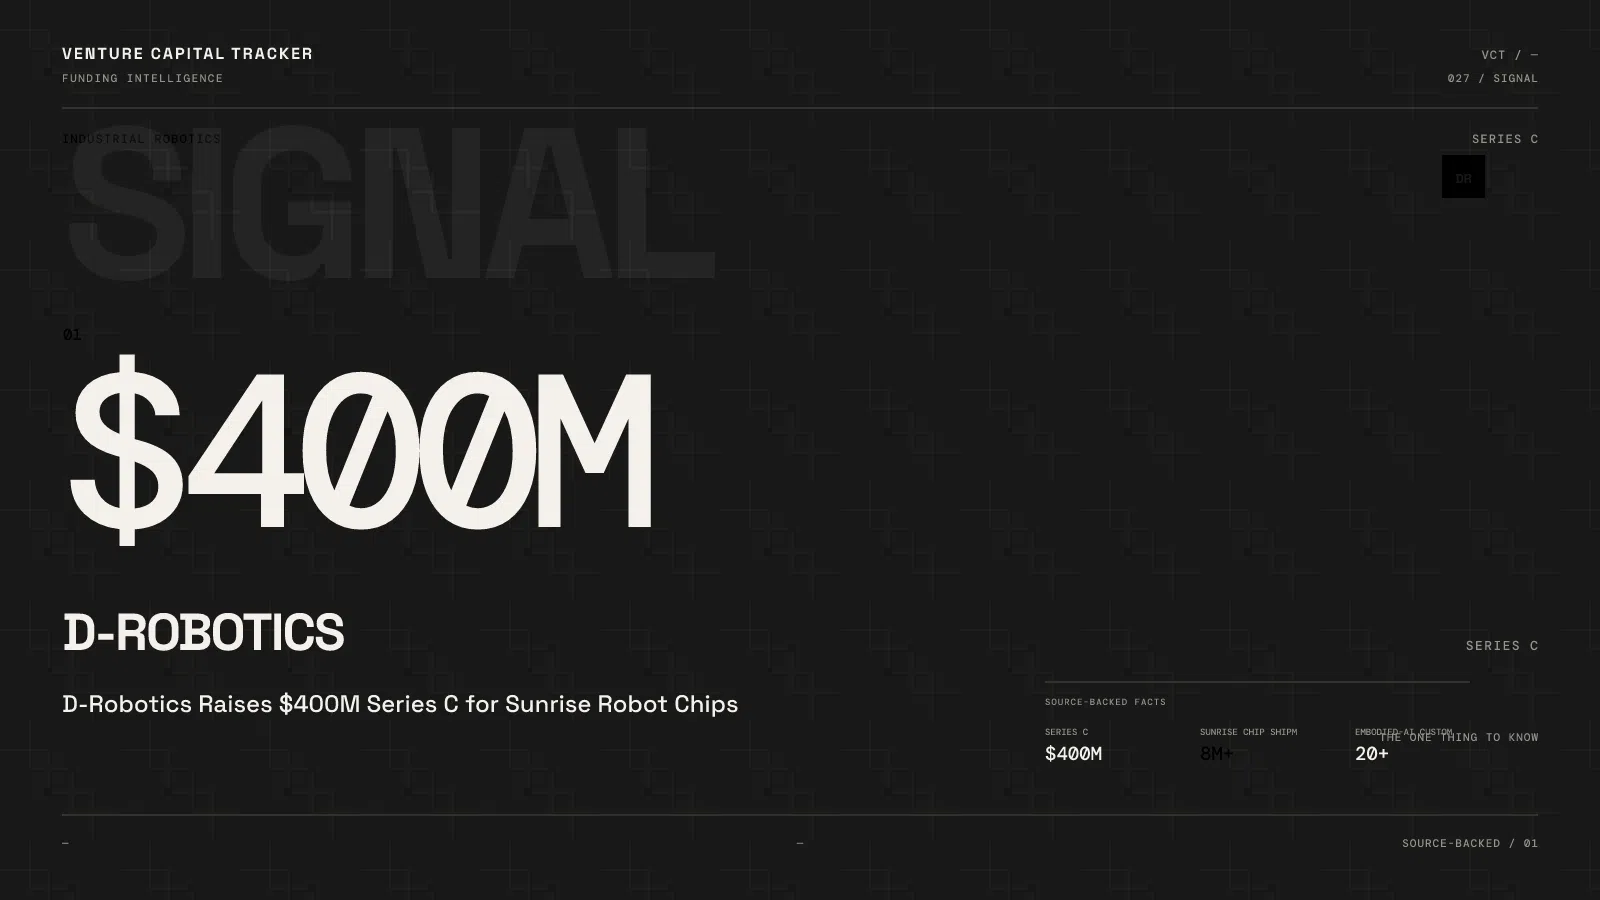
D-Robotics closed a $400 million Series C announced September 17, 2026. Yicai named Mirae Asset as lead with Meituan and government-backed platforms in; the company PR Newswire release described a “leading global internet company,” institutions, and existing shareholders without naming Mirae.
See VCT's robotics sector coverage for related startups and funding activity.
this is a silicon + stack round with company-claimed 8 million+ Sunrise chip shipments — not a humanoid OEM raise dressed up as infrastructure.
Key facts
- Company
- D-Robotics — Horizon Robotics spinout (Jan 2024)
- Round
- $400M Series C
- Date
- September 17, 2026
- Lead
- Mirae Asset (Yicai); unnamed in company PR
- Strategic
- Meituan (Yicai); “global internet company” (PR)
- Valuation
- Not disclosed
- Shipments (company)
- Sunrise series >8M cumulative
- S600
- Launched Nov 2025; 20+ embodied-AI customers in six months
- Named customers
- TARS, Spirit AI, X Square Robot, UBTECH, PaXini, Astribot, FOURIER, Booster Robotics
- Revenue
- H1 2026 “several times” YoY (company — no absolute dollar figure)
- Use of proceeds
- Sunrise portfolio across compute tiers; full-chain software (data → deploy)
Who uses the product — and for what job
Users: robot OEMs (humanoid, wheeled, companion, AMR), embodied-model teams needing edge compute, and universities/developers on RDK kits (company: 500+ universities, 100k+ developers, 20+ countries).
Job: buy a compute + toolchain substrate so a robot team is not reinventing chips, OS layers, and sim-to-deploy pipes. The Gravity Program (DGP) adds GTM and fundraising support for innovators — a platform play, not a single product SKU.
Named S600 adopters span humanoids and industrial wheeled robots; the release says the majority are already in mass production. That is the diligence line versus demo-stage peers covered alongside Antioch (simulation) or PHYMI (embodied seed with amount fuzz).
Why now
- Embodied AI moved from lab videos to category boom — OEMs need volume silicon and shared software rails.
- D-Robotics already printed large 2026 B rounds (Yicai/Gasgoo summaries differ on B1/B2 splits; treat prior totals carefully). Series C funds the next compute tiers and a software platform that looks like “Nvidia for robots” messaging without claiming Nvidia parity.
- Cross-border capital (Korean asset manager + Chinese strategic) signals that robotics compute is treated as industrial infrastructure, not only domestic softtech.
Why Mirae / Meituan — portfolio fit
Mirae Asset (per Yicai) brings large-check Asia growth capital into hardware platforms. Meituan adds distribution and ops adjacency for robots in logistics and services. Existing Horizon-era shareholders rolling forward keeps continuity after the 2024 spin.
**
| Investor | Fit |
|---|---|
| Mirae | Growth check size for hardware platforms |
| Meituan | Strategic customer/channel adjacency |
| Existing shareholders | Continuity post-spinout |
Strategic rationale: raise enough to fund multi-tier silicon and software without selling control to a single strategic that would limit OEM customers; keep Meituan as a partner, not the sole buyer.
Competitive map
- NVIDIA Jetson / Isaac — global default outside China.
- Horizon Robotics — parent lineage; ADAS vs robotics focus.
- Humanoid OEMs — customers (UBTECH, FOURIER), not peer chip vendors.
Do not confuse chip shipments with robot units sold.
What remains undisclosed
- Valuation and ownership.
- Absolute revenue and margins behind “several times” growth.
- Exact prior 2026 B-round totals (press conflicts).
- How much of S600 design wins are exclusive vs multi-sourced.
Implication
If the shipment and mass-production claims hold, D-Robotics is a bet that robotics scales like phones once compute is cheap and standardized — and that Asia’s capital stack will keep funding the substrate while Western coverage stays stuck on humanoid demos. The unresolved question is whether Sunrise becomes a default BOM line outside China or remains a regional stack.
Follow Venture Capital Tracker on Google
Add VCT as a preferred source to see more of our venture-capital reporting in Google Search.
Last updated:
Editorial note: AI tools assisted with research, structure, or drafting. Venture Capital Tracker retains human editorial responsibility for factual accuracy, relevance, and source quality before publication.