· Investment Strategies · 3 sources
Crusoe Confirms $3.9B Series F at $30.9B — AI Factories, Not Just Capex
Company-confirmed Series F: $3.9B at $30.9B post-money, co-led by Atreides, Mubadala Capital, and Valor. $140B+ TCV and 6 GW contracted capacity — who buys Crusoe and why Founders Fund and Nvidia stay in.

By Venture Capital Tracker Editorial
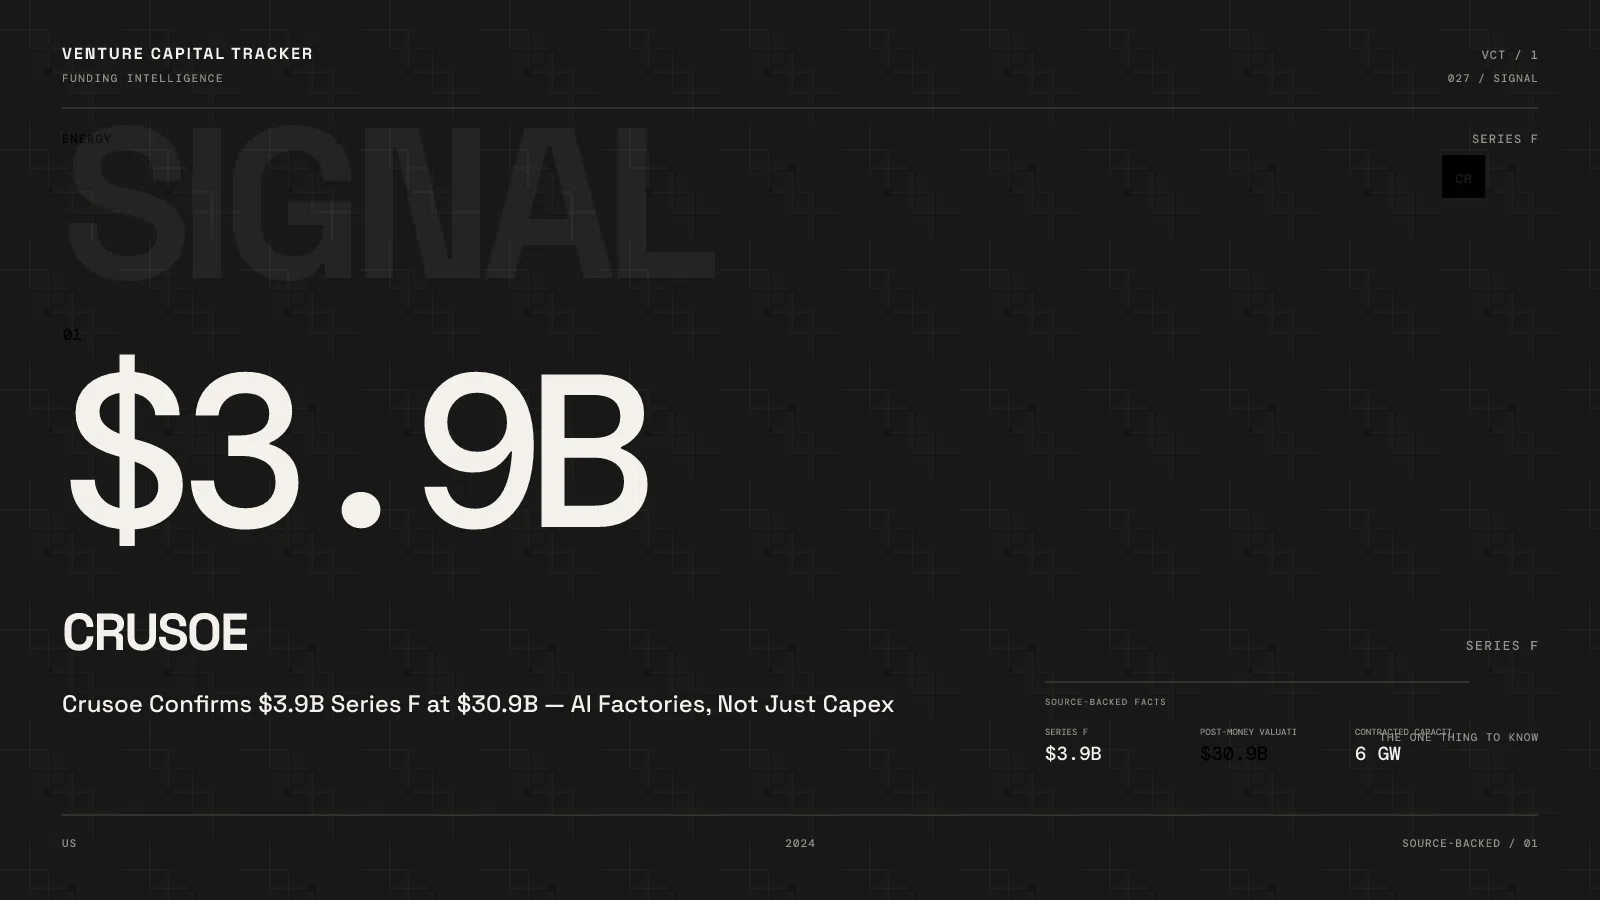
Crusoe confirmed the initial close of a $3.9 billion Series F on September 17, 2026, at a $30.9 billion post-money valuation. Atreides Management, Mubadala Capital, and Valor Equity Partners co-led. Named backers include Founders Fund, GIC, NVIDIA, QIA, Radical Ventures, TPG, and Ribbit Capital.
the September 3 “~$3B / ~$30B” leak is now a priced, company-owned Series F — and the story is contracted megawatts plus inference ARR, not another abstract neocloud mark-up.
Key facts
- Company
- Crusoe — Denver; founded 2018 (flare-gas crypto → AI infra)
- Round
- $3.9B Series F (initial close) · $30.9B post-money
- Date
- September 17, 2026
- Co-leads
- Atreides Management, Mubadala Capital, Valor Equity Partners
- Named participants (selected)
- Founders Fund, GIC, NVIDIA, QIA, Radical Ventures, TPG, Ribbit Capital, plus a long crossover/LP list
- Prior print
- Oct 2025: $1.38B at ~$10B (TechCrunch)
- Earlier Sep tape
- Sep 3 Bloomberg reported ~$3B / ~$30B — prior memo
- Company traction claims
- >$140B TCV; 6 GW+ contracted capacity (1 GW operational); Managed Inference >$100M contracted ARR; 20x+ YoY Crusoe Cloud bookings YTD
- Use of proceeds
- Scale existing programs + AI factories (campuses + modular Spark units) + Crusoe Cloud
Who uses the product — and for what job
Users: frontier labs, hyperscalers, trading firms, and enterprises that need power + GPUs + cloud faster than traditional colo can deliver.
Jobs Crusoe sells:
- Campus build / colo — lease capacity (e.g. OpenAI-linked Abilene site per TechCrunch).
- GPU cloud / inference — rent compute; company claims Managed Inference already >$100M contracted ARR.
- Modular Spark factories — truckable units aimed at power sites without multi-year campus fights.
Press-cited logos include Meta, Microsoft, Oracle, and OpenAI. Bloomberg’s ~$13B / five-year Jane Street GPU contract remains reported — the Series F release does not restate it.
Why now
- October 2025 was ~$10B. Seventeen days after Bloomberg’s leak, Crusoe locked $30.9B with a $3.9B equity close — roughly a 3× mark in under a year if you take company and prior TechCrunch figures at face value.
- Company-disclosed 6 GW contracted and $140B+ TCV are the diligence numbers that make a multi-billion equity round look like project finance with a venture wrapper.
- Modular Spark is explicitly a response to community backlash and construction labor scarcity (TechCrunch framing) — speed-to-power is the product.
- Axios reported bankers (Goldman, Morgan Stanley) in the mix for a potential IPO; Series F is dry powder and a public-market reference, not a substitute for offtake.
Why these funds — portfolio fit
| Investor | Likely job on the check |
|---|---|
| Atreides / Valor / Mubadala | Size + infra underwriting; Atreides CIO Gavin Baker framed “lowest-cost producer of intelligence” via vertical integration (company release) |
| Founders Fund | Returning hard-tech / energy-to-compute thesis; continuity from earlier Crusoe exposure |
| NVIDIA | Strategic alignment with Exemplar Cloud / GPU demand — not a pure financial LP |
| Ribbit Capital | Fintech/AI infra crossover; adds public-market-adjacent network without owning a /fund/ for every sovereign on the list |
| GIC / QIA / TPG | Late-stage and sovereign scale for multi-GW capex |
Strategic rationale: keep the three co-leads who can write mega-checks, keep Nvidia in the room for supply and cloud credibility, and keep Founders Fund as the venture narrative anchor while sovereigns and crossovers fill the book.
Do not invent /fund/ links for Atreides, Mubadala Capital, Valor Equity, GIC, QIA, Radical Ventures, TPG, or Altimeter — they are not in our directory.
Competitive map
| Player | Lane vs Crusoe |
|---|---|
| Nscale | Neocloud / AI factory peer; $3.5B was talks, not this close |
| Firmus | AI factory buildout with different capital mix |
| Hyperscaler self-build | Captive capacity; Crusoe sells speed and third-party optionality |
| Traditional colo (Equinix, Digital Realty) | Power + shells; weaker “electrons to tokens” stack |
Missing numbers (treat as information)
- No ARR for the whole company in the Series F release — only Managed Inference >$100M contracted ARR.
- Jane Street $13B still Bloomberg-attributed, not company-restated here.
- Cap table percentages and primary vs secondary split undisclosed.
Practical takeaway
- Founders (infra): Contracted GW and TCV beat “AI demand” slides when the check is nine figures.
- Investors: Diligence power origination, interconnection, and customer concentration — valuation is a multiple of scarcity, not software SaaS math.
- Operators: Ask whether you are buying campus, cloud GPUs, or inference SLA — Crusoe sells all three.
Follow Venture Capital Tracker on Google
Add VCT as a preferred source to see more of our venture-capital reporting in Google Search.
Editorial note: AI tools assisted with research, structure, or drafting. Venture Capital Tracker retains human editorial responsibility for factual accuracy, relevance, and source quality before publication.