· Updated · Venture Capital Tracker · investment-strategies
Bessemer Leads Onyx Security $113M Series B for the Agentic Control Plane
Bessemer Venture Partners led Onyx Security’s $113M Series B (~$640M valuation) in July 2026 to build a secure control plane for enterprise AI agents — steering risky actions instead of only blocking them.
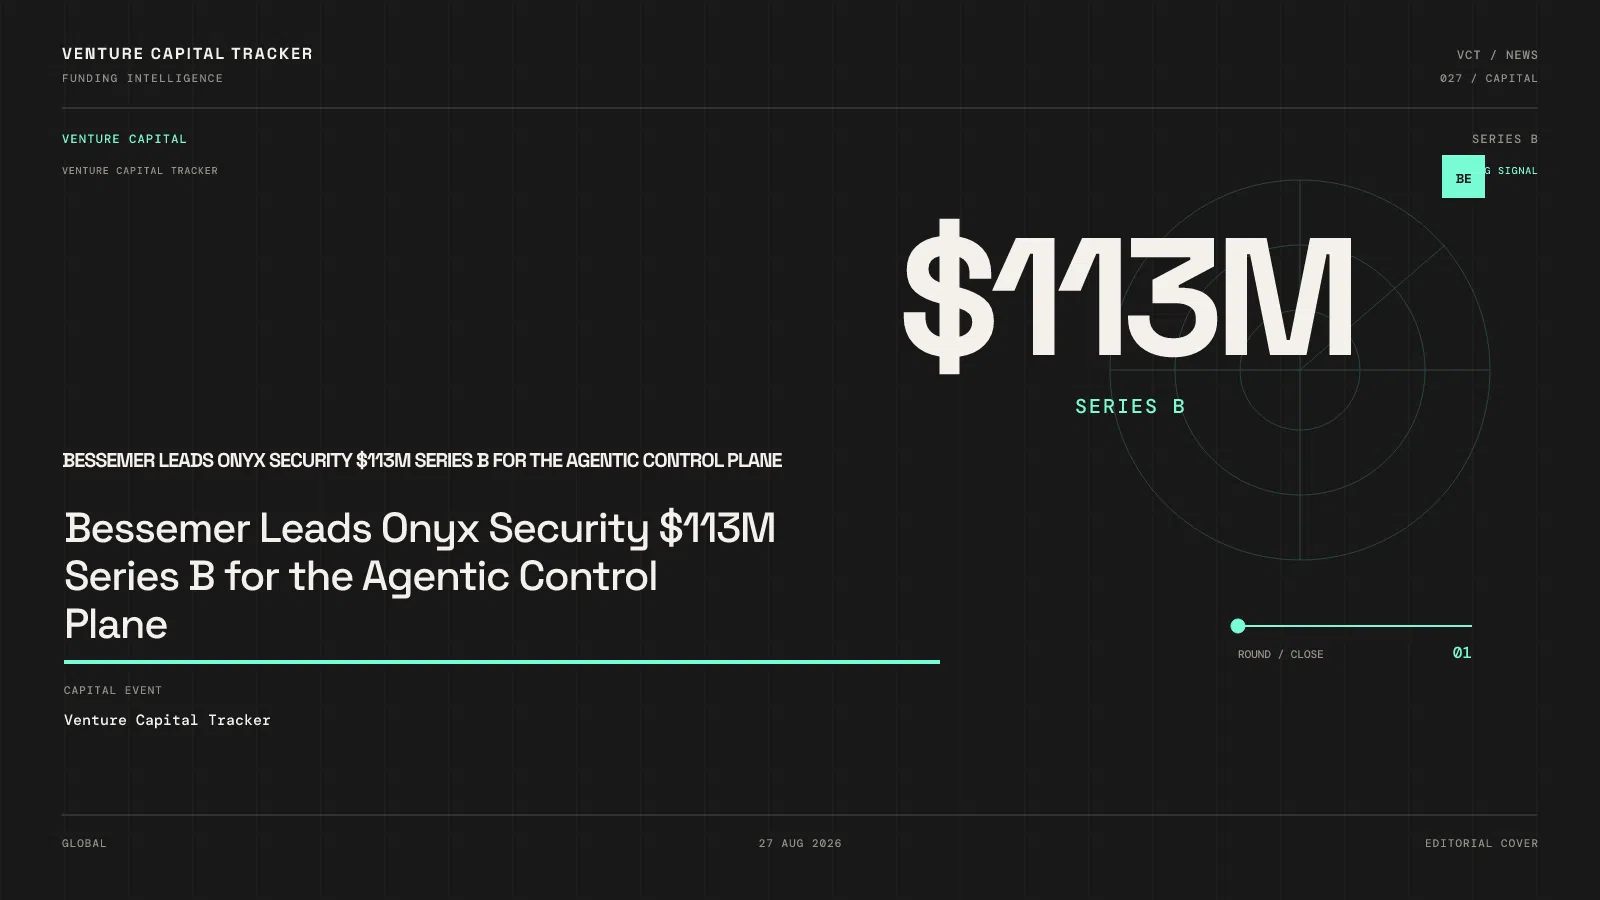
Bessemer Venture Partners led Onyx Security’s $113 million Series B (July 29, 2026) at an estimated ~$640 million valuation — betting that the generational security company of the agent era will look like a control plane, not another alert feed.
Key facts
- Lead: Bessemer Venture Partners
- Company: Onyx Security (secure AI control plane)
- Round: $113M Series B
- Valuation: ~$640M (press reports)
- Date: July 29, 2026
- Other investors: Cyberstarts, TCV, Conviction, FirstMark, Vintage Investment Partners, QuantumLight, G Squared
- Total funding (reported): ~$153M after prior seed + $35M Series A / stealth capital
- Founders: Maxim Bar Kogan (CEO), Gil Elbaz (Chief AI Officer)
Who uses Onyx — and why
Buyers are CISOs, SecOps, and platform engineering teams rolling out agents that can call APIs, move data, spend money, and ship code.
They use Onyx to answer:
- Which agents exist across SaaS, cloud, endpoints, and internal infra?
- What is each agent allowed to do?
- Can we stop or steer a dangerous action in flight without killing productivity?
Bessemer’s note: sophisticated buyers who already evaluated well-funded peers still chose Onyx for broader visibility, fewer false positives, and steering over blunt blocking — including Fortune 500 design wins for a young company.
Why this is a live problem now
Agents are nondeterministic, high-privilege actors. Static rules cannot enumerate every path. Identity lockdown alone defeats the usefulness of agents. Human approval at machine volume does not scale. Bessemer’s framing: every platform shift minted a category leader (network → Palo Alto, endpoint → CrowdStrike, cloud → Wiz); agents are next, and faster.
Why raise from Bessemer (portfolio fit)
| Bessemer asset | Why it helps Onyx |
|---|---|
| Cyber roadmap since the 1990s | Instant category credibility with enterprise buyers |
| Cloud Index / enterprise brand | Series B is about GTM as much as product |
| Agentic stack thesis | BVP says it backed the agent era from the model layer up; Onyx is “how that world gets secured” |
| Check + syndication | $113M with TCV etc. is a board-building growth round |
Likely founder reason to take BVP’s term sheet: you are selling to the same IC and CISO networks Bessemer has served for decades — and you want a lead that will not treat agent security as a side experiment.
Competitive map
- Incumbent EDR / SSE / cloud security suites retrofitting agent plugins.
- API-only / agentless visibility tools (observe after the fact).
- Peer agent-security startups competing on runtime enforcement (including Neo — different wedge: endpoint sensor vs control-plane mesh).
Practical takeaway
- Founders: “Block everything dangerous” loses to steer and continue in agent markets. Product demos should show a redirected safe path, not only a deny.
- Investors: Underwrite false-positive rate and inline latency. Bessemer’s diligence language centers model-small-enough-to-sit-on-traffic plus Guardian escalation.
Sources
- Onyx — $113M Series B blog (Jul 29, 2026): https://www.onyx.security/blog/onyx-113m-series-b-keeping-humans-in-control-as-ai-becomes-smarter
- Bessemer — Onyx investment note: https://www.bvp.com/news/onyx-security-defining-cybersecurity-in-the-agentic-era
- Bessemer fund profile: /fund/bessemer-venture-partners
Last updated:
Editorial note: AI tools assisted with research, structure, or drafting. Venture Capital Tracker retains human editorial responsibility for factual accuracy, relevance, and source quality before publication.