· Venture Capital Tracker Editorial · investment-strategies
Aqua’s $15M Series A: Arthur Ventures Funds Alts Operating Software
YC-backed Aqua raised $15M Series A led by Arthur Ventures on Sep 9, 2026 ($18.8M lifetime) to turn its alternatives marketplace into TAIP infrastructure for advisers and sponsors — not another access app.
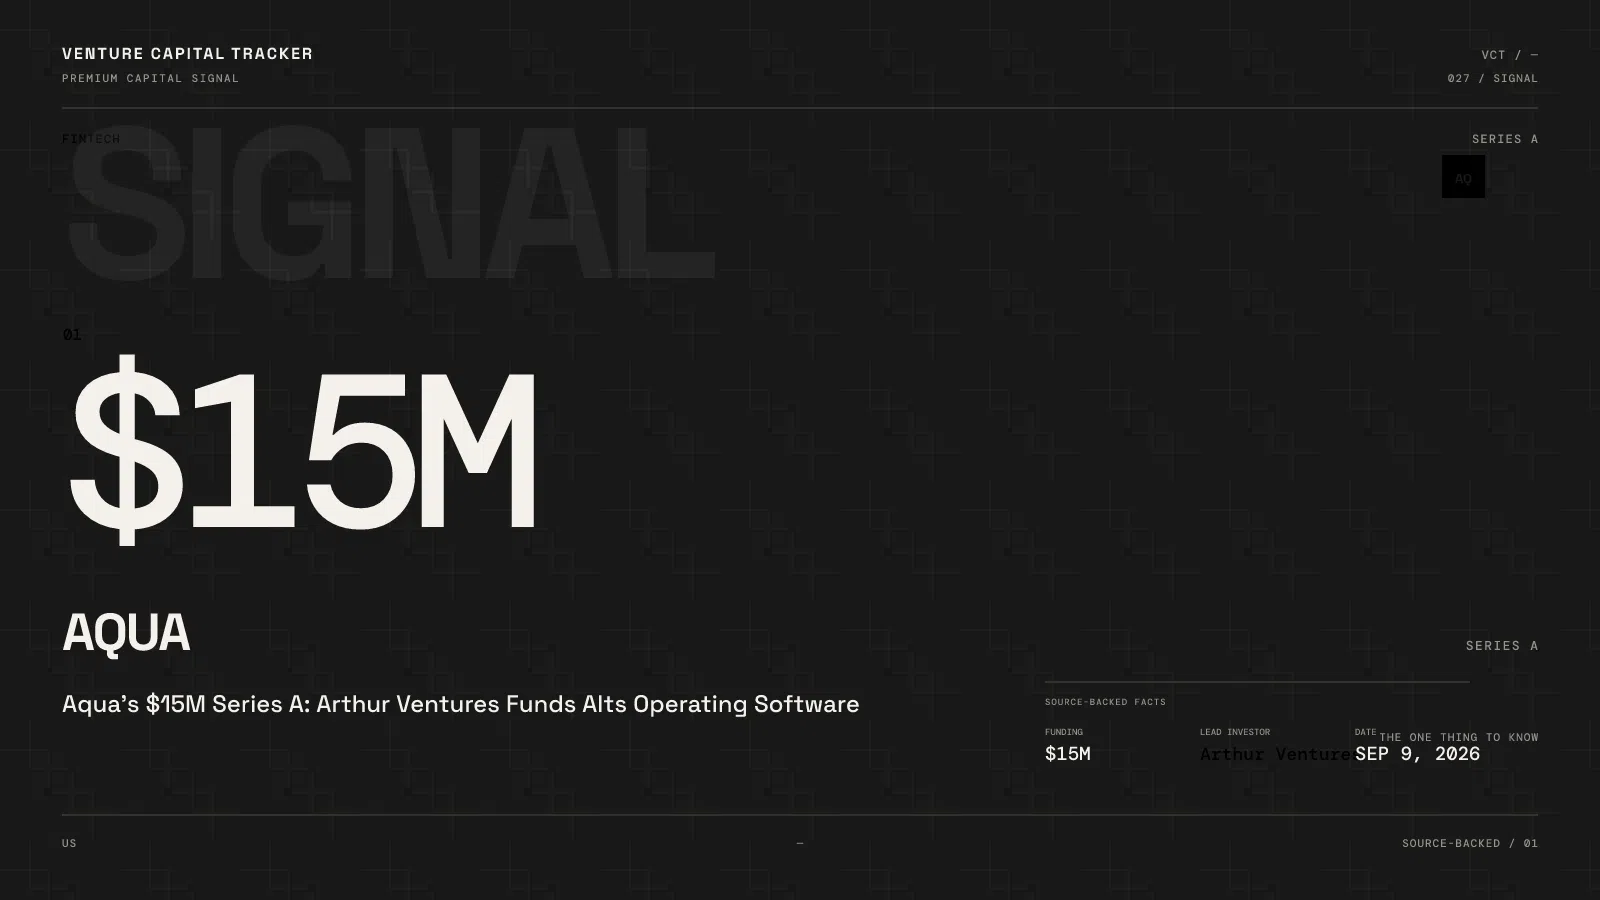
Aqua (the wealthtech TAIP company — not Aqua Security) raised $15 million Series A on September 9, 2026, led by Arthur Ventures with Alumni Ventures (FinSMEs; FinTech Global). Lifetime funding: $18.8 million including a $3.8 million seed backed by Gradient Ventures and Y Combinator. Valuation was not disclosed.
Alts access got easier. The expensive part is still subscriptions, vehicles, documents, and servicing. Aqua is raising to own that operating layer.
Key facts
| Field | Detail |
|---|---|
| Company | Aqua (investwithaqua.com) |
| Round | $15M Series A ($18.8M lifetime — not one close) |
| Lead | Arthur Ventures |
| Also | Alumni Ventures; prior seed: Gradient + YC (S21) |
| Founders | Rohan Marwaha (ex-Blackstone ops insight), Dev Patel |
| Traction (company) | $3.6B annual transaction volume; ~8,000 advisers; ~170,000 end clients; >4,000 investor accounts |
Who uses the product — and for what job
Users: wealth managers, RIAs, banks, trust companies, and fund sponsors running alternatives programs.
Job: create vehicles → process subscriptions and approvals → normalize documents from outside portals → service investors and report — without stitching email, PDFs, e-sign, and sponsor portals for every client.
Modules (company): AIX (lifecycle), Access Vehicles (SPVs/feeders), Fund Factory (interval/tender funds), Document Intelligence, and a 1031 DST marketplace. Legal terms say Aqua is tech/admin/marketplace services — not a broker, custodian, or investment adviser.
Why now
- Private markets distribution into the wealth channel expanded faster than ops capacity.
- Marwaha’s stated pivot: demand shifted from consumer aggregation to adviser software that manages alts across many clients and sponsors.
- Series A funds engineering, partnerships, and custodian/sponsor integrations for that pivot — not a seed-stage product search.
Why Arthur Ventures — portfolio fit
Arthur Ventures repeatedly buys B2B workflow software outside the Bay Area hype cycle (same firm also returned in Perry Weather’s Series C the same week). Aqua’s pitch is configurable alts ops — messy, regulated, sticky — which fits that mandate better than competing on marketplace brand against CAIS/iCapital.
YC remains a prior backer from the S21 batch; Alumni Ventures is a follow-on style participant. Arthur Ventures, Alumni Ventures, and Gradient have
Competitive map
| Player | Position | Implication for Aqua |
|---|---|---|
| CAIS | Scale marketplace + post-trade; >$2B valuation coverage in 2025 | Distribution incumbency |
| iCapital | End-to-end lifecycle; large feeder footprint | Hard to out-brand; must win on implementation speed |
| Gridline | Startup peer with end-to-end alts stack | Direct feature overlap |
Aqua’s “first TAIP” marketing claim is hard to verify against those products. The investable question is whether configurable ops + document intelligence wins mid-market RIAs that will not rebuild on CAIS/iCapital.
What to watch
- Software ARR vs transaction-volume vanity metrics.
- How “~8,000 advisers” relates to paying seats and active AUA.
- Custodian integrations that shorten compliance reviews.
Sources
- FinSMEs
- FinTech Global
- RuntimeWire
- Day tape: Sep 9–12 roundup · Month: September 2026 VC news
Follow Venture Capital Tracker in Google
Add VCT as a preferred source to make our venture-capital coverage easier to find in Google Search.
Editorial note: AI tools assisted with research, structure, or drafting. Venture Capital Tracker retains human editorial responsibility for factual accuracy, relevance, and source quality before publication.