· Investment Strategies · 2 sources · Updated · Verified
Vantora Raises >$100M From Silversmith for Physical AI Venture Building
Former UP.Labs — now Vantora — took its first outside capital (>$100M, Silversmith) to build AI ventures industrial partners can own. Who uses the studio model and why growth equity fits.

By Venture Capital Tracker Editorial
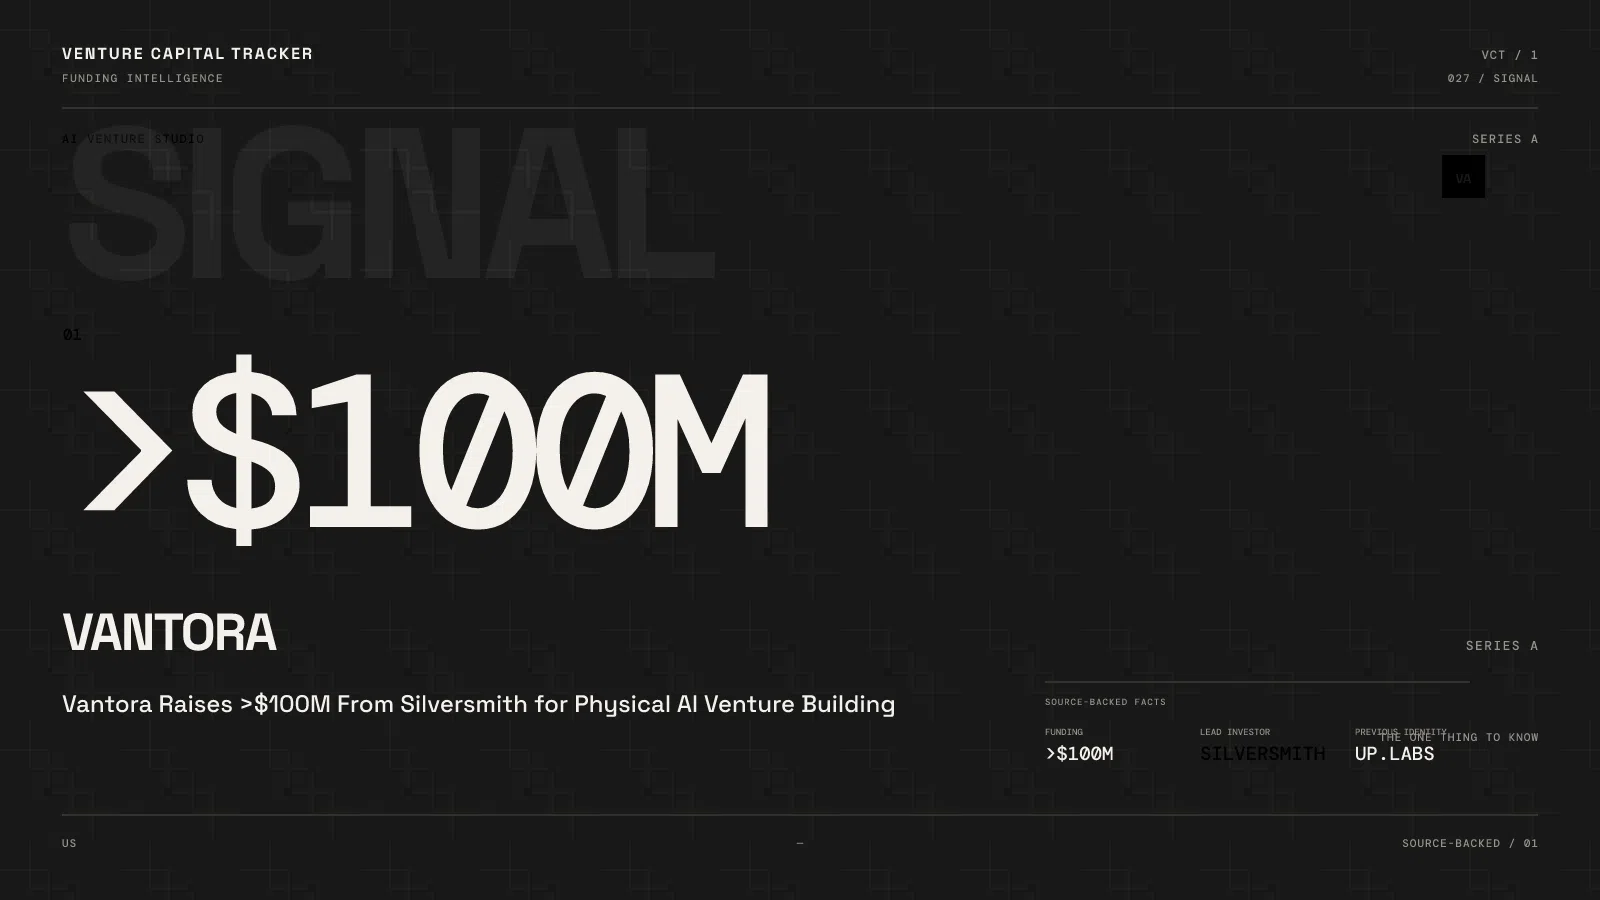
Vantora (formerly UP.Labs) took more than $100 million from Silversmith Capital Partners, announced September 16, 2026 (TechCrunch on September 18). First outside capital. Exact dollars above $100M, valuation, and ownership undisclosed.
industrial companies will not bolt generic AI onto legacy ops — Vantora sells equity-aligned venture builds that partners can eventually own, under a “Sovereign AI” label, with physical AI as the wedge.
Key facts
- Company
- Vantora — rebrand of UP.Labs (founded 2022)
- Round
- Growth / first outside capital
- Amount
- >$100M (floor disclosed)
- Investor
- Silversmith Capital Partners (Boston growth equity; >$5B AUM claimed)
- Board
- Todd MacLean, Danielle Waldman, Annie Cory (Silversmith)
- Traction (company)
- 17 ventures launched; target 20 by end-2026; revenue +79% YoY; profitable pre-raise
- Named partners
- Porsche (launch), Alaska Airlines, J.B. Hunt, Wabash, TDG
- Product
- COSMOS ontology + embedded venture teams
- Valuation
- Not disclosed
Who uses the product — and for what job
Users: Fortune-scale operators in energy, aviation, logistics, manufacturing, and automotive — not seed-stage founders shopping for an incubator.
Job: identify $50–$100M EBITDA-class problems (company framing), embed founders and AI engineers with the partner’s operators and data, then ship a venture or capability where the enterprise is investor + first customer + optional acquirer. TechCrunch’s Kuolt interview adds a “proprietary M&A pipeline” shift: partners can keep solutions in-house instead of forcing every build to be an outward product.
That is why physical AI unlocked: retrofitting machines for autonomy often cannot be sold to competitors — the old UP.Labs outward-product constraint blocked those deals.
J.B. Hunt’s CFO is quoted on disciplined problem selection — the buyer voice is ops finance, not innovation theater.
Why now
- McKinsey statistic in Silversmith’s release: 94% of organizations still fail to get significant earnings from AI — generic tools miss the P&L.
- Physical AI hype needs owned workflows and data, not another copilot seat.
- A profitable studio finally took institutional capital to scale partnerships and COSMOS — Silversmith’s Danielle Waldman: “Physical AI before there was even a name for it.”
Why Silversmith — portfolio fit
Silversmith writes first-institutional checks into tech and healthcare operators (Appfire, DistroKid, Iodine, LifeStance cited in its About). Vantora looks like a services-plus-product compounder: recurring partnership economics plus ontology software, not a classic seed fund GP.
**
| Investor | Fit |
|---|---|
| Silversmith | Growth equity; first-institutional playbook; board seats |
Strategic rationale: take one growth partner that understands multi-year enterprise cycles, give board seats for governance, and avoid a traditional VC that would push every venture toward a venture-scale exit instead of partner ownership.
Adjacent on our tape: Antioch sells simulation software — different product, same physical-AI keyword cluster.
Competitive map
- Corporate incubators / CVC studios — rarely give partners a clean path to own the intelligence layer.
- Physical-AI software vendors (simulation, teleop data) — sell tools; Vantora sells built companies.
- Up.Partners — office neighbor, not the same entity, not the capital provider.
What remains undisclosed
- Dollars above $100M and valuation.
- Per-venture ownership splits and which partners exercised buy-in.
- Revenue mix: studio fees vs COSMOS vs venture equity marks.
- Named oil-and-gas / manufacturing partners still withheld.
Implication
If the model works, Vantora is a bet that the next industrial AI winners are owned by the operators, not by SaaS vendors renting models. The open question is whether a studio that sells exclusivity can still compound COSMOS as a repeatable product — or whether each partner engagement stays bespoke forever.
Follow Venture Capital Tracker on Google
Add VCT as a preferred source to see more of our venture-capital reporting in Google Search.
Last updated:
Editorial note: AI tools assisted with research, structure, or drafting. Venture Capital Tracker retains human editorial responsibility for factual accuracy, relevance, and source quality before publication.